
Oct 16, 2026
Factor Friday - October 16, 2026
Size Continues to Lead as The Market Remains Flat
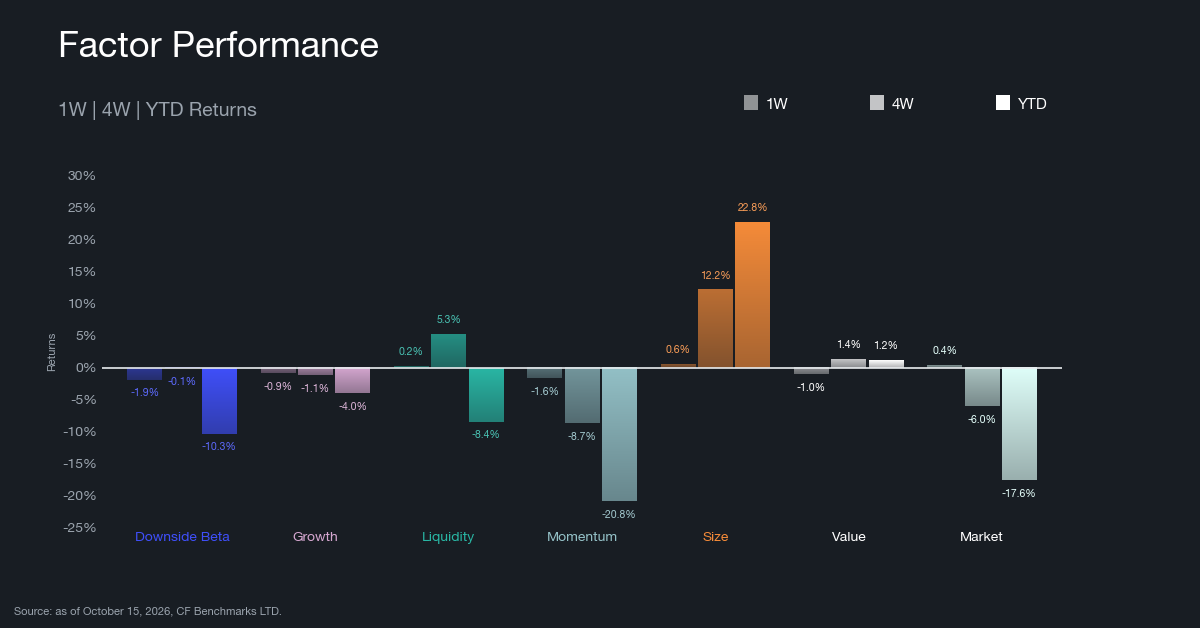
Size led the factor table for a third straight week at 0.59% as the Market rebounded 0.40% to rank second, after falling 4.98% last week. Liquidity (0.22%) was the only other factor to gain, while Growth (-0.89%), Value (-0.95%), Momentum (-1.58%) and Downside Beta (-1.86%) all lost ground. Over four weeks Size leads at 12.23%, ahead of Liquidity (5.25%) and Value (1.38%), Downside Beta (-0.05%) and Growth (-1.14%) sit near flat, the Market (-6.04%) is sixth and Momentum (-8.66%) last. Year to date, Size extended its lead to 22.81% from 22.09% a week earlier and Value held positive at 1.18%, while Growth (-4.02%), Liquidity (-8.44%) and Downside Beta (-10.31%) trail, and Momentum (-20.82%) and the Market (-17.59%) remain the two weakest. Breadth recovered, with 15 of 35 CF Broad Cap constituents closing higher against 2 a week ago, and the median constituent lost 0.15% after falling 8.68% the week before. Bitcoin (BTC) gained 0.92%. Because Size is a long-short factor, a positive print means smaller assets outperformed larger ones, but at 0.59% the margin was far narrower than last week's 2.58%. Momentum is the exposure to watch. It lost 1.58% in a week when the Market rose, the pattern of a rebound led by recent laggards rather than recent winners, and it ranks last over four weeks and year to date.
Rolling Factor Rankings and Rotation
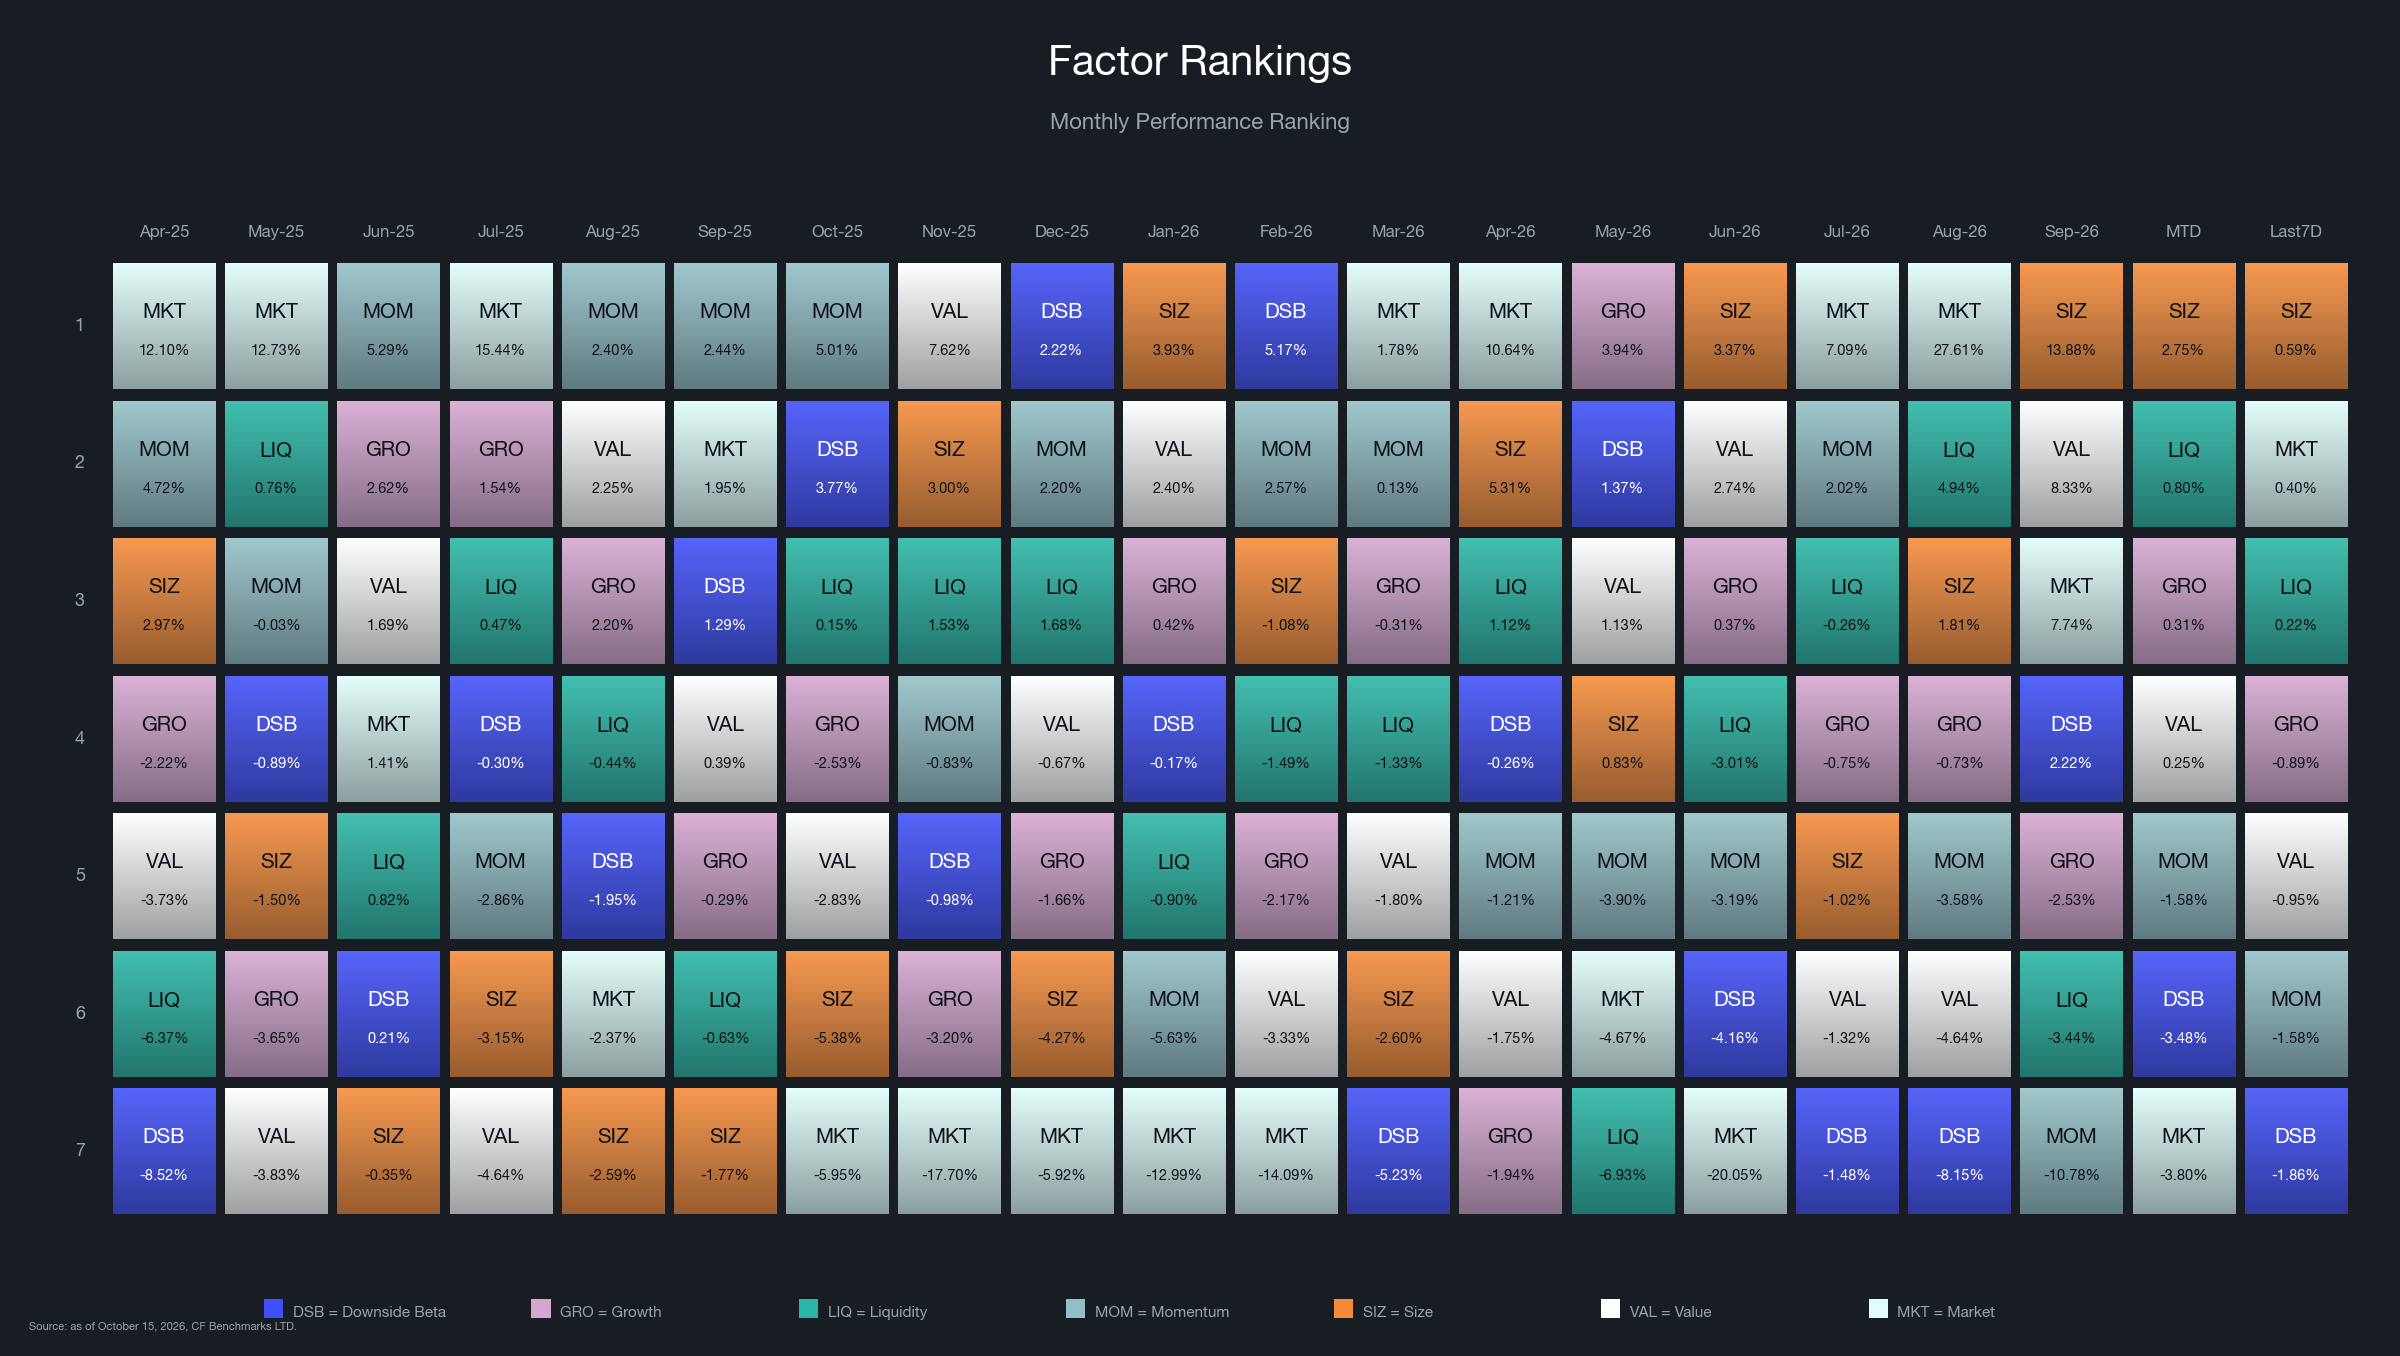
Size kept first place, but the order beneath it reshuffled. The Market jumped from last to second at 0.40%, Liquidity rose from fifth to third at 0.22%, Growth slipped from third to fourth at -0.89%, Value fell from second to fifth at -0.95%, Momentum dropped from fourth to sixth at -1.58%, and Downside Beta went from sixth to last at -1.86%. Month to date Size leads at 2.75%, followed by Liquidity (0.80%), Growth (0.31%) and Value (0.25%), while Momentum (-1.58%), Downside Beta (-3.48%) and the Market (-3.80%) are negative, with the Market last. Much of the change in the four-week table is the window. The Market's four-week return swung to -6.04% from 2.53% because the 11.70% gain posted in the week ending September 24 has largely left the window, leaving the weeks since at 0.07%, -4.98% and 0.40%. Liquidity's 5.25% four-week gain is likewise mostly the 4.61% week ending October 1, with this week adding 0.22%. Size is the only factor ranked in the top two on the weekly, four-week and year-to-date tables, yet its weekly print has narrowed from 8.86% to 2.58% to 0.59% over three weeks, so the lead now rests on the longer horizons. Size gives back gains when larger assets outperform, so a rebound that reaches the biggest tokens is the condition that would end the run.
Market and Key Factor Betas
Market Beta
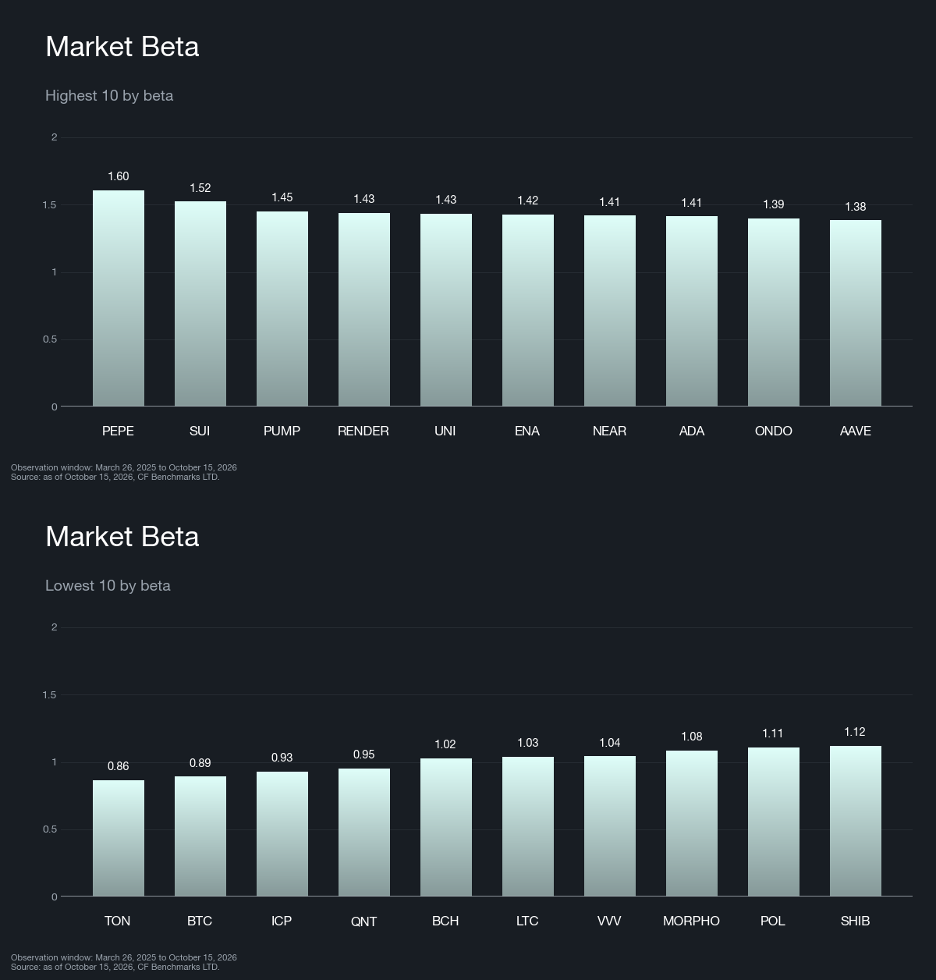
The Market rebounded 0.40% and breadth recovered sharply, with 15 of 35 CF Broad Cap constituents finishing higher against 2 a week ago. The median constituent lost 0.15% compared with 8.68% last week, and BTC, at a market beta of 0.89, gained 0.92% to finish ahead of it. The high market-beta roster is unchanged, a mix of meme-linked and launchpad tokens, DeFi protocols, AI compute and real-world-asset names and alternative layer-1 platforms. The low-beta ten is also unchanged, with Toncoin (TON) rising from 0.75 to 0.86, Venice (VVV) from 0.95 to 1.04 and Morpho (MORPHO) from 1.02 to 1.08 as their regression windows filled. The ten highest market-beta names returned an average 1.12% against 0.04% for the ten lowest, a gap of 1.1 percentage points (pp) that runs with a rising Market, compared with a 0.3 pp gap that ran marginally against a falling Market a week ago. The medians are 0.08% and -0.74%, a gap of 0.8 pp. The average leans on a few names. NEAR Protocol (NEAR, +18.46%) and Pepe (PEPE, +10.05%) rose sharply while Pump.fun (PUMP, -16.63%) fell, a 35.1 pp range inside the cohort, and excluding NEAR the ten highest average -0.81%, below the lowest ten. Exposure also differs less than the labels suggest, with the low ten between 0.86 and 1.12 and the high ten between 1.38 and 1.60. A tilt to high market beta paid slightly on average this week, but it paid through two or three tokens, so broad beta was a thin guide to which holdings recovered.
Size
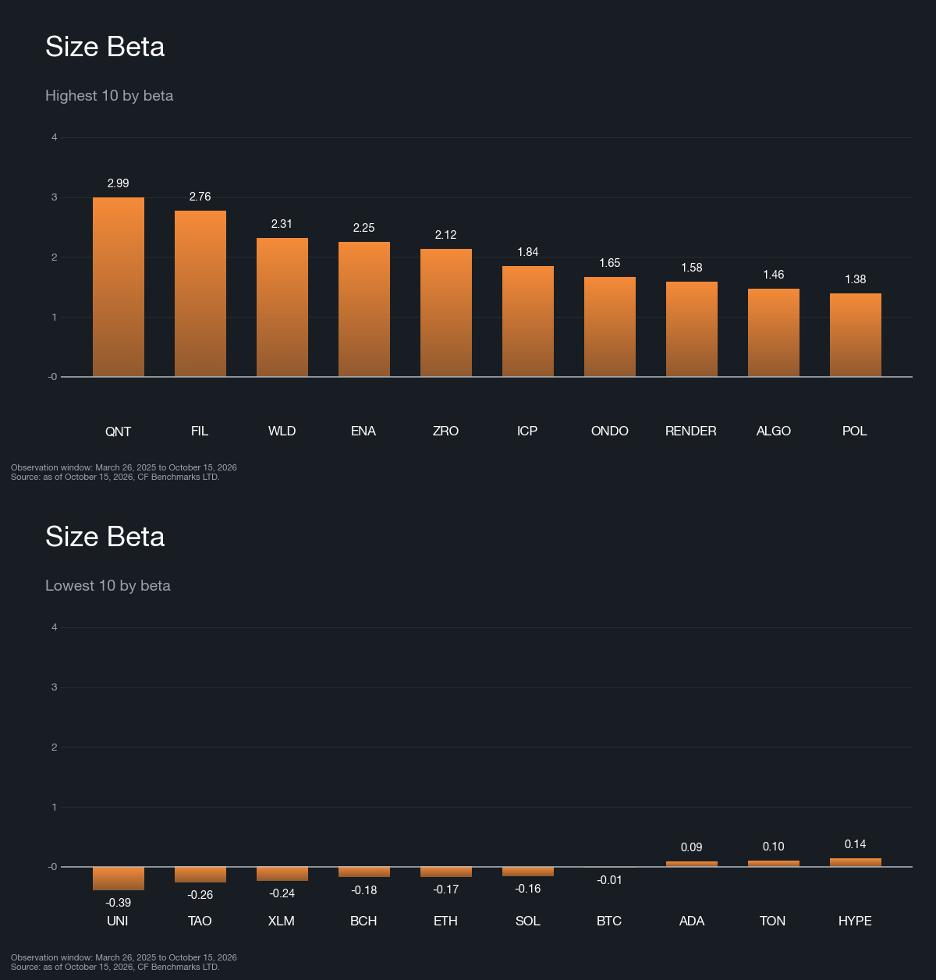
Size gained 0.59% and tops the table for a third week, though the weekly print has narrowed from 8.86% to 2.58% to 0.59%. The factor is sign-inverted, so a positive print means smaller assets outperformed larger ones. The ten highest size-beta names returned an average 1.05% against -0.24% for the ten lowest, a 1.3 pp spread in favor of smaller assets and the direction the print implies, though well below the 4.4 pp spread a week ago. The medians are 1.94% and -0.34%, a 2.3 pp spread. Quant (QNT) sits clear at the top of the high-beta list and fell 9.68%, and excluding it the cohort averages 2.24%, a spread of 2.5 pp, against 4.9 pp a week ago on the same excluding-QNT basis. Five of the ten highest rose, led by Filecoin (FIL, +7.71%) and Render (RENDER, +7.18%), and the lowest ten has outliers of its own, with Uniswap (UNI, +2.61%) and Bittensor (TAO, +3.50%) rising against a group otherwise made up of the largest networks and payment chains. Excluding UNI and TAO the lowest ten average -1.07%, which widens the excluding-QNT spread to 3.3 pp. The spread therefore ranges from 1.3 pp to 3.3 pp depending on which tokens are removed, and it holds in the factor's direction under every cut. The composition barely changed. Polygon (POL) entered the highest ten as VVV left, and TON entered the lowest ten as XRP left, and the high end is still drawn from interoperability, storage, AI compute, real-world-asset and DeFi tokens. Size scores barely moved because they track market capitalization, with the largest change just 0.02. Only two of 35 names switched sides, TAO from long to short and SHIB from short to long, both at about 0.22, the median split between the two sides, so a short-side name can carry a positive score. This week's return therefore reflects price action. A three-week narrowing from 8.86% to 0.59% suggests the bid for smaller assets is fading even as the cumulative lead holds, and a rebound led by larger assets would be the test.
Momentum
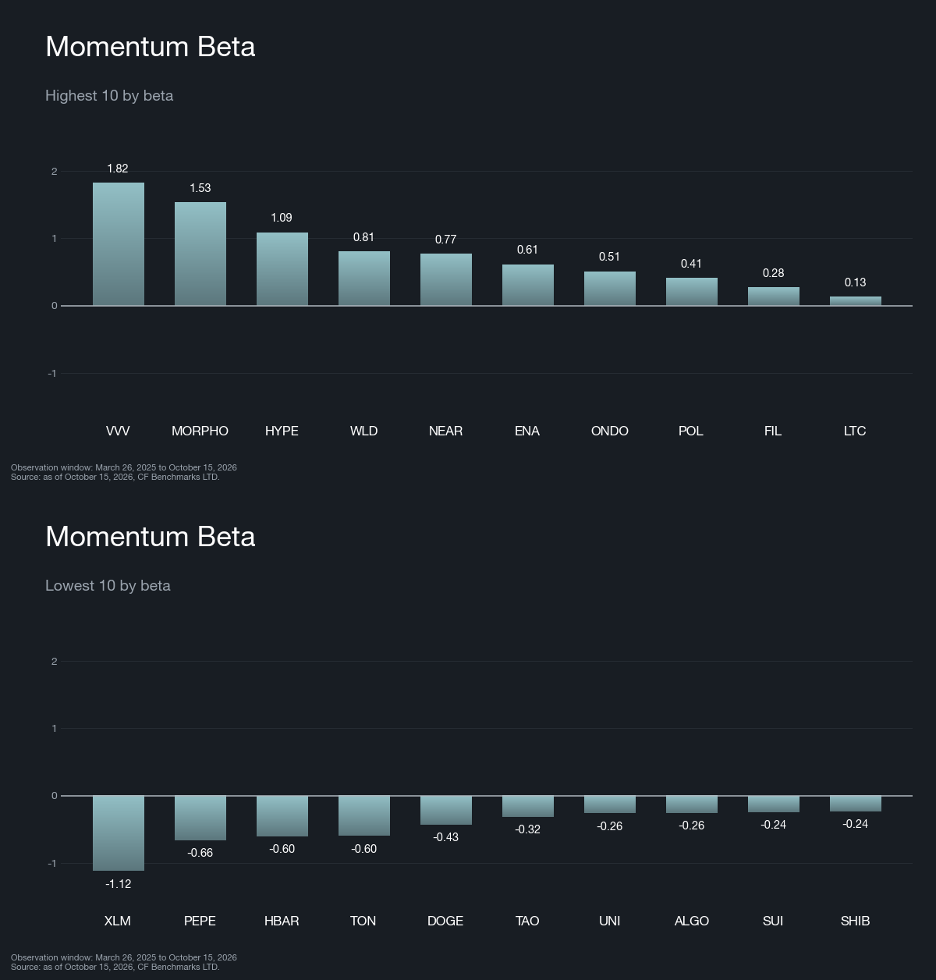
Momentum fell 1.58% while the Market rose, so recent winners did not lead the bounce. It ranks last over four weeks (-8.66%) and year to date (-20.82%), and three of the last four weekly prints have been negative. The beta cohorts do not explain the move. The ten highest momentum-beta names returned an average 3.28% against -0.34% for the ten lowest, a 3.6 pp gap that runs against a negative print, and the medians (1.10% against -1.49%) agree at 2.6 pp. The result survives the obvious outlier checks, since excluding NEAR from the highest ten and PEPE from the lowest ten still leaves a 3.1 pp gap against the print. A week ago the same cohorts ran with the print, by 4.6 pp. The high-beta ten is mainly DeFi, AI and real-world-asset tokens, with Litecoin (LTC) entering as Polkadot (DOT) left, while the lowest ten is meme coins and payments and enterprise chains. Beta measures sensitivity to the factor, and the return comes from the portfolio, which is built from the momentum scores themselves, so the portfolio is the better guide. Entering the week QNT carried the highest momentum score at 5.00 against 1.45 for the next highest, and PUMP held the third at 1.13. QNT fell 9.68% and PUMP 16.63%. On the short side VVV (+10.55%) and PEPE (+10.05%) rallied, along with DOT (+8.58%). A leader falling while laggards rally is how Momentum loses in a rebound. QNT's score fell from 5.00 to 0.11, the sharpest swing in the portfolio, though it remains on the long side. LayerZero (ZRO) rose from 1.45 to 3.57 to become the highest-scoring name, and Hedera (HBAR) fell from -0.18 to -2.18, the deepest short. The portfolio also turned over heavily, with 12 of 35 names changing sides. BTC and PEPE moved to the long side, and Chainlink (LINK) and Ethena (ENA) moved to the short side. With membership churning at that rate, last week's portfolio says little about the next one, and a Momentum print will keep reflecting a handful of high-scoring names until the rebound settles on a set of winners.
What Factors are Driving Markets
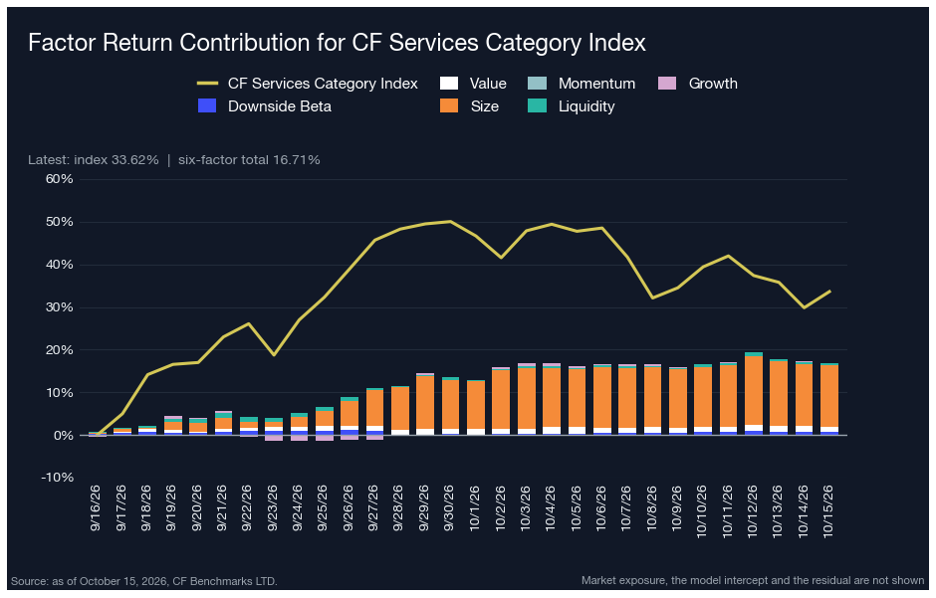
In the CF DACS Services universe, factor contributions total 16.71% against an index return of 33.62%, a 16.9 pp gap with the index ahead, compared with 3.4 pp last week as published. The widening is mostly the window, since the roll lifted the index by 13.8 pp and the sleeve by 1.7 pp, which accounts for 12.1 pp of the 13.5 pp change, and this week's moves of 1.5 pp and 0.1 pp account for the rest. The factor sleeves are log contributions while the index is a simple return, so the gap is overstated, and on a like-for-like basis it is 12.3 pp against 1.9 pp last week. Size accounts for nearly all of the sleeve at 14.44%, with Value (1.16%) and Downside Beta (0.79%) next and Liquidity (0.39%), Momentum (-0.02%) and Growth (-0.05%) negligible. The index rose 1.15% on the week, with Chainlink (LINK), at 41.83% of the weight, up 0.68% for about 0.3 pp of gain, and QNT, at 14.01%, down 9.68% for about 1.4 pp of drag. Last week's report noted that a QNT reversal would reach the index before it reached the Size contribution, and that held again, since Size added 0.6 pp this week while QNT trailed the index by 10.8 pp. VVV (+10.55%) led, 9.4 pp ahead of the index, with FIL 6.6 pp ahead. The six style factors now equal about 50% of the 30-day index return, down from 81%, partly the roll and partly the basis, and the model's Market exposure, which added 10.24% on the log basis, is not in the sleeve. Size remains the exposure underneath the index.
In the CF DACS Services universe, factor contributions total 14.91% against an index return of 18.30%, a 3.4 pp gap that narrowed sharply from 34.4 pp. Size accounts for almost the entire sleeve at 12.54%, with Value adding 1.57% and Momentum (-0.10%) the only drag. The index fell 10.01% on the week, with Chainlink (LINK), at 41.83% of the weight, down 13.48% and QNT, at 14.01%, down 9.58%. Last week's report noted that a QNT reversal would reach the index before it reached the Size contribution. The 30-day index return fell by 29.9 pp, from 48.21% to 18.30%, but 17.1 pp of that is early-September gains rolling out of the window and 12.8 pp is this week's move. On the same like-for-like basis the Size contribution rose 2.7 pp, so the decline reached the index and not the sleeve, although QNT accounts for only about 1.3 pp of the index's weekly fall against about 5.9 pp for LINK. ZRO led at 10.38%, 20.4 pp ahead of the index, and no constituent trailed by more than 4.4 pp, with VVV the weakest at -14.41%. The six style factors now equal about 81% of the 30-day index return, up from 29%, although part of that move is the window roll and the model's Market exposure, which added 4.28% over the window, is not in the sleeve. That leaves Size as the exposure to watch.
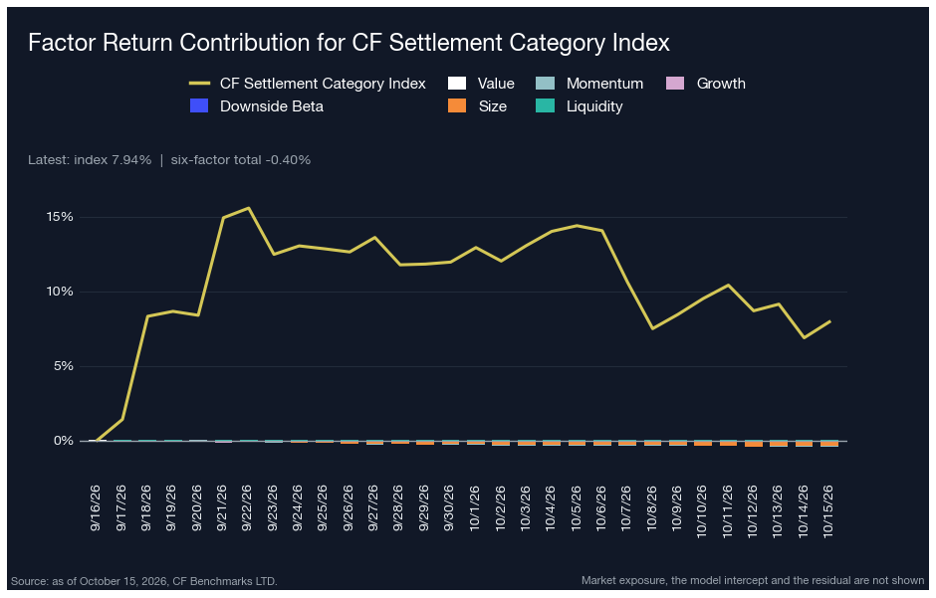
The Settlement universe, dominated by Bitcoin, again shows the weakest link to the style factors, which is expected because Market exposure sits outside the set and BTC is about 74% of the index. Factor contributions total -0.40% against an index return of 7.94%, an 8.3 pp gap, up from 3.6 pp last week, and Size (-0.27%) is the only factor larger than 0.06 pp in either direction. The widening is mostly the window, with the roll adding 4.2 pp to the index and this week's move 0.5 pp. Market exposure alone contributed 7.58% over the window on the model's log basis, nearly all of the index return. The index rose 0.43% on the week, with BTC (+0.92%, 74.21% of the weight) ahead of Ether (ETH, -0.14%) and Solana (SOL, -2.71%), which trailed the index by 3.1 pp. NEAR (+18.46%) led on a weight under 0.4%, 18.0 pp ahead of the index, followed by DOT (+8.58%), 8.2 pp ahead on a near-zero weight, so the outperformers were too small to move the index. That makes Settlement a read on Bitcoin and Market exposure more than on the style factors.
Appendix: CF Factor Methodology
Market Factor
The market factor captures the broad, systematic risk that permeates the digital asset ecosystem. It reflects aggregate influences such as macroeconomic conditions, investor sentiment, and overall market volatility. As such, this factor is defined by the daily returns of the CF Broad Cap (Free Float Market Cap Weight) Index, offering a comprehensive and capitalization-weighted representation of the asset class.
Size Factor
The size factor captures the return differential associated with asset scale, reflecting the hypothesis that smaller-cap digital assets tend to outperform their larger-cap counterparts. This effect is understood to compensate for elevated operational and financial risks while exploiting potential market inefficiencies. In this framework, the size factor is defined by each asset’s fully diluted market capitalization. The value is sign-inverted so that higher z-scores are assigned to smaller assets and vice-versa.
Value Factor
The value factor reflects a protocol’s ability to generate economic output relative to its capital base and market valuation, combining measures of both efficiency and user engagement. It is constructed as the average z-score of two key ratios: transaction fees relative to total value locked (Fees/TVL) and daily active users relative to market capitalization (DAU/MCap). This composite metric captures how productively a protocol utilizes its resources while also serving as a proxy for user-driven demand. A higher combined score indicates efficient resource utilization and strong user engagement.
Momentum Factor
The momentum factor captures short-term price persistence by identifying assets that have recently exhibited strong performance. It is computed as the average z-score of two metrics: the 2 weeks cumulative performance and the 2 weeks risk-adjusted cumulative performance. This approach aligns with established findings in traditional financial literature and demonstrates empirical relevance in digital assets, where price trends tend to exhibit momentum over short horizons.
Growth Factor
The growth factor captures the expansion of a protocol’s network activity and user adoption. In the context of digital assets, it reflects metrics such as fee generation and user engagement, which serve as indicators of increased platform utilization and operational scale. The factor is defined as the average z-score of 30-day fee growth and 30-day weekly active user growth, thereby identifying assets exhibiting consistent and measurable increases in underlying network usage.
Downside Beta
The downside beta factor captures an asset’s sensitivity to adverse market conditions by isolating its behavior during periods of negative market returns. Empirical evidence shows that assets with lower downside beta tend to outperform their higher-beta counterparts over the long-term, due to their reduced participation in market drawdowns and more stable return profiles during periods of elevated volatility. As such, it is estimated through a regression of the asset’s daily returns over the most recent four-week period against market returns observed exclusively during negative sessions. The resulting value is sign-inverted to ensure that assets with lower downside exposure are assigned higher z-scores.
Liquidity Factor
The liquidity factor captures the ease with which a digital asset can be traded without significantly impacting its price. Empirical evidence shows that illiquid assets tend to command a higher risk premium than their more liquid counterparts, serving as compensation for trading friction and price volatility. To quantify this, the factor is measured using token turnover, defined as trading volume as a percentage of circulating supply. The value is sign-inverted such that higher z-scores are assigned to less liquid assets.
For further detail, view the CF Factors Methodology Document, the CF Factor Data Suite, and Our paper “A Factor Model for Digital Assets” in Springer Nature’s Mathematical Research for Blockchain Economy.
The information contained within is for educational and informational purposes ONLY. It is not intended nor should it be considered an invitation or inducement to buy or sell any of the underlying instruments cited including but not limited to cryptoassets, financial instruments or any instruments that reference any index provided by CF Benchmarks Ltd. This communication is not intended to persuade or incite you to buy or sell security or securities noted within. Any commentary provided is the opinion of the author and should not be considered a personalised recommendation. Please contact your financial adviser or professional before making an investment decision.
Note: Some of the underlying instruments cited within this material may be restricted to certain customer categories in certain jurisdictions.
Factor Friday - October 16, 2026
Size led the factor table for a third week at 0.59% as the Market rebounded 0.40% and 15 of 35 Broad Cap tokens closed higher. Momentum fell 1.58% in a rebound led by laggards, and Size's weekly print has narrowed from 8.86% to 0.59% in three weeks, even as its year-to-date lead holds at 22.81%.
Mark Pilipczuk
Launch of the CF HODLife HARD Index
The Administrator announces the launch of the CF HODLife HARD Index, a co-branded benchmark developed by CF Benchmarks and HODLife, an insurance technology company.
Mark Pilipczuk
Changes to the Token Market Price Benchmarks Series - Market Prices – 13 October 2026
The Administrator has confirmed changes to the Token Market Price Family for the period 06 October 2026 to 13 October 2026
CF Benchmarks
By clicking Accept, you consent to CF Benchmarks's use of cookies.
Visit Cookie Settings to learn how CF Benchmarks uses cookies and to adjust your preferences.