
Nov 06, 2026
Factor Friday - November 6, 2026
Downside Beta leads as the Market falls
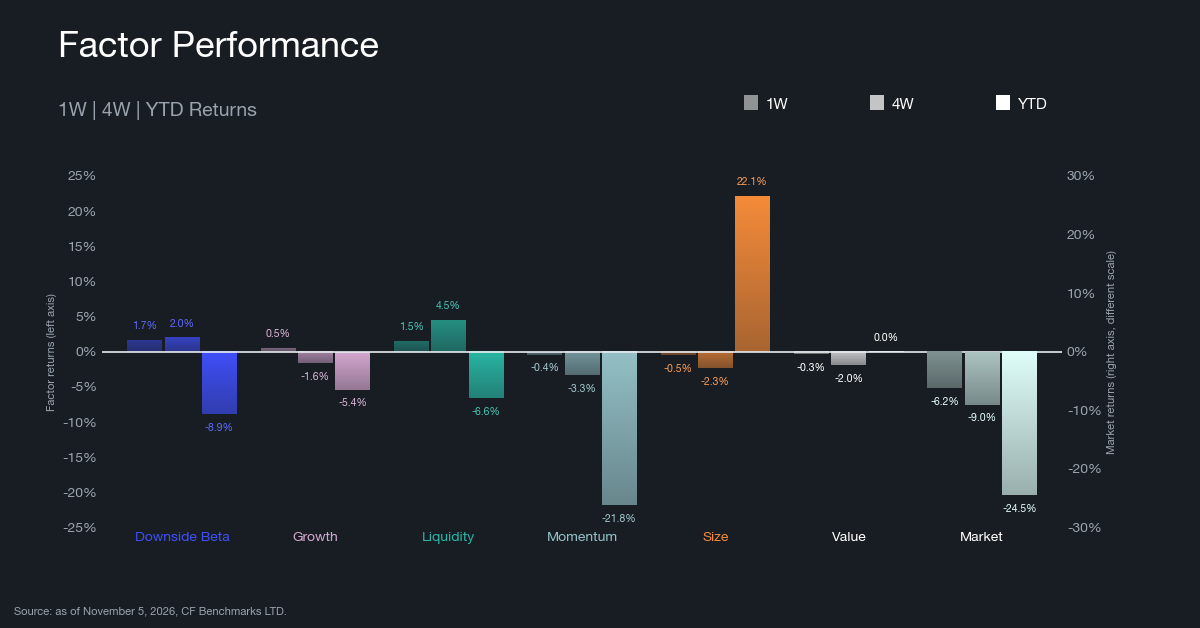
Downside Beta led the factor portfolios at +1.66% in a week the Market fell 6.17%, its largest weekly loss since the week to June 25. Liquidity (1.51%) and Growth (0.50%) also gained, while Value (-0.35%), Momentum (-0.41%) and Size (-0.50%) declined, so the six style factors finished within 2.2 percentage points (pp) of each other. Over four weeks Liquidity leads at 4.46%, ahead of Downside Beta (2.04%), Growth (-1.63%), Value (-1.96%), Size (-2.28%) and Momentum (-3.31%), with the Market (-9.03%) last. Year to date Size leads at 22.14%, down from 22.76% a week earlier, followed by Value (0.03%), Growth (-5.39%), Liquidity (-6.60%), Downside Beta (-8.92%) and Momentum (-21.81%), with the Market (-24.47%) now below Momentum at the bottom of the table. Breadth narrowed to 1 of 35 CF Broad Cap constituents closing higher, against 8 a week ago, and the median constituent lost 7.43% after losing 3.18%. Bitcoin (BTC) fell 5.86%, 1.6 pp ahead of the median. The ten highest downside-beta tokens beat the ten lowest by 5.0 pp, in the factor's direction, and the gap holds when the largest single moves are removed. Liquidity is the less certain read. Its second straight gain came with a cohort gap of only 1.1 pp, down from 10.4 pp last week, and the medians run against it. Most of the week's loss came before November, as the Market is down 2.34% month to date against 6.17% on the week. A rebound in beta would test Downside Beta's lead.
Rolling Factor Rankings and Rotation
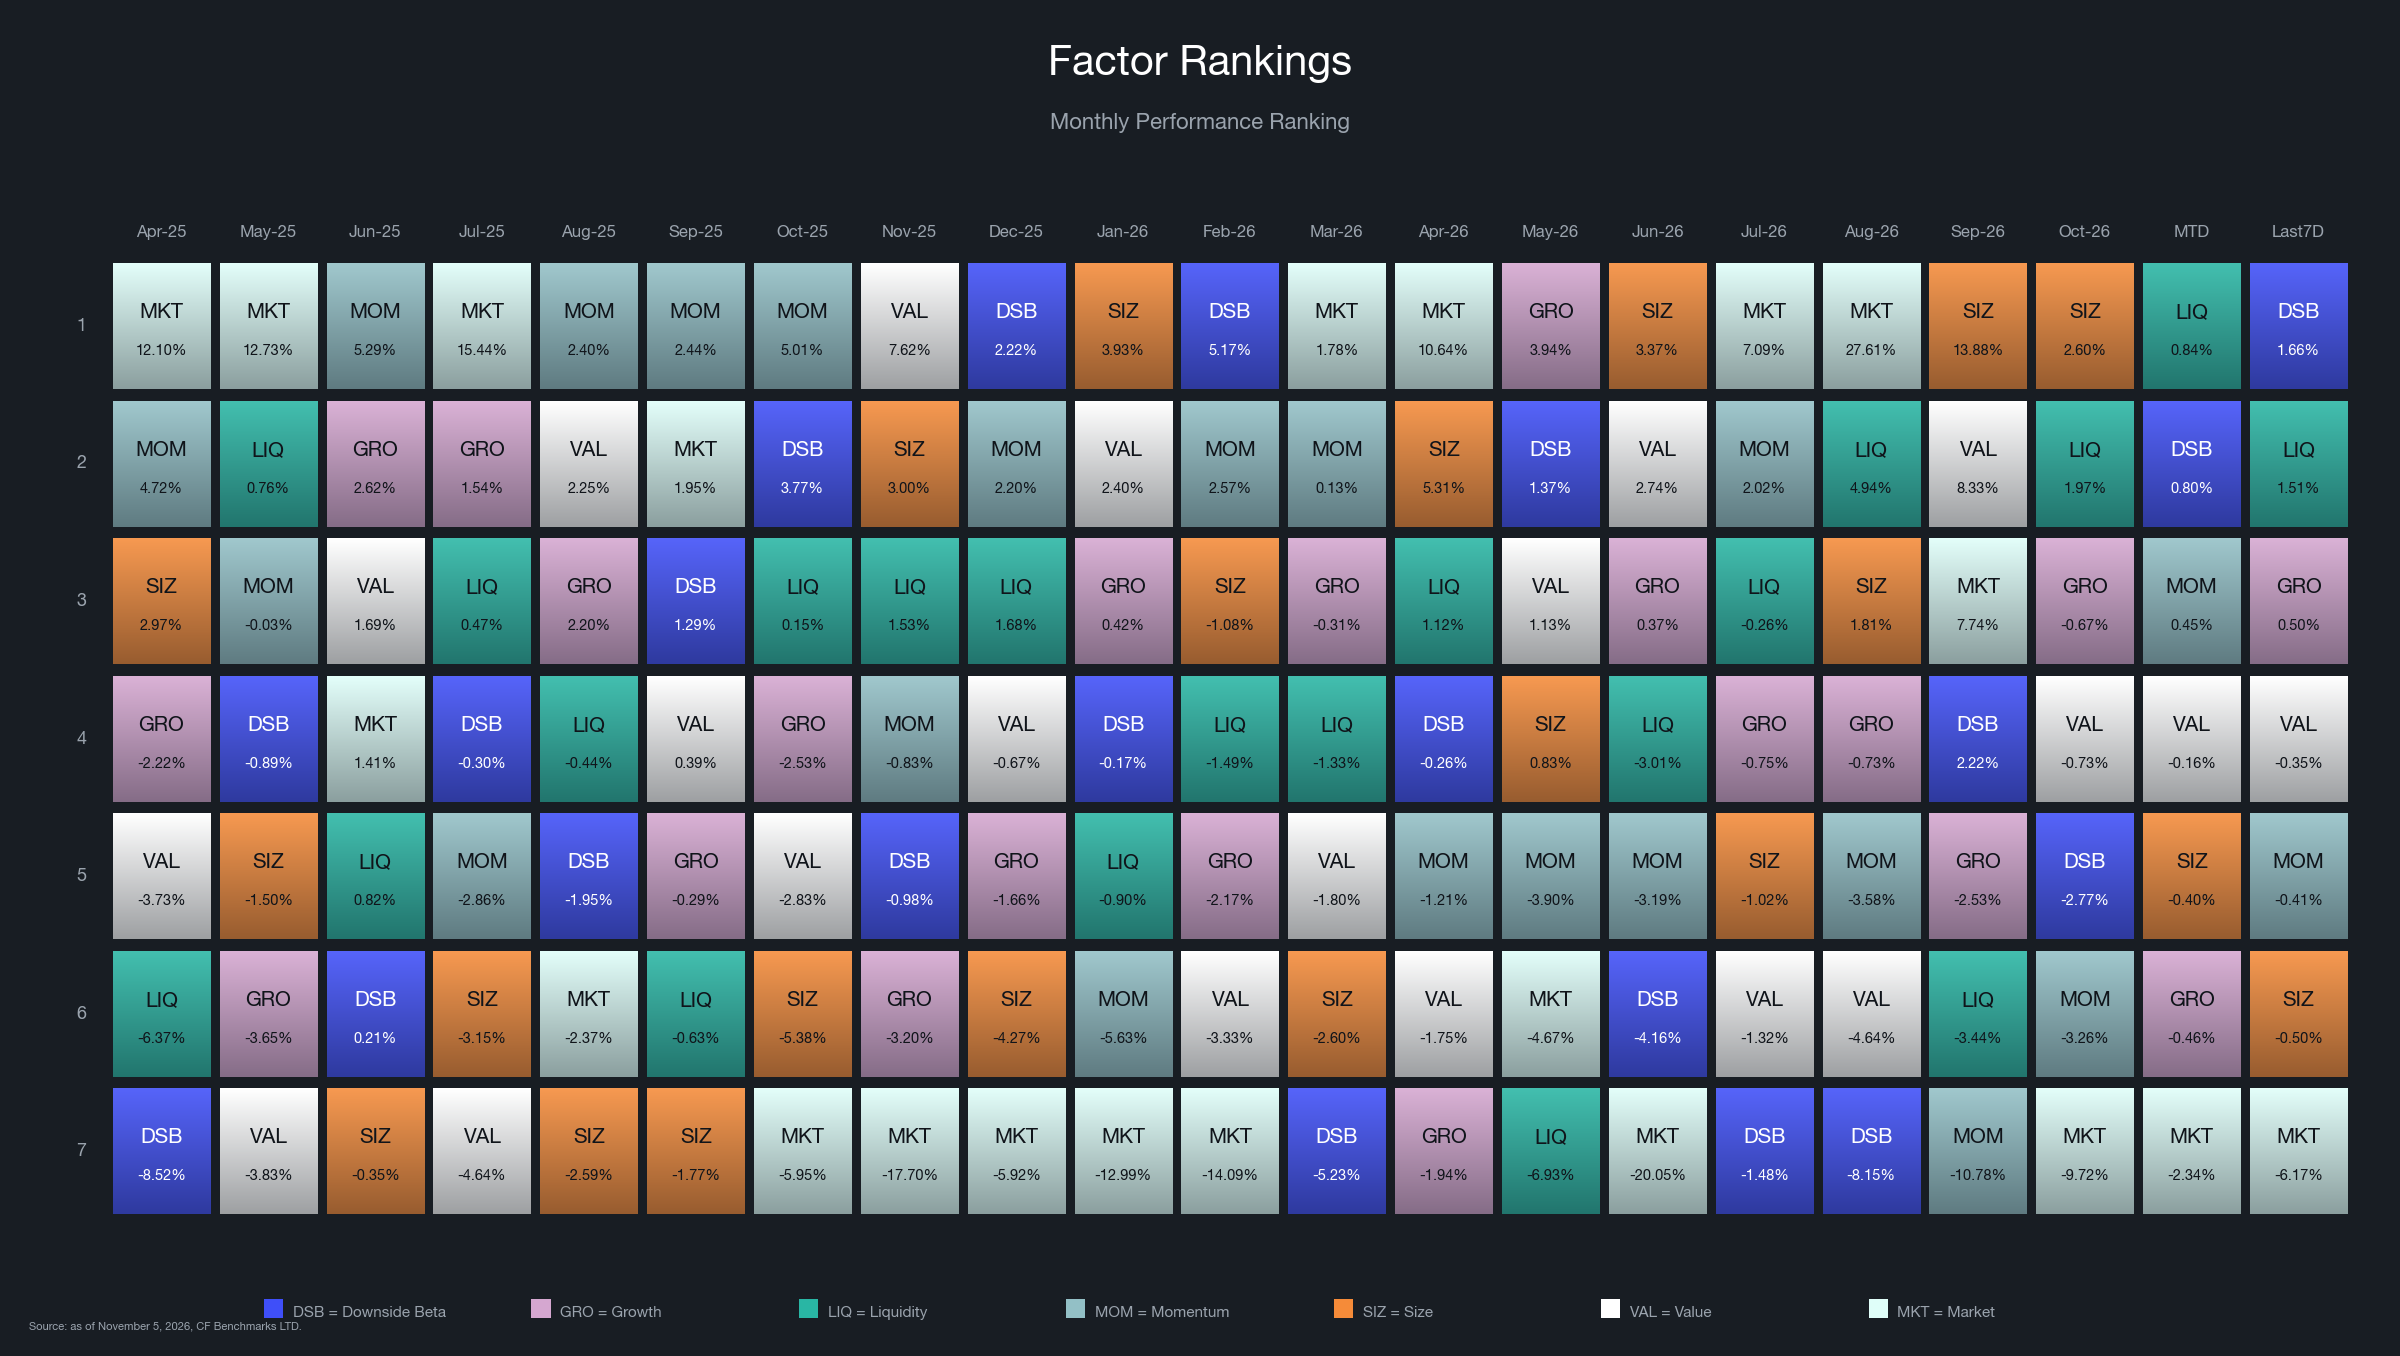
Leadership moved from Liquidity to Downside Beta on the weekly table, a defensive tilt that matched a falling Market. Downside Beta rose from second to first at 1.66%, Liquidity slipped from first to second at 1.51%, Growth recovered from last to third at 0.50%, and Value (-0.35%) fell from third to fourth. Momentum (-0.41%) slipped from fourth to fifth, Size (-0.50%) stayed sixth, and the Market dropped from fifth to last at -6.17%. The six style factors sat inside a 2.2 pp range while the Market lost 6.17%, so style selection accounted for little of the week's move. Liquidity has now gained two weeks running, at 1.54% and 1.51%, its first back-to-back gain since the weeks to August 20 and August 27, and it moved from second to first on the four-week table at 4.46% from -0.19%. It also leads month to date at 0.84%, ahead of Downside Beta (0.80%), Momentum (0.45%), Value (-0.16%), Size (-0.40%), Growth (-0.46%) and the Market (-2.34%). Size ended October first at 2.60%, ahead of Liquidity (1.97%), and has since fallen to fifth month to date. Its four-week return fell to -2.28% from 0.88%, a 3.2 pp decline against a 0.50% loss on the week, and the rest is the window as the days from October 6 to October 12 left it. Its last five weekly prints have run 2.58%, 0.59%, 0.75%, -0.79% and -0.50%. Size still leads year to date. The Market's four-week return fell to -9.03% from -8.02%, and its year-to-date loss widened to -24.47% from -19.51%, taking it below Momentum (-21.81%) at the bottom of that table. If the Market recovers, Downside Beta is exposed to a reversal. If the decline extends, Liquidity is the factor under test, with its lead resting on a cohort gap of 1.1 pp.
Market and Key Factor Betas
Market Beta
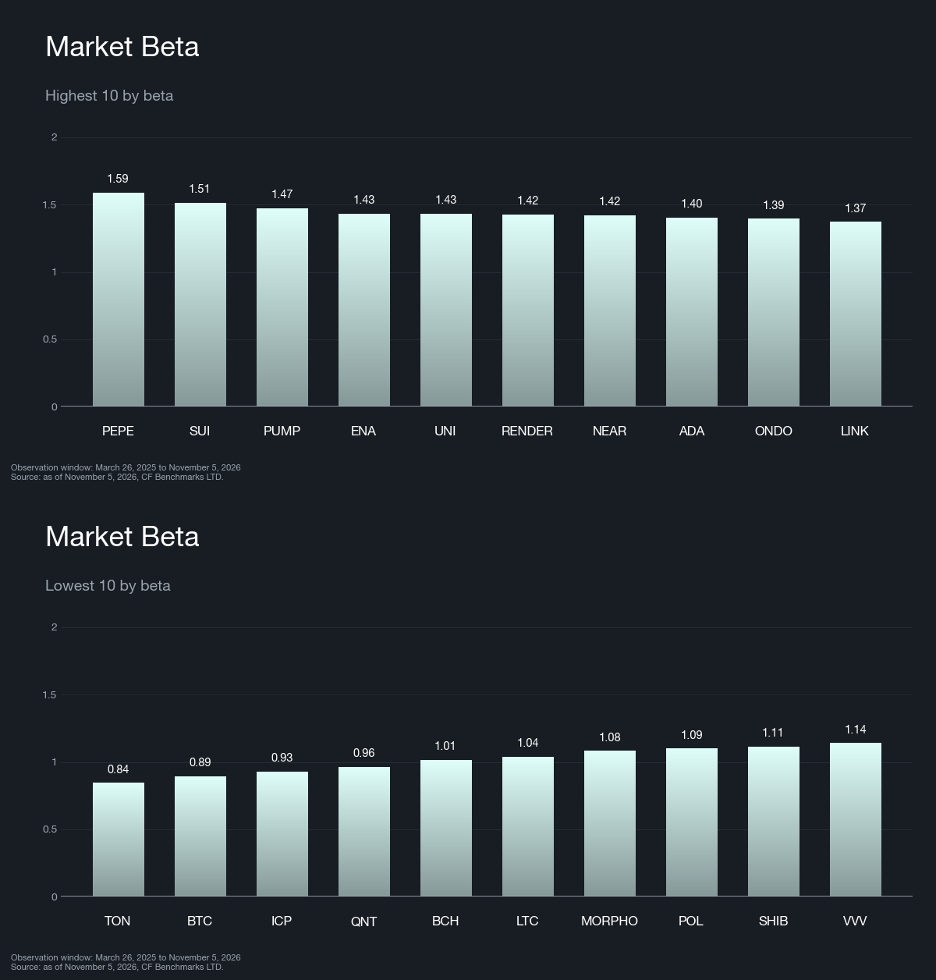
Broad exposure took the week's loss. The Market fell 6.17%, and only 1 of 35 CF Broad Cap constituents finished higher, Polygon (POL) at +2.17%, against 8 a week ago. The median constituent, Chainlink (LINK), lost 7.43% after 3.18% last week. BTC, at a market beta of 0.89, fell 5.86%, 0.3 pp ahead of the Market. Ethena (ENA) fell furthest at -21.45%, ahead of Worldcoin (WLD, -17.88%) and Hyperliquid (HYPE, -17.06%). The high market-beta roster changed by one name, with LINK entering at 1.37 as LayerZero (ZRO) left. It remains a mix of meme-linked and launchpad tokens, DeFi protocols, AI compute and real-world-asset names, alternative layer-1 platforms and an oracle token. The low-beta ten also changed by one name, with Venice (VVV) entering at 1.14 as Stellar (XLM) left. It holds Bitcoin and two of its forks, two layer-1 platforms, an interoperability token, a scaling network, a lending protocol, a meme coin and an AI token. The ten highest market-beta names returned an average -10.11% against -5.55% for the ten lowest, a 4.6 pp shortfall that runs with the print, and the medians (-8.56% and -6.39%) are 2.2 pp apart in the same direction. Last week the two cohorts averaged within 0.1 pp of each other. Returns inside the high-beta cohort ranged 17.0 pp, from Uniswap (UNI, -4.41%) to ENA. Excluding ENA, the ten highest average -8.85%, 3.3 pp below the lowest ten. Excluding POL, the one riser in the lowest ten, the gap is 3.7 pp, so the cohorts run with the print under each cut. Beta ordered returns this week, which it did not last week, so the highest-beta roster carries the most exposure if the decline extends.
Downside Betas
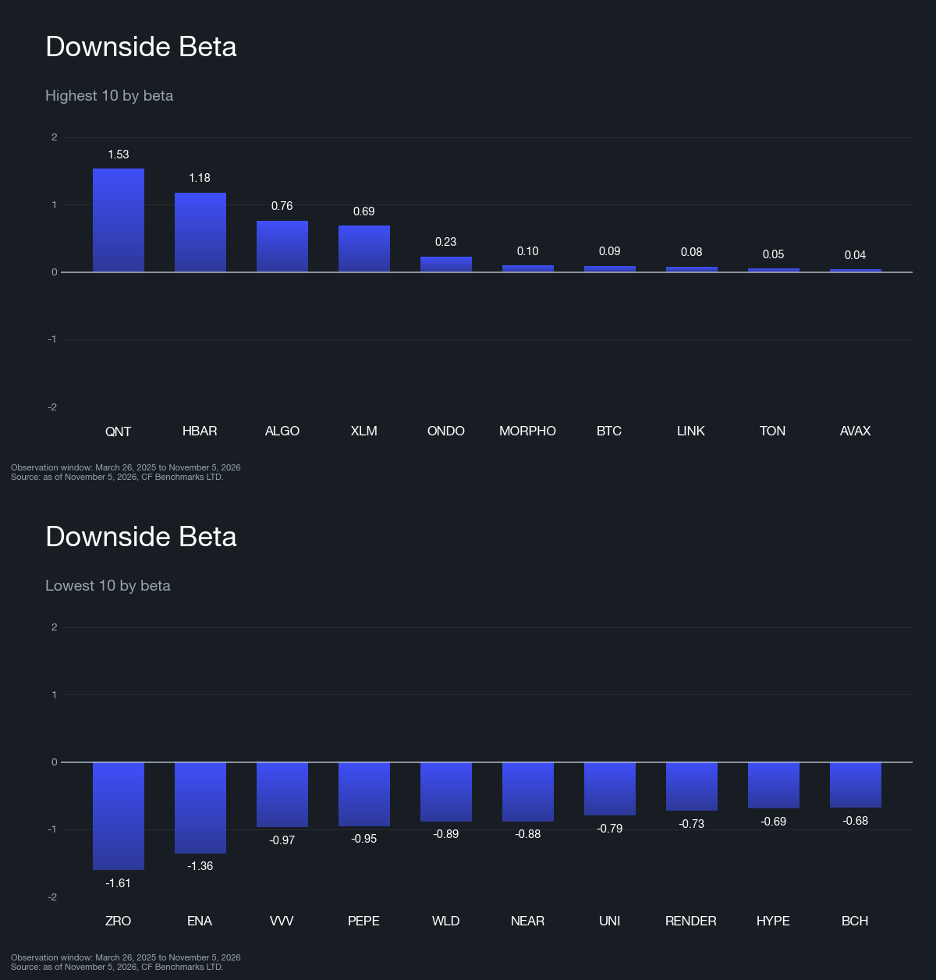
Downside Beta gained 1.66% to rank first, up from second last week, and has now gained two weeks running after 0.68%. Its four-week return improved to 2.04% from -2.85%, moving it from fifth to second, and its year-to-date loss narrowed to -8.92% from -10.41%. The factor is sign-inverted, so a positive print means tokens with lower sensitivity to adverse market conditions outperformed those with higher sensitivity, the result a 6.17% Market decline favors. This time the beta cohorts confirm the print. The ten highest downside-beta names returned an average -6.18% against -11.22% for the ten lowest, a 5.0 pp gap in the factor's direction, and the medians (-6.69% and -10.66%) are 4.0 pp apart in the same direction. Last week the cohorts ran against the print, with the highest ten averaging -4.41% against 0.38% for the lowest, a gap of 4.8 pp the wrong way. The result survives a cut at either end. Excluding ENA, the worst name in the lowest ten, the gap is 3.9 pp, and with Quant (QNT), the best name in the highest ten at -0.65%, also excluded it is 3.3 pp. The highest ten is led by QNT at 1.53, clear of Hedera (HBAR) at 1.18 and the rest. The group otherwise draws on payment and enterprise chains, real-world-asset, lending and oracle tokens, BTC (0.09) and layer-1 platforms, with Avalanche (AVAX) entering at 0.04 as Polkadot (DOT) left. The lowest ten holds interoperability, synthetic-dollar, AI, meme, identity, DEX, perpetuals-exchange, layer-1 and Bitcoin-fork tokens, with VVV entering at -0.97 as Bittensor (TAO) left. Score moves were modest and none passed 1.5 points. Bitcoin Cash's (BCH) score rose by 1.10 to 1.63 and stayed on the long side. WLD's rose from -0.93 to 0.08, which moved it to the long side after a 17.88% weekly loss. Cardano (ADA) also moved to the long side, and Aave (AAVE) and Toncoin (TON) moved to the short side. A Market rebound is the test. The factor is long the tokens that fall least in sell-offs, so it gives back when the names that fell hardest recover first.
Liquidity
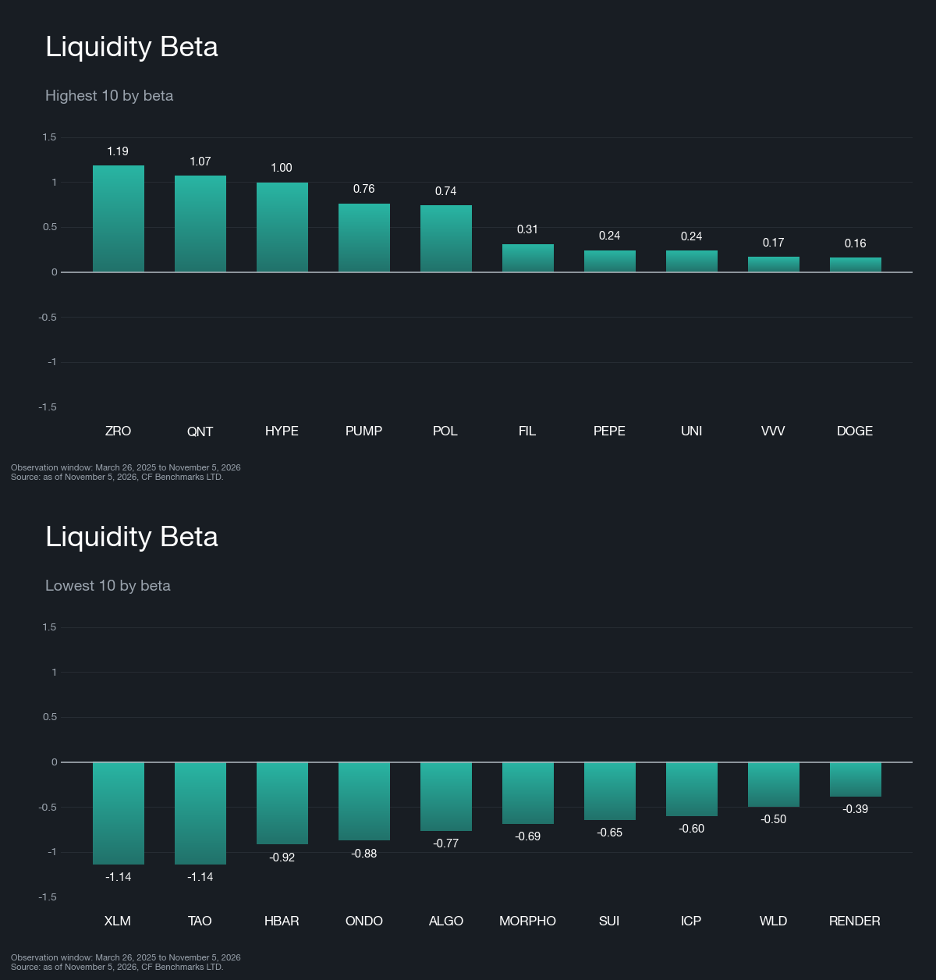
Liquidity gained 1.51% to rank second, down from first last week at 1.54%, its second straight gain. It leads month to date at 0.84%, and its four-week return rose to 4.46% from -0.19%, first on that table. The factor is sign-inverted, so a positive print means less liquid assets outperformed more liquid ones, even with the Market down 6.17%. The beta cohorts give a weaker answer than last week. The ten highest liquidity-beta names returned an average -7.26% against -8.35% for the ten lowest, a 1.1 pp gap in the factor's direction, down from 10.4 pp last week, and the medians (-8.48% and -7.31%) are 1.2 pp apart the wrong way. The average rests on one token. POL is the only riser in the highest ten, and excluding it the two cohorts average -8.31% and -8.35%, level to within 0.1 pp. WLD sits in the lowest ten. Excluding it leaves that cohort at -7.29%, and with POL also removed the highest ten trail by 1.0 pp, against the print. The highest ten mixes interoperability, perpetuals-exchange, meme-launchpad, scaling, storage, DEX, AI and meme tokens, with VVV entering at 0.17 as BCH left. ZRO's beta rose from 0.99 to 1.19, passing QNT, which eased from 1.10 to 1.07. HYPE's rose from 0.92 to 1.00. The lowest ten holds payment and enterprise chains, AI and compute tokens, identity, real-world-asset and layer-1 platforms and a lending protocol, with Morpho (MORPHO) entering at -0.69 as AVAX left. Turnover was heavy near the median split between the long and short sides. Eight names changed sides, Filecoin (FIL), WLD, HBAR and Ether (ETH) to the long side and AAVE, Solana (SOL), UNI and Litecoin (LTC) to the short, and UNI and ETH reversed last week's moves. QNT's score rose by 2.77 to -1.13, a move toward the less liquid side that left it on the short side. Until the cohort gap widens again, the print reads as a narrow tilt toward a few thinner tokens rather than a broad reach for less liquid assets.
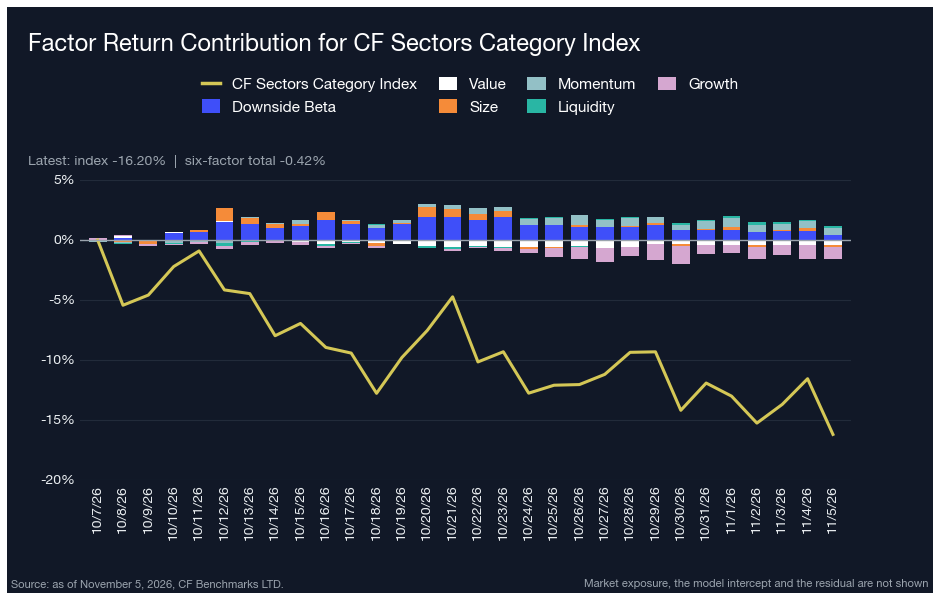
What Factors are Driving Markets
Across the CF DACS Sectors universe, factor contributions total -0.42% over the trailing 30 days against an index return of -16.20%, so the factors sit 15.8 pp above the index, compared with 16.7 pp above it last week as published. That is 0.9 pp narrower, but two larger moves offset each other. The window roll narrowed the gap by 7.1 pp, as the first week of October left the window and took 5.0 pp of loss off the index and 2.1 pp of gain off the six-factor total. This week widened it by 6.2 pp, with the index down 6.9 pp and the six factors down 0.7 pp. Momentum (0.58%) is now the largest contributor, followed by Downside Beta (0.38%) and Liquidity (0.23%), with Size (-0.13%) and Value (-0.45%) small drags and Growth (-1.03%) the largest, as it was last week at -1.22%. Size was the second-largest contributor last week at 1.04%, and the roll alone brought it to 0.13%. The index fell 8.10% on the week, and one token accounts for nearly half of it. Dogecoin (DOGE), at 44.60% of the weight at the start of the week, fell 8.49% for about 3.8 pp of the decline, while ENA (-21.45%) trailed the index by 13.4 pp, and AAVE (-2.01%) and UNI (-4.41%) finished 6.1 pp and 3.7 pp ahead. The six factors shown leave out Market exposure, which the model also includes along with an intercept and a token-specific residual. The Sectors model carries a Market beta of 1.34 with an R2 of 0.81. On a 30-day log basis that also counts the October 7 session, the index's -24.81% splits into about -19.3% from Market exposure, -3.2% from the intercept, -1.9% from the residual and -0.4% from the six factors. Sectors lost with the Market, and the six style factors neither cushioned the loss nor added to it. Growth has been the largest drag for two weeks running and is the contribution to track.
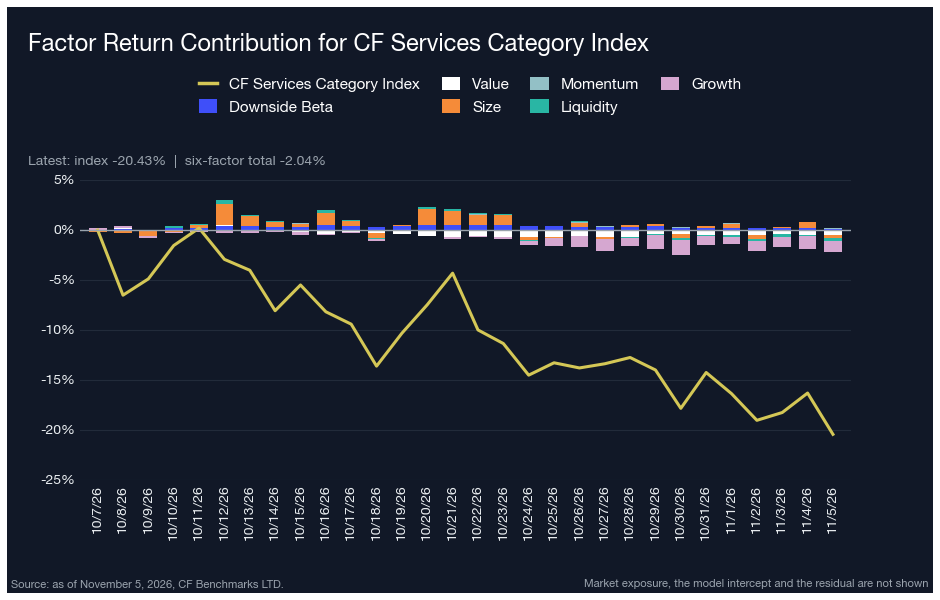
In the CF DACS Services universe, factor contributions total -2.04% against an index return of -20.43%, so the factors sit 18.4 pp above the index, compared with 20.5 pp above it last week as published. The roll narrowed the gap by 7.7 pp, taking 5.5 pp of loss off the index and 2.2 pp of gain off the six-factor total, and this week widened it by 5.6 pp, with the index down 6.4 pp and the six factors down 0.8 pp. No factor is a meaningful contributor now. Downside Beta (0.11%) and Momentum (0.04%) are marginally positive, Size (-0.26%), Liquidity (-0.28%) and Value (-0.53%) are small drags, and Growth (-1.12%) is the largest. Size was the largest contributor last week at 2.04%, and the roll alone brought it to 0.25%. The index lost 7.91% on the week, and two tokens account for more than half of it. LINK, at 42.76% of the weight at the start of the week, fell 7.43% for about 3.2 pp, and TAO, at 13.08%, fell 12.74% for about 1.7 pp. WLD fell 17.88% after losing 25.28% last week and trailed the index by 10.0 pp, while POL (+2.17%) and QNT (-0.65%) finished 10.1 pp and 7.3 pp ahead. The Services model carries a Market beta of 1.33 with an R2 of 0.81. Of the index's -28.86% log return over the window, Market exposure accounts for about -19.2%, the residual -5.5%, the intercept -2.2% and the six factors -2.0%. The residual is less than half of last week's -11.8%. With LINK near 43% of the index, one token's move drove Services more than any factor did.
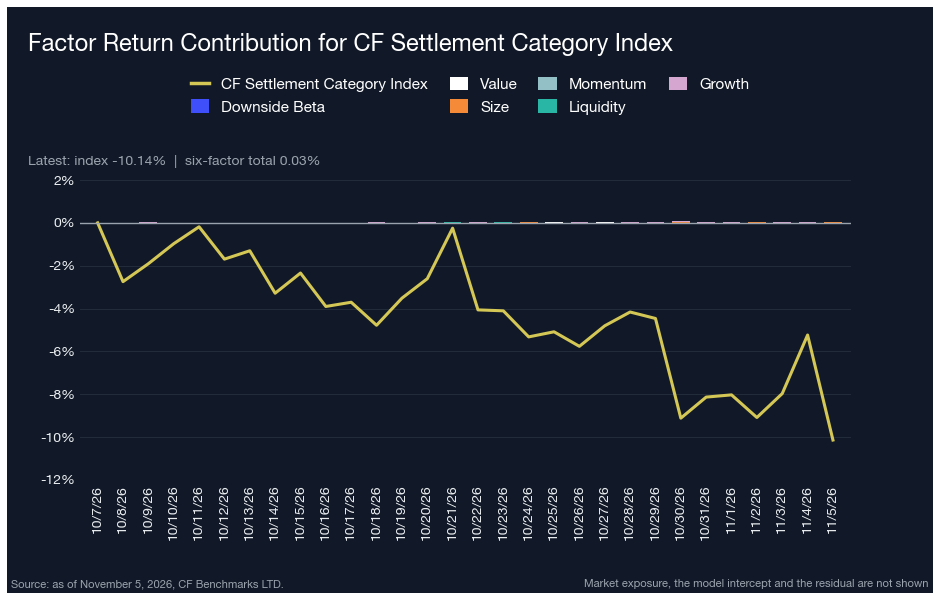
The Settlement universe, dominated by Bitcoin at about 75% of the index, again shows the weakest link to the style factors, which is expected because Market exposure sits outside the set. Factor contributions total 0.03% against an index return of -10.14%, so the factors sit 10.2 pp above the index, compared with 5.7 pp above it last week as published, and no single factor contributes more than 0.03% in either direction. The roll added 1.3 pp to the index and this week's move took off 5.7 pp. The model's Market beta for Settlement is 0.99 with an R2 of 1.00, and Market exposure accounts for about -14.3% of the index's -14.11% log return, so the index tracked the Market essentially one for one. The index lost 6.13% on the week. BTC fell 5.86% for about 4.4 pp of the decline and ETH fell 3.59% for about 0.4 pp, and all 17 constituents fell. HYPE (-17.06%) and NEAR Protocol (NEAR, -15.91%) trailed the index by 10.9 pp and 9.8 pp, at roughly 3% and 0.3% of the weight, while ALGO and Internet Computer (ICP) held up best at about -3.0%, 3.1 pp ahead on weights of 0.04% each. Style contributions in Settlement read near zero while BTC holds three quarters of the weight.
Appendix: CF Factor Methodology
Market Factor
The market factor captures the broad, systematic risk that permeates the digital asset ecosystem. It reflects aggregate influences such as macroeconomic conditions, investor sentiment, and overall market volatility. As such, this factor is defined by the daily returns of the CF Broad Cap (Free Float Market Cap Weight) Index, offering a comprehensive and capitalization-weighted representation of the asset class.
Size Factor
The size factor captures the return differential associated with asset scale, reflecting the hypothesis that smaller-cap digital assets tend to outperform their larger-cap counterparts. This effect is understood to compensate for elevated operational and financial risks while exploiting potential market inefficiencies. In this framework, the size factor is defined by each asset’s fully diluted market capitalization. The value is sign-inverted so that higher z-scores are assigned to smaller assets and vice-versa.
Value Factor
The value factor reflects a protocol’s ability to generate economic output relative to its capital base and market valuation, combining measures of both efficiency and user engagement. It is constructed as the average z-score of two key ratios: transaction fees relative to total value locked (Fees/TVL) and daily active users relative to market capitalization (DAU/MCap). This composite metric captures how productively a protocol utilizes its resources while also serving as a proxy for user-driven demand. A higher combined score indicates efficient resource utilization and strong user engagement.
Momentum Factor
The momentum factor captures short-term price persistence by identifying assets that have recently exhibited strong performance. It is computed as the average z-score of two metrics: the 2 weeks cumulative performance and the 2 weeks risk-adjusted cumulative performance. This approach aligns with established findings in traditional financial literature and demonstrates empirical relevance in digital assets, where price trends tend to exhibit momentum over short horizons.
Growth Factor
The growth factor captures the expansion of a protocol’s network activity and user adoption. In the context of digital assets, it reflects metrics such as fee generation and user engagement, which serve as indicators of increased platform utilization and operational scale. The factor is defined as the average z-score of 30-day fee growth and 30-day weekly active user growth, thereby identifying assets exhibiting consistent and measurable increases in underlying network usage.
Downside Beta
The downside beta factor captures an asset’s sensitivity to adverse market conditions by isolating its behavior during periods of negative market returns. Empirical evidence shows that assets with lower downside beta tend to outperform their higher-beta counterparts over the long-term, due to their reduced participation in market drawdowns and more stable return profiles during periods of elevated volatility. As such, it is estimated through a regression of the asset’s daily returns over the most recent four-week period against market returns observed exclusively during negative sessions. The resulting value is sign-inverted to ensure that assets with lower downside exposure are assigned higher z-scores.
Liquidity Factor
The liquidity factor captures the ease with which a digital asset can be traded without significantly impacting its price. Empirical evidence shows that illiquid assets tend to command a higher risk premium than their more liquid counterparts, serving as compensation for trading friction and price volatility. To quantify this, the factor is measured using token turnover, defined as trading volume as a percentage of circulating supply. The value is sign-inverted such that higher z-scores are assigned to less liquid assets.
For further detail, view the CF Factors Methodology Document, the CF Factor Data Suite, and Our paper “A Factor Model for Digital Assets” in Springer Nature’s Mathematical Research for Blockchain Economy.
The information contained within is for educational and informational purposes ONLY. It is not intended nor should it be considered an invitation or inducement to buy or sell any of the underlying instruments cited including but not limited to cryptoassets, financial instruments or any instruments that reference any index provided by CF Benchmarks Ltd. This communication is not intended to persuade or incite you to buy or sell security or securities noted within. Any commentary provided is the opinion of the author and should not be considered a personalised recommendation. Please contact your financial adviser or professional before making an investment decision.
Note: Some of the underlying instruments cited within this material may be restricted to certain customer categories in certain jurisdictions.
Factor Friday - November 6, 2026
Downside Beta led CF Benchmarks' factor table at 1.66% as the Market fell 6.17%, its largest weekly loss since June. Liquidity gained 1.51% for a second week and leads over four weeks at 4.46%, while Size, down 0.50% on the week, still leads year to date at 22.14%.
Mark Pilipczuk
Altcoins Lead October's Decline
The CME CF Crypto Market Index fell 9.32% in October, the smallest decline in the family, as Bitcoin supplied 57% of it while falling less than the index. Altcoins led the selling before the Binance theft and Bitcoin after it, so the CF Services Category Index fell furthest (-19.71%).
Mark Pilipczuk
Crypto Slides On Hike Fears And Binance Theft
Digital assets fell in October as the Fed held rates with two dissents in favor of a hike and the $6.3 billion Binance theft pushed Broad Cap below its 100-day average. All eight CF indices declined, DeFi fell 23.5%, and funds recorded their first outflow since June.
Mark Pilipczuk
By clicking Accept, you consent to CF Benchmarks's use of cookies.
Visit Cookie Settings to learn how CF Benchmarks uses cookies and to adjust your preferences.