
Sep 25, 2026
Factor Friday - September 25, 2026
The Market Rallies as Less Liquid Tokens Trail
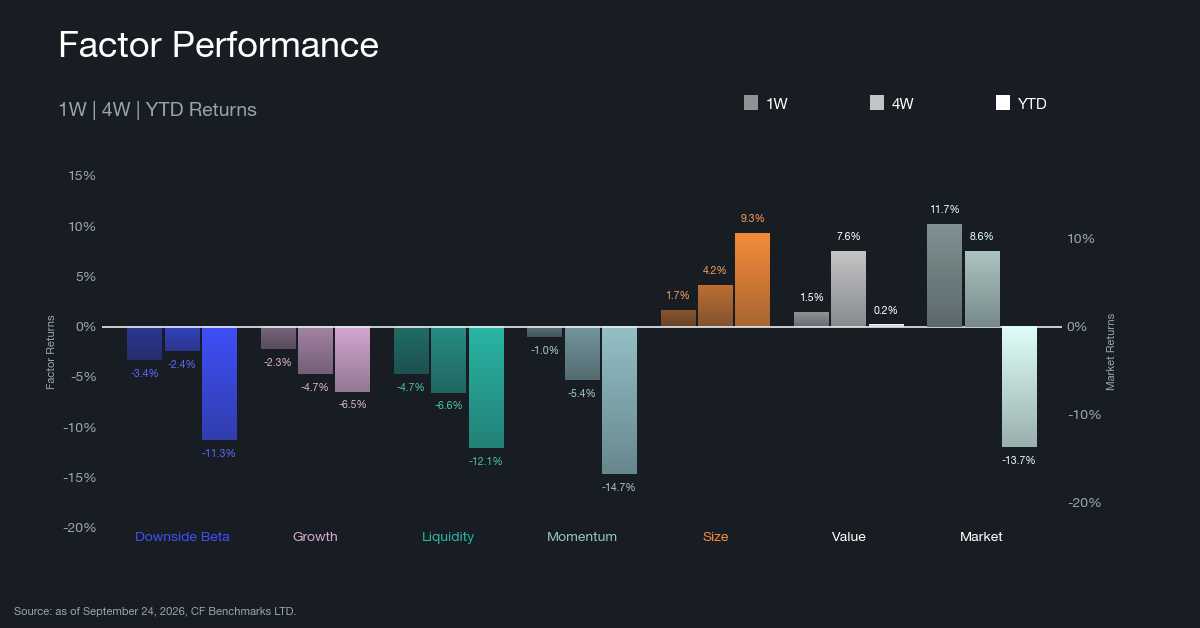
The Market rose 11.70%, recovering the declines of the prior two weeks (-4.98% and -0.70%) and moving from fifth to first on the weekly table. Size (1.67%) and Value (1.47%) were the only other factors to finish positive, while Momentum (-1.02%), Growth (-2.25%), Downside Beta (-3.37%) and Liquidity (-4.71%) all lagged, with Liquidity last. Over four weeks the Market leads at 8.57%, ahead of Value (7.55%) and Size (4.17%), and Liquidity (-6.58%) trails. Year to date, Size remains the strongest factor at 9.33% and Value turned positive at 0.20%, up from -1.26% a week earlier. The Market's year-to-date loss narrowed to -13.67% from -22.71%, which leaves Momentum (-14.66%) as the weakest factor of the year. Both sign-inverted risk factors fell, meaning tokens with high downside beta and more liquid tokens outperformed, while the positive Size print shows the bid reached smaller caps. For investors, the week rewarded directional exposure held in heavily traded tokens, and books positioned defensively or in thinly traded names lagged it.
Rolling Factor Rankings and Rotation
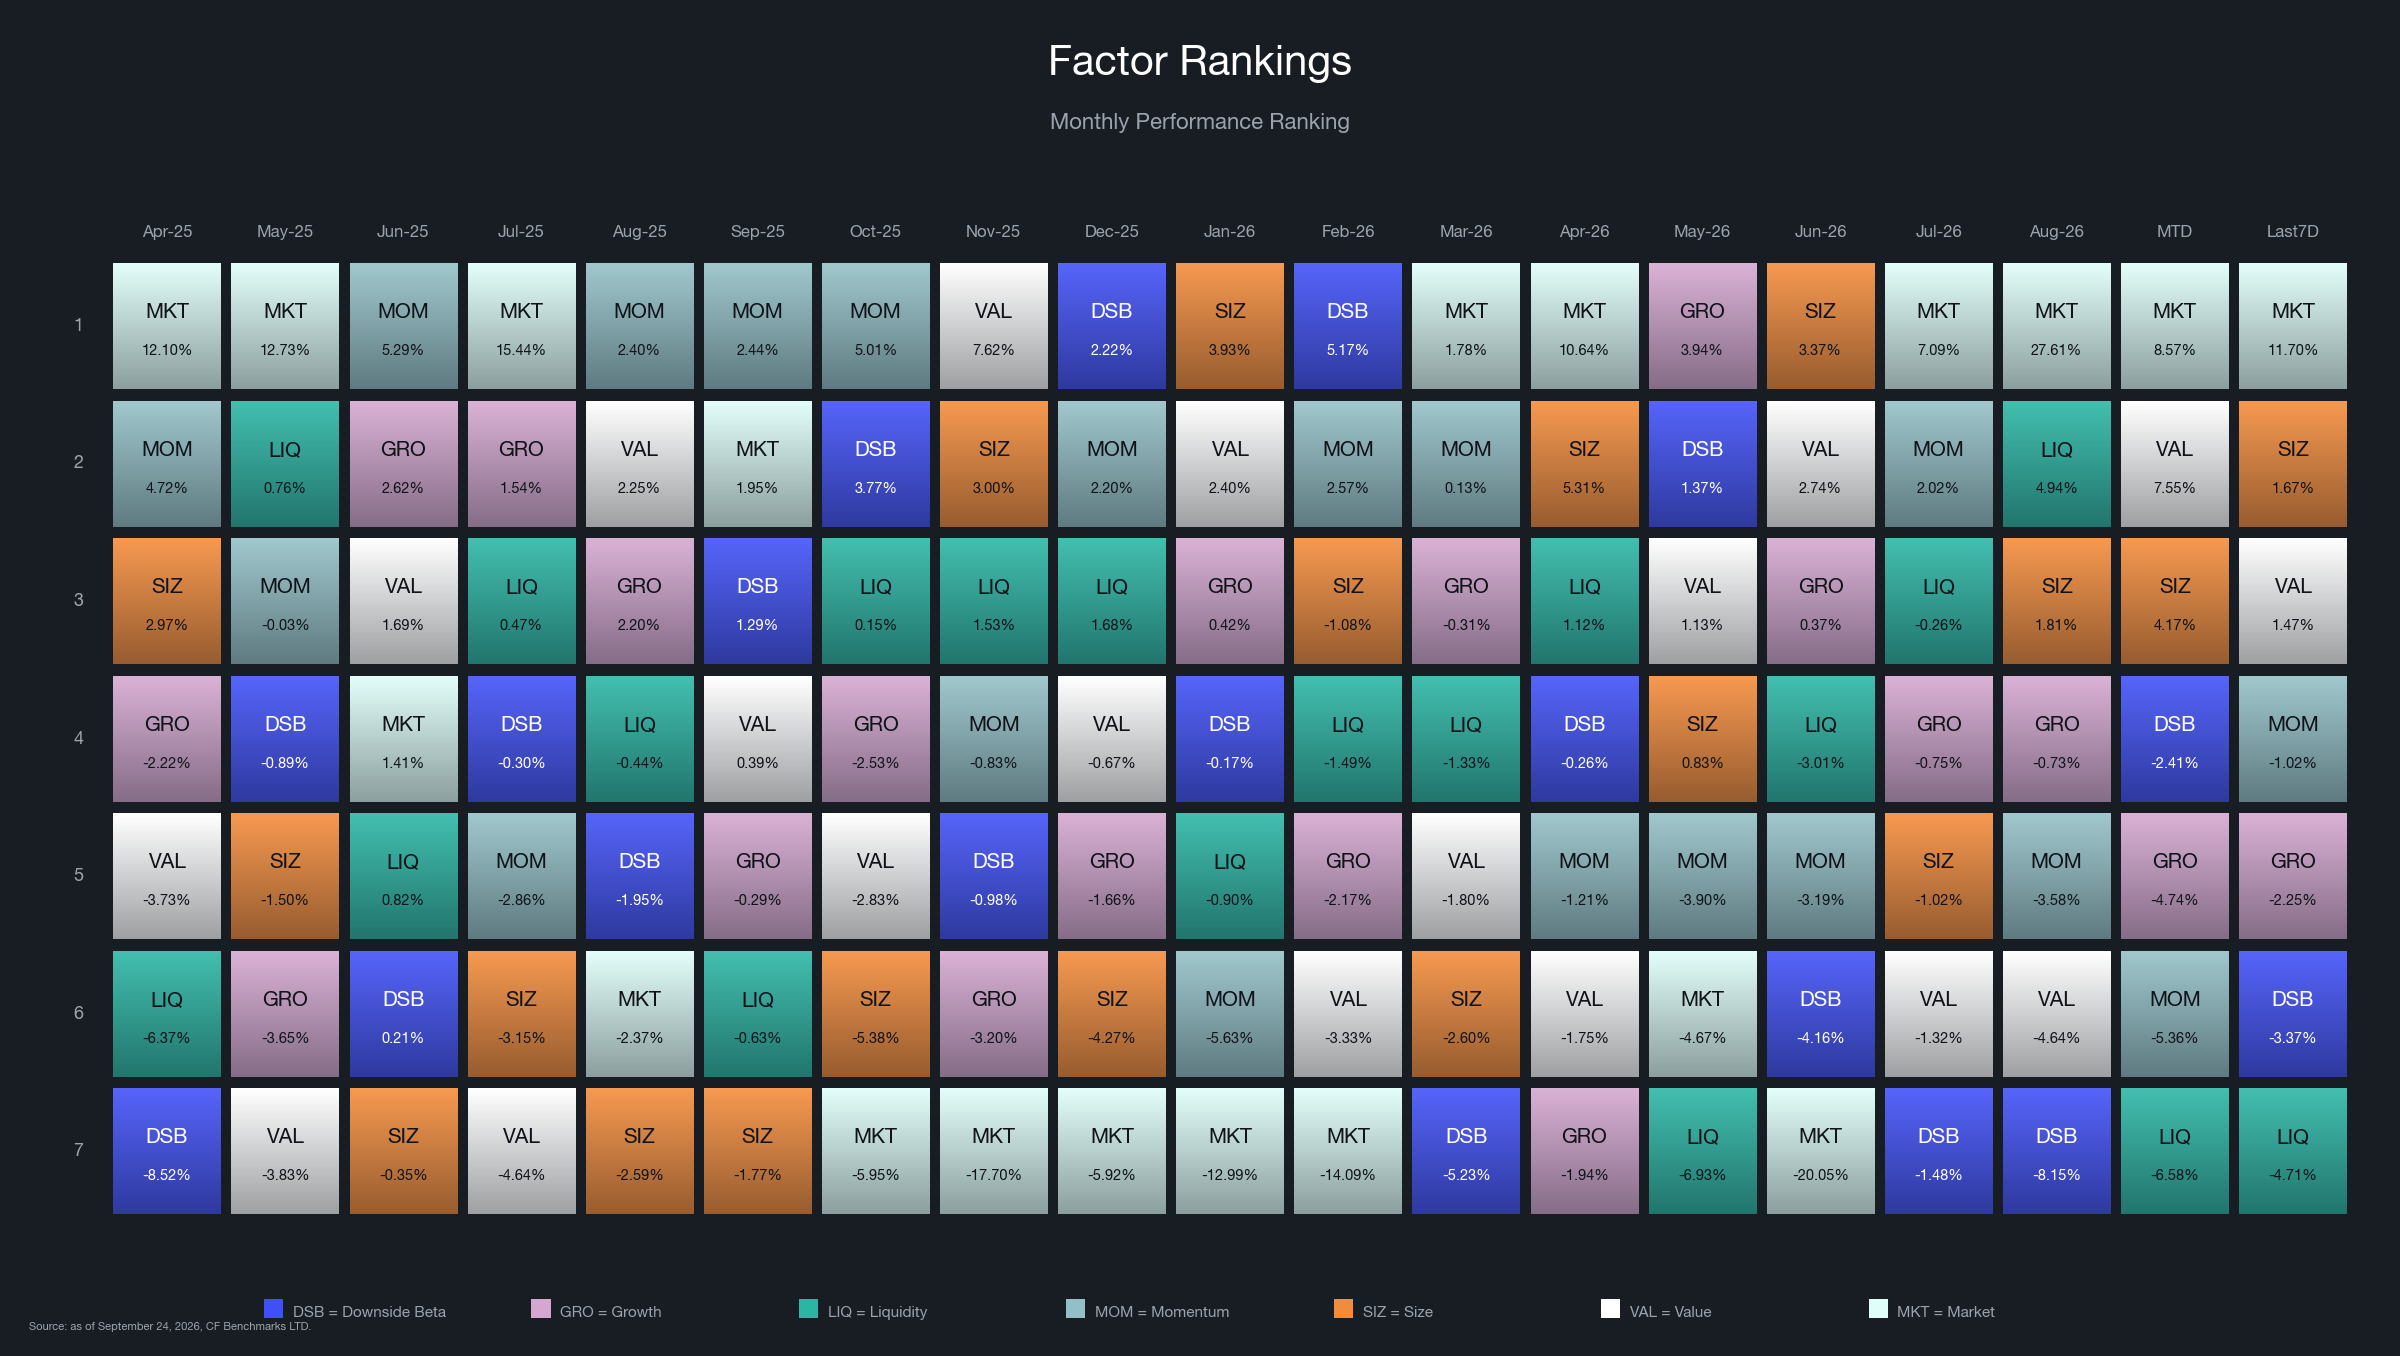
Value's three-week run at the top of the weekly table ended as broad beta took over. The Market climbed from fifth to first and Size moved from fourth to second, while Value slipped to third at 1.47% after 1.85% a week earlier. Momentum rose from last to fourth as its loss narrowed from -1.32% to -1.02%. Growth moved the other way, dropping from second to fifth, and Liquidity fell from third to last as its loss deepened from -0.25% to -4.71%. Downside Beta held sixth. Last week the month-to-date (MTD) ranking had barely moved; this week it reordered. The Market jumped from sixth to first MTD at 8.57%, ahead of Value (7.55%) and Size (4.17%), pushing Downside Beta out of the top three to fourth at -2.41%, and Liquidity (-6.58%) replaced Momentum at the bottom. With the monthly table now moving alongside the weekly one, the shift toward beta looks like a trend. Value and Size hold second and third on both measures, so fundamentals and smaller caps are still participating. Leadership that rests on the Market alone would be a narrower, and more fragile, rally than the one in place now.
Market and Key Factor Betas
Market Beta
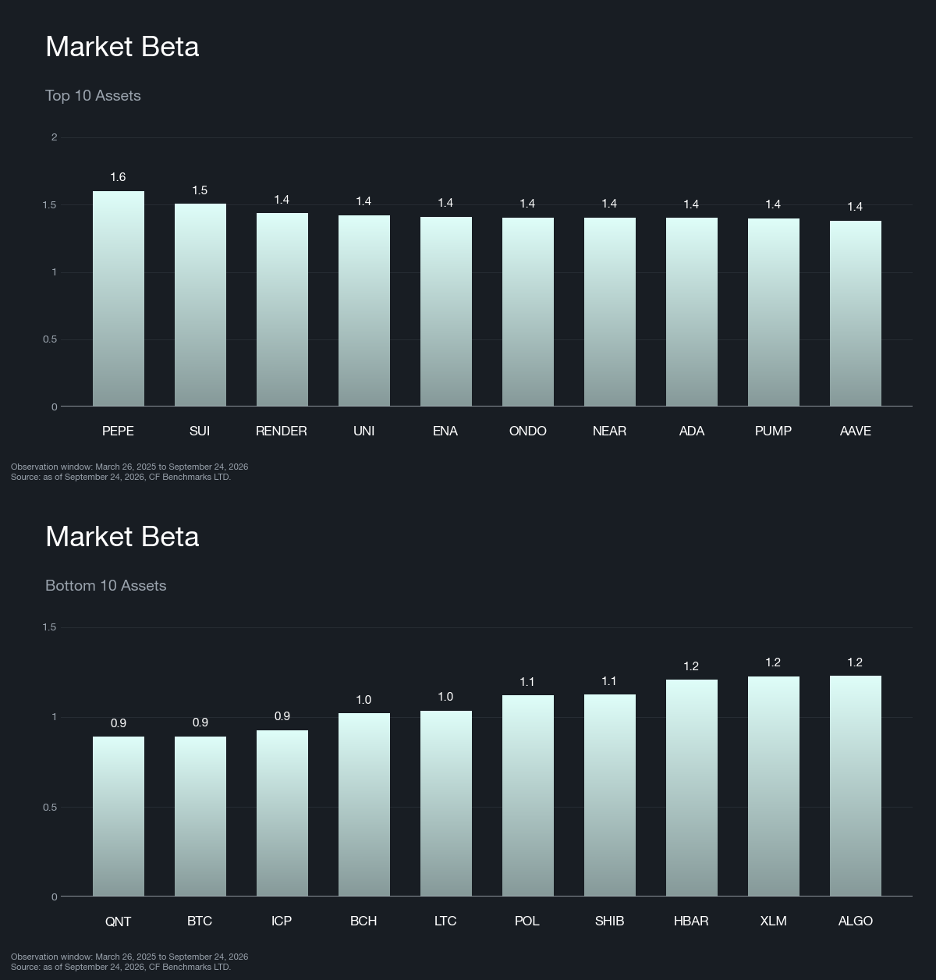
From this week we rank only the index's current constituents. The regression window is expanding, so tokens that had left the CF Broad Cap basket, including several that anchored these lists in recent weeks, kept betas frozen at their last observation. Removing them explains most of the change from last week's charts. On a like-for-like basis the list barely moved. The high market-beta cohort mixes meme-linked tokens, DeFi protocols and alternative layer-1 platforms with AI compute and real-world-asset names, and the DeFi group widened as Aave (AAVE) entered and Zero (ZRO) left. The low end is unchanged, with Quant (QNT) and Bitcoin (BTC) at the floor near 0.89 and older payment and enterprise chains filling the rest. The high-beta cohort paid off. Its ten names returned an average 29.16% on the week against 23.22% for the low-beta ten, and both groups ran far ahead of Bitcoin's 10.43%. That spread is the cost of Bitcoin's weight in a cap-weighted benchmark during a week like this one, and the same exposure would work in reverse on a sharp drawdown.
Liquidity
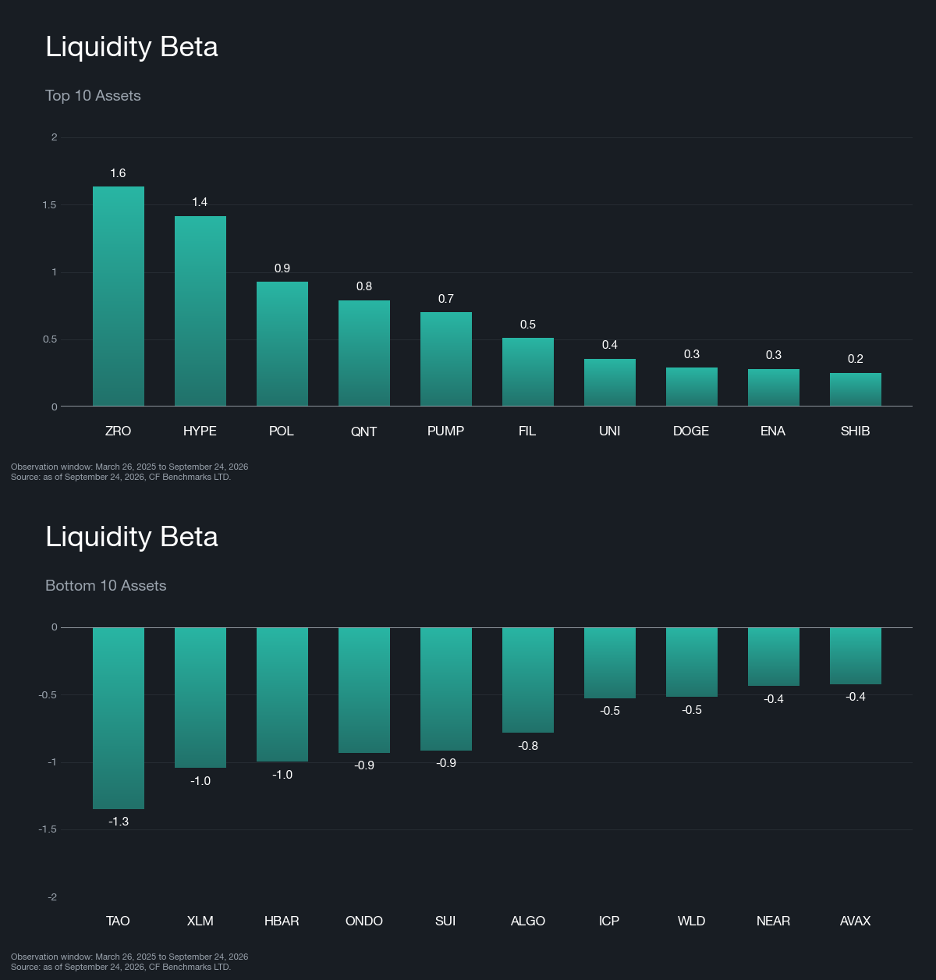
Liquidity's -4.71% was the weakest print of the week and leaves the factor last over four weeks at -6.58%. The factor is sign-inverted, so a negative print means tokens that trade heavily relative to their supply outperformed. ZRO now leads the high liquidity-beta cohort, the names that move with less liquid tokens, after its beta rose from 0.68 to 1.63 and lifted it from fourth to first. Hyperliquid (HYPE) sits second, DeFi and payment tokens fill most of the rest, and Uniswap (UNI) entered as Pepe (PEPE) left. The opposite end is weighted toward layer-1 and AI tokens and is led by Bittensor (TAO), and Avalanche (AVAX) entered it as Render (RENDER) dropped out. The factor scores moved in the same direction. AVAX and Sui (SUI) both saw their liquidity scores fall by more than 2.4 points as turnover rose, while Filecoin (FIL) moved 5.54 points the other way, from -5.45 to 0.10, as its turnover fell back toward the middle of the universe. The ten highest liquidity-beta names returned an average 22.20% against 29.63% for the ten lowest. Taken with a positive Size print, this says the market reached down the market cap curve only where it could trade easily. If Liquidity turns positive while the Market holds its gains, the bid would be broadening into thinner names.
Downside Beta
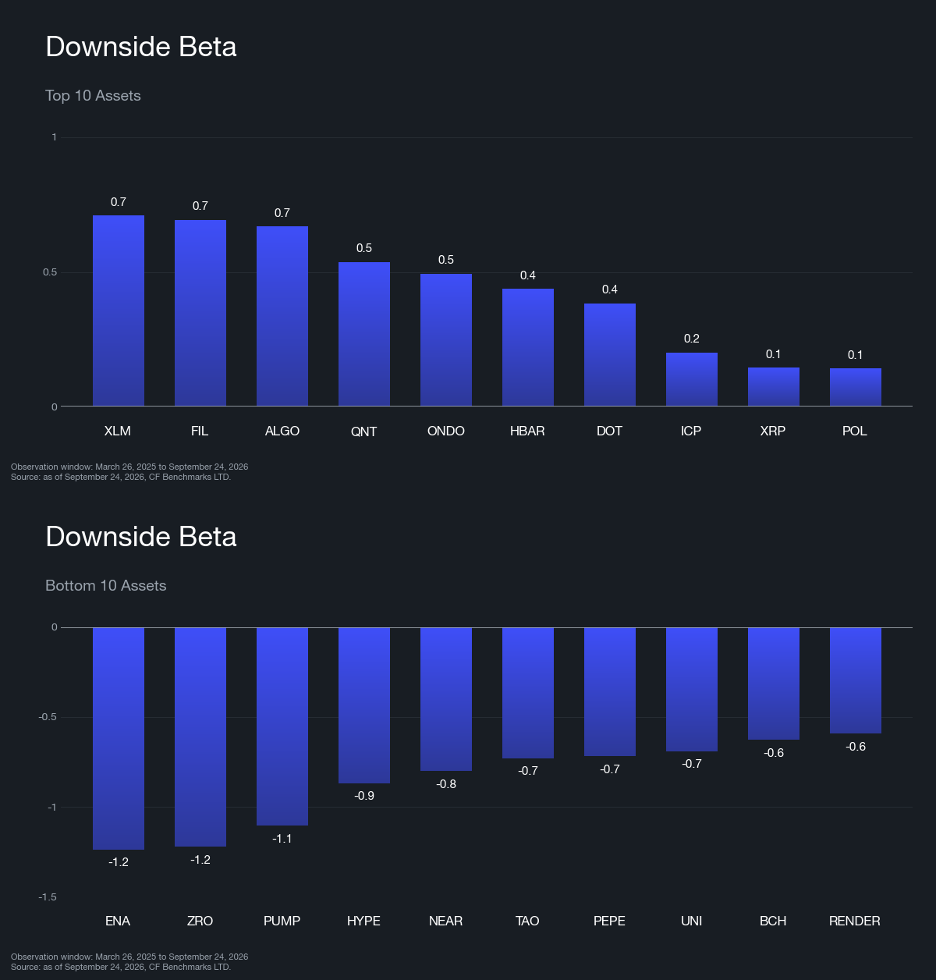
Downside Beta fell for a third straight week, to -3.37% from -0.80%, after leading the table at 3.20% three weeks ago. With the sign inverted, a negative reading means the tokens most exposed to the Market's down days outperformed, which is the usual pattern in an 11.70% rally. Last week's report said continued decay would confirm the reversal of the defensive bid, and this week's reading does that. The defensive end of the list is made up of legacy layer-1 and enterprise payment chains led by Stellar (XLM) and FIL, with Polygon (POL) entering as Bitcoin moved out. The drawdown-sensitive end is concentrated in DeFi and trading-venue tokens alongside meme and AI-linked names. ZRO entered it at -1.22 from -0.20, and Bitcoin Cash (BCH) joined as Dogecoin (DOGE) and SUI left. FIL's downside-beta score moved from the long side of the factor portfolio to the short side, from 0.30 to -0.97, even as it ranks second on the beta list. The score uses the last four weeks of down days while the beta uses the full window since March 2025, so the split says its recent trading has turned more fragile than its history. The ten most drawdown-sensitive names returned an average 30.64% this week against 21.70% for the ten most defensive, an 8.94 pp gap. That gap is what the market paid for drawdown exposure this week, and a rough measure of what a Market reversal could take back from the same names.
What Factors are Driving Markets
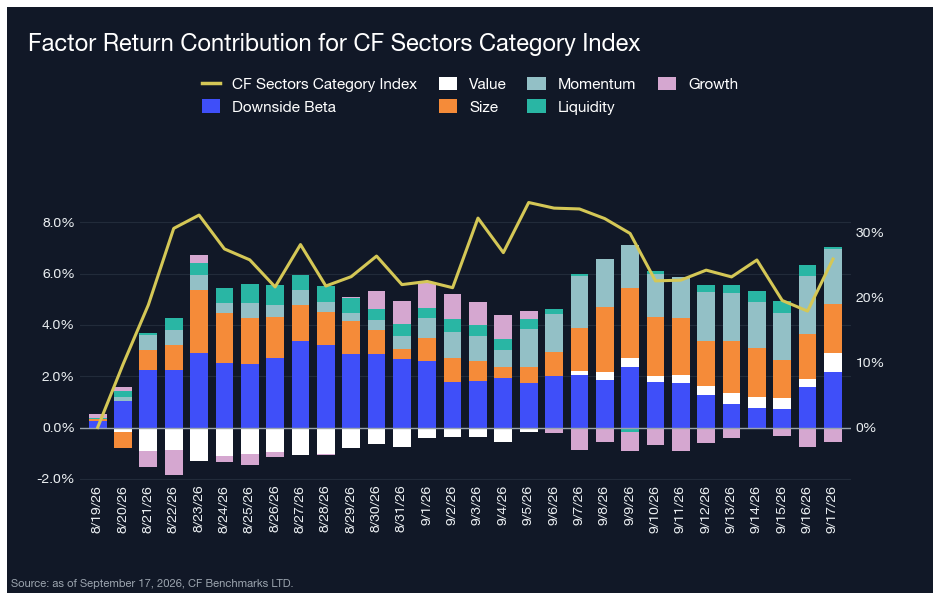
Factor contributions across the CF DACS Sectors universe total 3.02% over the trailing 30 days against an index return of 23.31%, leaving the index 20.29 percentage points (pp) ahead, slightly wider than last week's 19.45 pp. The factor sleeve fell by more than half from 6.45% as Liquidity (-1.63%) became the largest drag alongside Growth (-1.47%), offsetting Value (1.86%), Momentum (1.66%), Size (1.40%) and Downside Beta (1.20%). The 30-day index return eased from 25.89% even though the index rose 19.99% on the week, because a strong late-August stretch rolled out of the window. Ethena (ENA) led the week at 43.28%, 23.29 pp ahead of the index, while Pump (PUMP) finished flat at -0.03%, 20.02 pp behind it. The factor sleeve now explains 13% of the 30-day return, down from 25% a week ago, and a 43 pp spread between the best and worst constituent puts most of the rest down to token-specific moves.
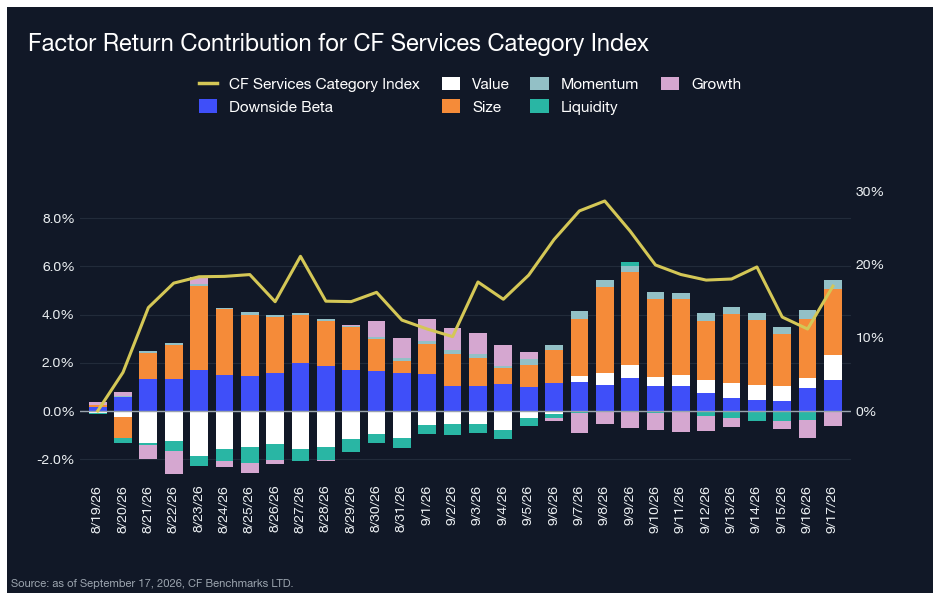
In the CF DACS Services universe, factor contributions total 4.97% against an index return of 22.70%, a 17.72 pp gap that widened from 12.29 pp a week earlier. The factor sleeve barely moved from 4.80%, so the wider gap comes entirely from the index, whose 30-day return rose from 17.10%. Value is now the leading contributor at 2.84%, overtaking Size (1.93%), and Growth (-1.29%) remains the largest drag. QNT led the week at 39.95%, 18.71 pp ahead of the index's 21.24% weekly gain, with ZRO close behind, while POL lagged at 9.45%, 11.79 pp behind. Last week's narrowing proved temporary. Services is again an index-led category, with factor contributions accounting for about a fifth of its 30-day return.
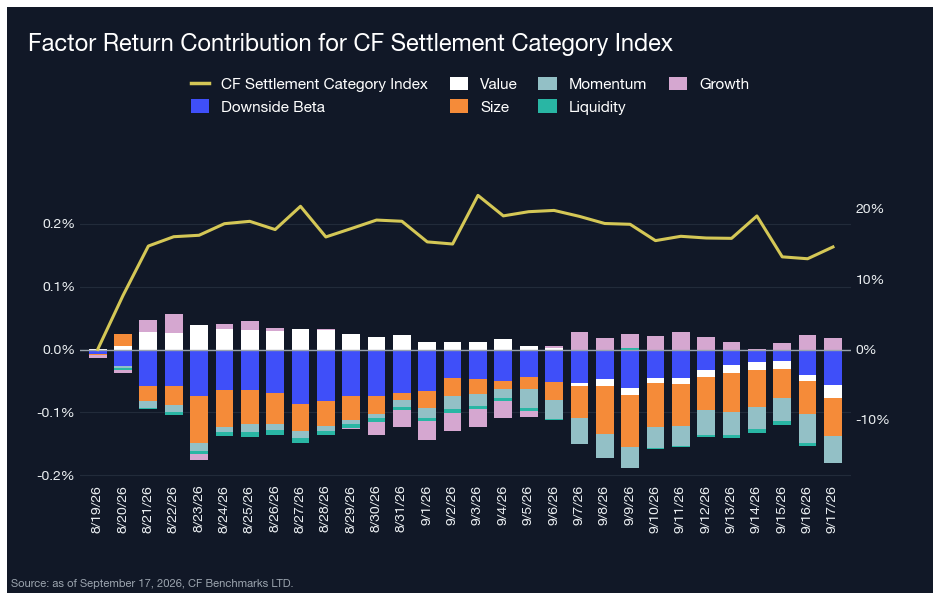
The Settlement universe, dominated by Bitcoin, remains the one where the factor set explains least. Factor contributions total -0.09% over the trailing 30 days against an index return of 9.17%, a 9.26 pp gap that narrowed from 14.73 pp because late-August gains rolled out of the window, while the factor sleeve stayed flat. No factor contributed more than 0.06 pp in either direction, as in each of the prior two weeks. Every constituent rose on the week, and the largest gains came from the smallest weights: Near (NEAR) returned 56.67%, 45.18 pp above the index's 11.49%, with BCH and SUI also above 38%, while Toncoin (TON) trailed at 6.38%. Bitcoin, at 73.04% of the index, returned 10.43%. Settlement's return is, in effect, a Bitcoin position, and style factors have little to add to it or take away from it.
Appendix: CF Factor Methodology
Market Factor
The market factor captures the broad, systematic risk that permeates the digital asset ecosystem. It reflects aggregate influences such as macroeconomic conditions, investor sentiment, and overall market volatility. As such, this factor is defined by the daily returns of the CF Broad Cap (Free Float Market Cap Weight) Index, offering a comprehensive and capitalization-weighted representation of the asset class.
Size Factor
The size factor captures the return differential associated with asset scale, reflecting the hypothesis that smaller-cap digital assets tend to outperform their larger-cap counterparts. This effect is understood to compensate for elevated operational and financial risks while exploiting potential market inefficiencies. In this framework, the size factor is defined by each asset’s fully diluted market capitalization. The value is sign-inverted so that higher z-scores are assigned to smaller assets and vice-versa.
Value Factor
The value factor reflects a protocol’s ability to generate economic output relative to its capital base and market valuation, combining measures of both efficiency and user engagement. It is constructed as the average z-score of two key ratios: transaction fees relative to total value locked (Fees/TVL) and daily active users relative to market capitalization (DAU/MCap). This composite metric captures how productively a protocol utilizes its resources while also serving as a proxy for user-driven demand. A higher combined score indicates efficient resource utilization and strong user engagement.
Momentum Factor
The momentum factor captures short-term price persistence by identifying assets that have recently exhibited strong performance. It is computed as the average z-score of two metrics: the 2 weeks cumulative performance and the 2 weeks risk-adjusted cumulative performance. This approach aligns with established findings in traditional financial literature and demonstrates empirical relevance in digital assets, where price trends tend to exhibit momentum over short horizons.
Growth Factor
The growth factor captures the expansion of a protocol’s network activity and user adoption. In the context of digital assets, it reflects metrics such as fee generation and user engagement, which serve as indicators of increased platform utilization and operational scale. The factor is defined as the average z-score of 30-day fee growth and 30-day weekly active user growth, thereby identifying assets exhibiting consistent and measurable increases in underlying network usage.
Downside Beta
The downside beta factor captures an asset’s sensitivity to adverse market conditions by isolating its behavior during periods of negative market returns. Empirical evidence shows that assets with lower downside beta tend to outperform their higher-beta counterparts over the long-term, due to their reduced participation in market drawdowns and more stable return profiles during periods of elevated volatility. As such, it is estimated through a regression of the asset’s daily returns over the most recent four-week period against market returns observed exclusively during negative sessions. The resulting value is sign-inverted to ensure that assets with lower downside exposure are assigned higher z-scores.
Liquidity Factor
The liquidity factor captures the ease with which a digital asset can be traded without significantly impacting its price. Empirical evidence shows that illiquid assets tend to command a higher risk premium than their more liquid counterparts, serving as compensation for trading friction and price volatility. To quantify this, the factor is measured using token turnover, defined as trading volume as a percentage of circulating supply. The value is sign-inverted such that higher z-scores are assigned to less liquid assets.
For further detail, view the CF Factors Methodology Document, the CF Factor Data Suite, and Our paper “A Factor Model for Digital Assets” in Springer Nature’s Mathematical Research for Blockchain Economy.
The information contained within is for educational and informational purposes ONLY. It is not intended nor should it be considered an invitation or inducement to buy or sell any of the underlying instruments cited including but not limited to cryptoassets, financial instruments or any instruments that reference any index provided by CF Benchmarks Ltd. This communication is not intended to persuade or incite you to buy or sell security or securities noted within. Any commentary provided is the opinion of the author and should not be considered a personalised recommendation. Please contact your financial adviser or professional before making an investment decision.
Note: Some of the underlying instruments cited within this material may be restricted to certain customer categories in certain jurisdictions.
Factor Friday - September 25, 2026
The Market rose 11.70% to lead CF Benchmarks' factor table, ending Value's three-week run at the top. Liquidity finished last and Downside Beta fell for a third week, so the rally favored heavily traded, drawdown-sensitive tokens, while Size showed the bid still reached smaller caps.
Mark Pilipczuk
Changes to the Token Market Price Benchmarks Series - Market Prices – 22 September 2026
The Administrator has confirmed changes to the Token Market Price Family for the period 15 September 2026 to 22 September 2026.
CF Benchmarks
Digital Assets Move Higher After the Rate Hike
An expected Fed hike gave way to a broad crypto rebound led by Infrastructure, DeFi and Programmable assets, while lower volatility and firmer Bitcoin funding pointed to normalization rather than uniform stress.
Mark Pilipczuk
By clicking Accept, you consent to CF Benchmarks's use of cookies.
Visit Cookie Settings to learn how CF Benchmarks uses cookies and to adjust your preferences.