
Sep 21, 2026
Digital Assets Move Higher After the Rate Hike
Weekly Index Highlights, September 21, 2026
All eyes were on the Fed this week, while regulatory guidance came from the SEC and CFTC after a failed Clarity Act vote. The Digital Asset Market Clarity Act failed to advance in the Senate on September 15th on a 49-50 vote, short of the 60 votes required. The Federal Reserve unanimously raised its target range 25 basis points (bps) to 3.75% to 4.00% on September 16th after the move was largely priced in by the futures market. Bitcoin (BTC) was roughly flat around the announcement before briefly reaching $76,000. On September 17th, the Securities and Exchange Commission (SEC) announced a five-year conditional innovation exemption for qualifying tokenized-securities venues, permitting eligible tokenized US stocks to trade through smart contracts and liquidity pools subject to the announced conditions. Contemporary coverage linked Uniswap (UNI) directly to the SEC announcement. UNI gained 35.41% for the week and extended its 2026 gain to +46.99%. Arbitrum (ARB) rose 50.71% and tokenization-focused Ondo (ONDO) 16.21%, moving both into positive year-to-date (YTD) territory at +7.65% and +10.13%, respectively. All eight CF Capitalization Series indices subsequently rose. Infrastructure and Programmable led the DACS sub-category averages, while US spot Bitcoin exchange-traded fund (ETF) flows finished near flat at +$6.2 million and spot Ether funds lost $140 million.
Market Performance Update
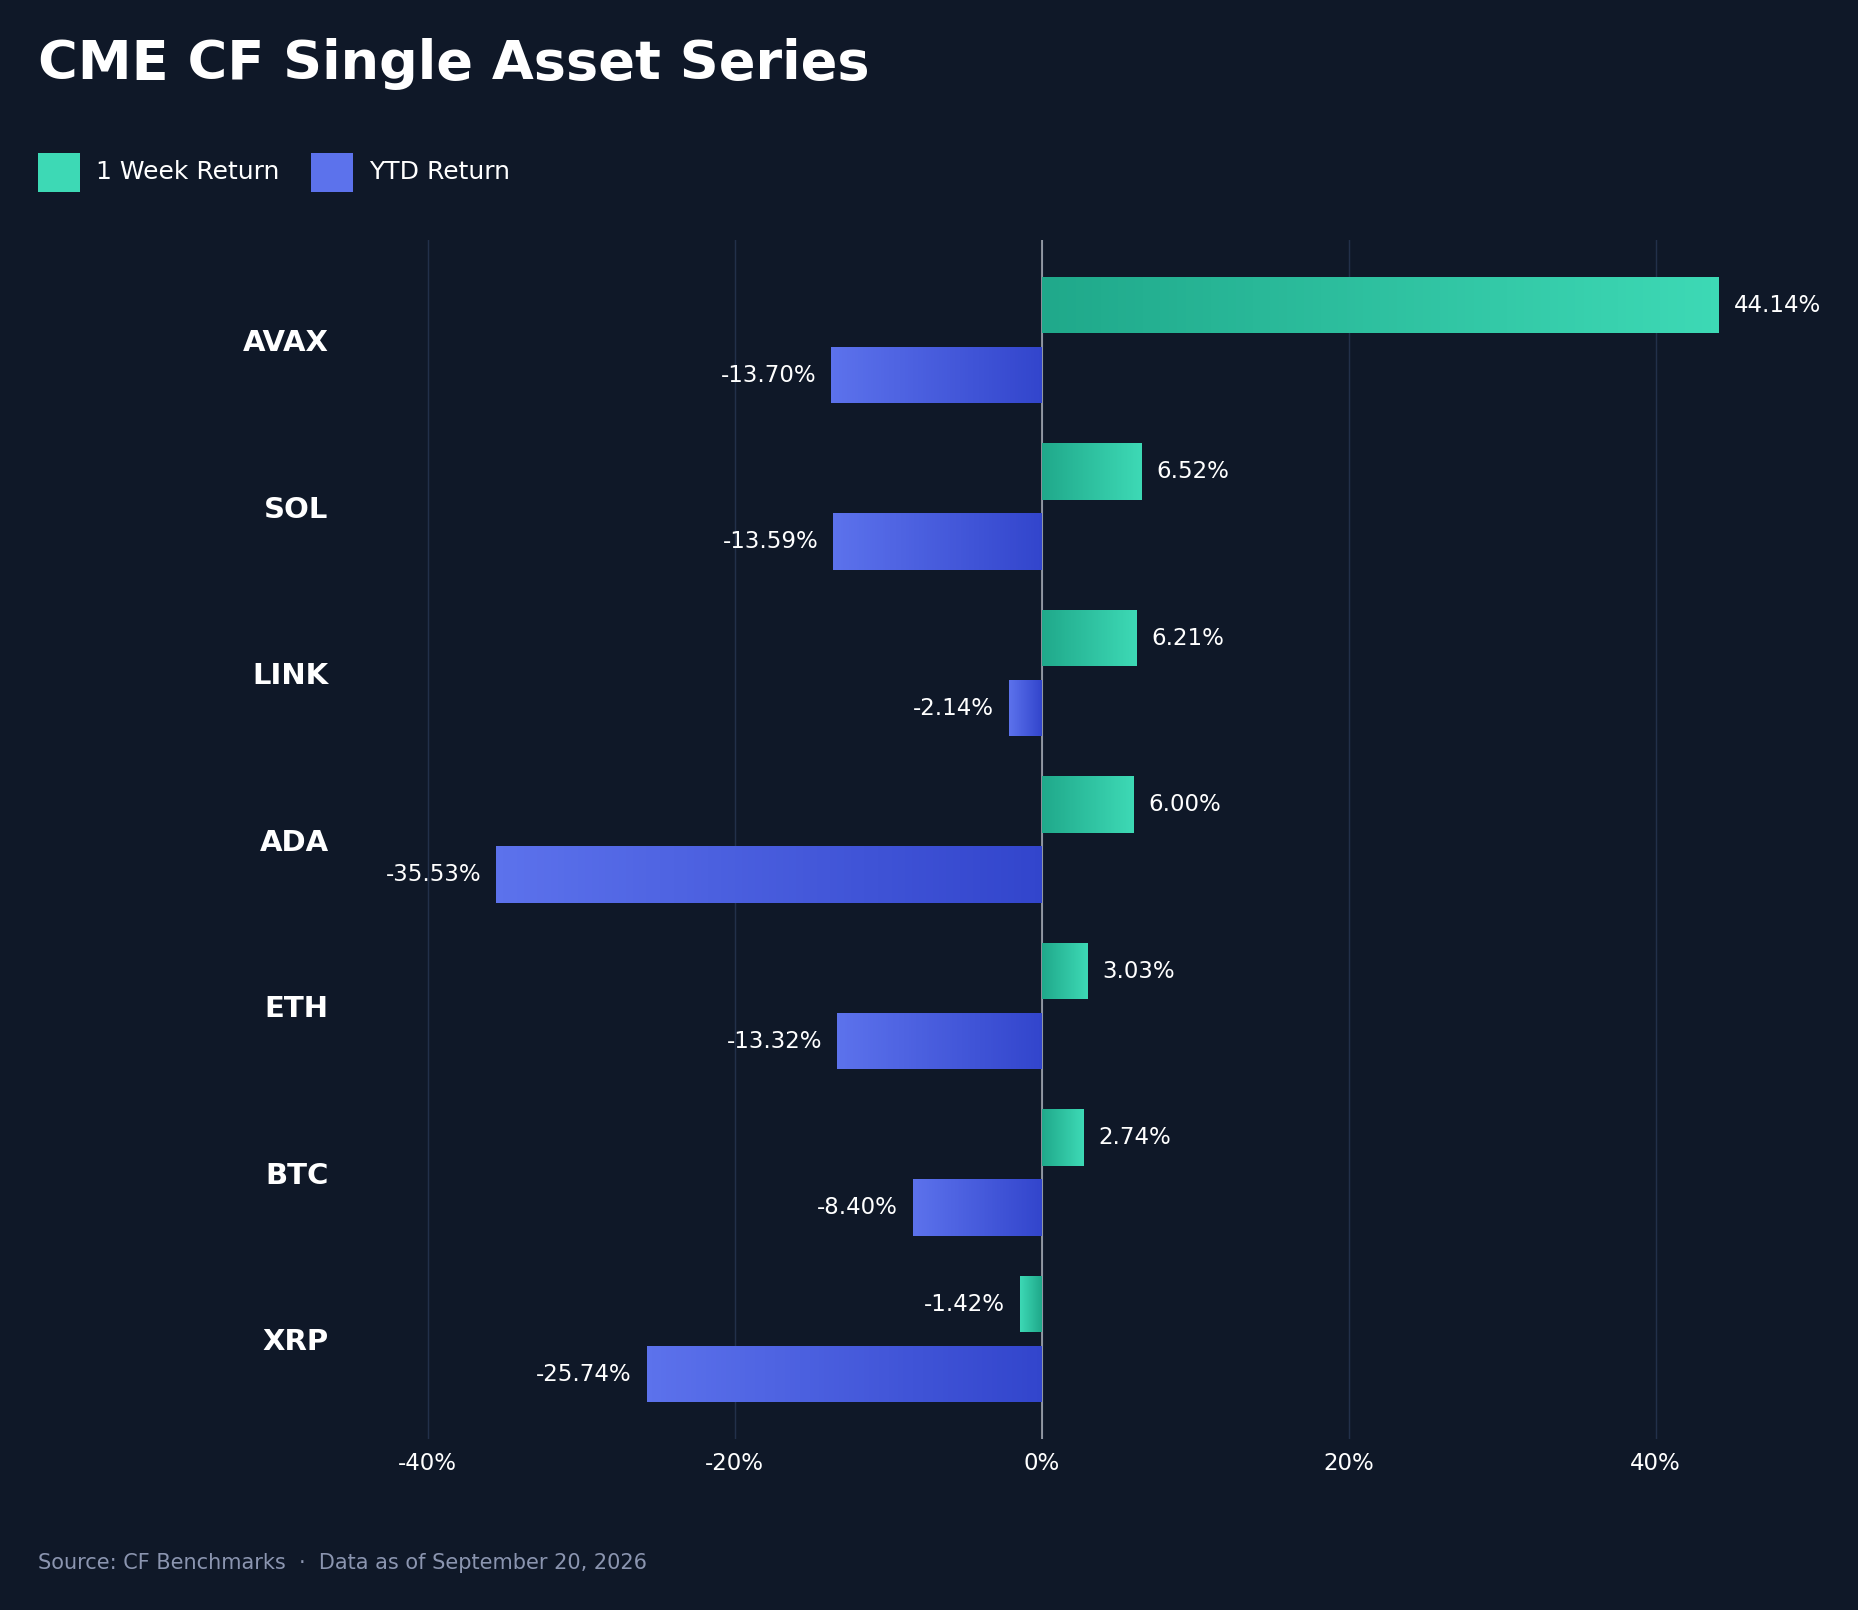
The week's macro catalyst was Wednesday's Federal Open Market Committee decision: the Fed unanimously raised the target range 25 bps to 3.75% to 4.00%, its first increase since 2023. The hike was largely priced in ahead of the meeting, and Bitcoin (BTC) was roughly flat in the minutes around the announcement before briefly reaching $76,000, so its +2.74% week-on-week (w/w) gain is better read as resilience to expected tightening than a relief response to a policy surprise. The CF Single Asset Series recorded six gains across its seven-name set over September 14th to September 20th. Avalanche (AVAX) led at +44.14%, although its year-to-date (YTD) return remained -13.70%. Solana (SOL) rose 6.52% (YTD -13.59%), Chainlink (LINK) 6.21% (YTD -2.14%), Cardano (ADA) 6.00% (YTD -35.53%), Ether (ETH) 3.03% (YTD -13.32%) and BTC 2.74% (YTD -8.40%). XRP was the sole decliner at -1.42% (YTD -25.74%). The 45.56 pp gap between AVAX and XRP, compared with a 13.11 pp range a week earlier, shows that the advance was broad but far from uniform. Every asset improved on its prior weekly return, with leadership concentrated in higher-beta networks rather than the largest assets.
Volatility Analysis
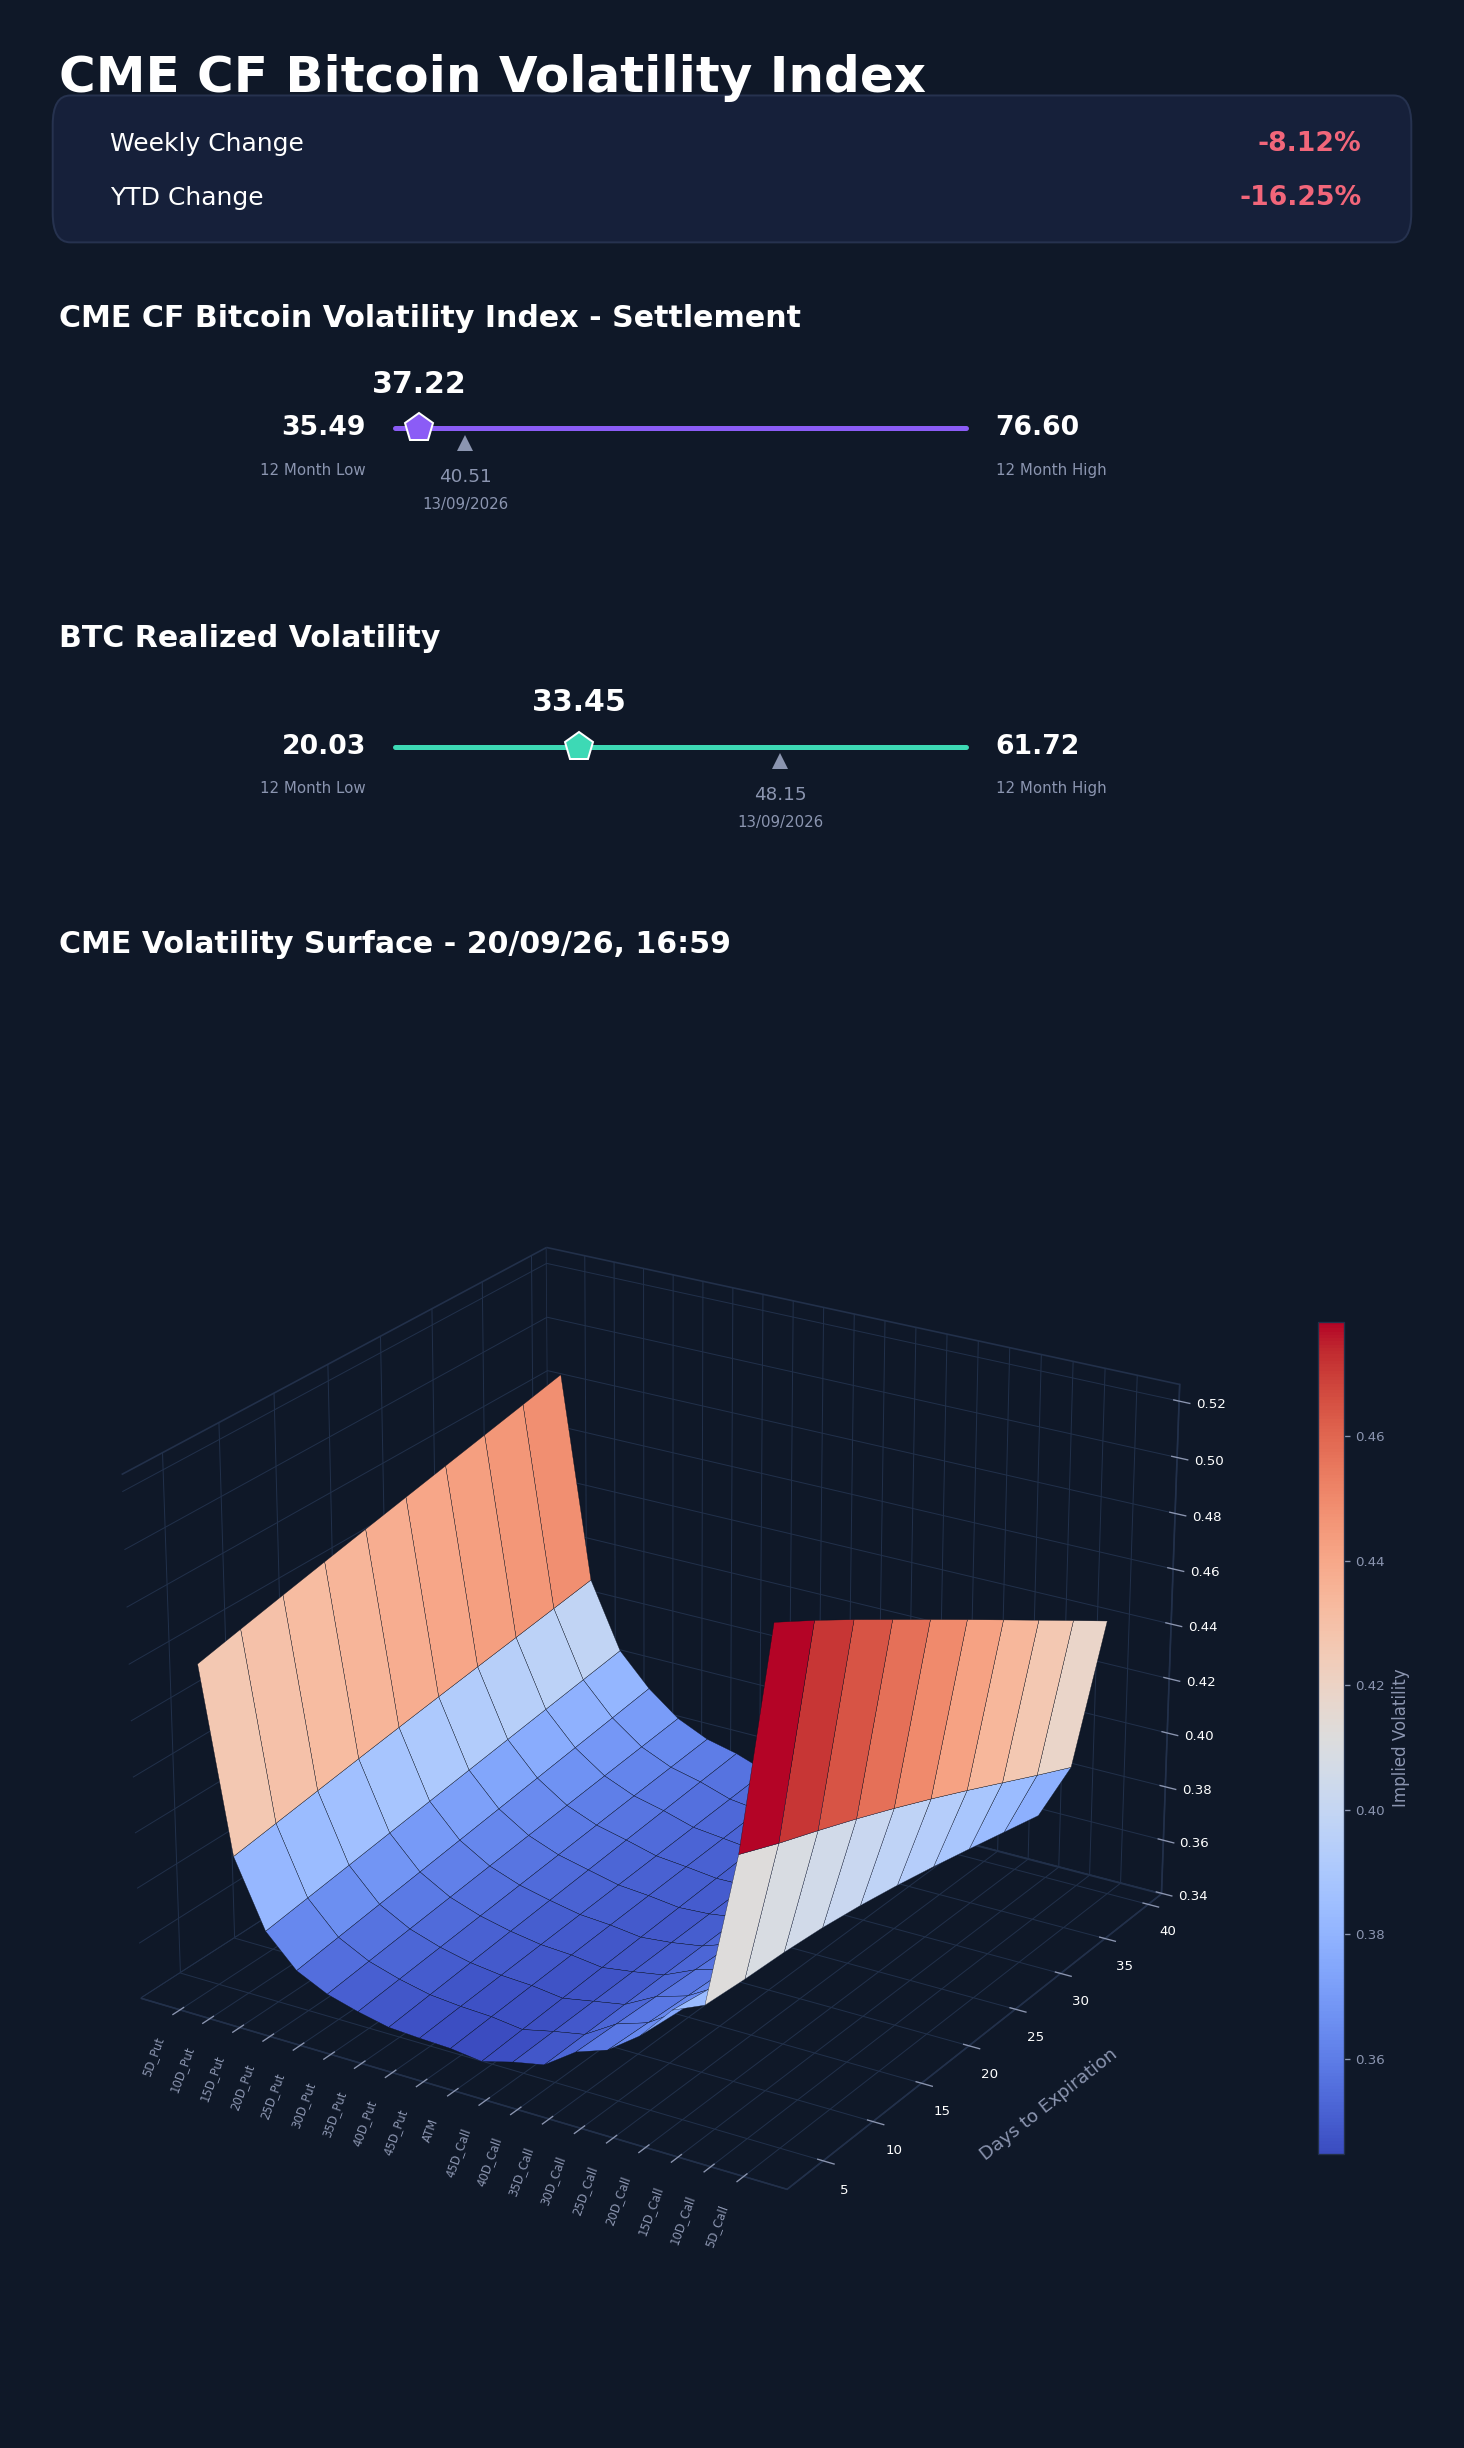
The CME CF Bitcoin Volatility Index Settlement (BVXS) finished September 20th at 37.22, down from 40.51 a week earlier, an 8.12% Sunday-to-Sunday decline. Thirty-day realized volatility fell to 33.45 from 48.15, moving the implied-minus-realized spread to +3.77 vol. points from -7.64. During the business week, BVXS reached 42.33 on Tuesday before finishing Friday at 37.67; realized volatility closed Friday at 52.53 before falling sharply over the weekend. The Sunday settlement remained 1.73 vol. points above its trailing 12-month low of 35.49, within a 35.49-to-76.60 range, and 16.25% below the 44.44 start-of-year reference. Realized volatility also moved toward the lower end of its 20.03-to-61.72 range. At the shortest available surface tenor, 4 days versus 11 days in the prior clean snapshot, at-the-money implied volatility was 34.35 and the 5-delta put was 45.79. The 25-delta put premium over at-the-money was 0.81 vol. points, compared with 1.69 vol. points at the prior snapshot's shortest tenor. These are endpoint comparisons, not matched maturities. Lower implied and realized volatility accompanied the week's positive spot returns, with realized volatility adjusting more sharply.
Market Cap Index Performance
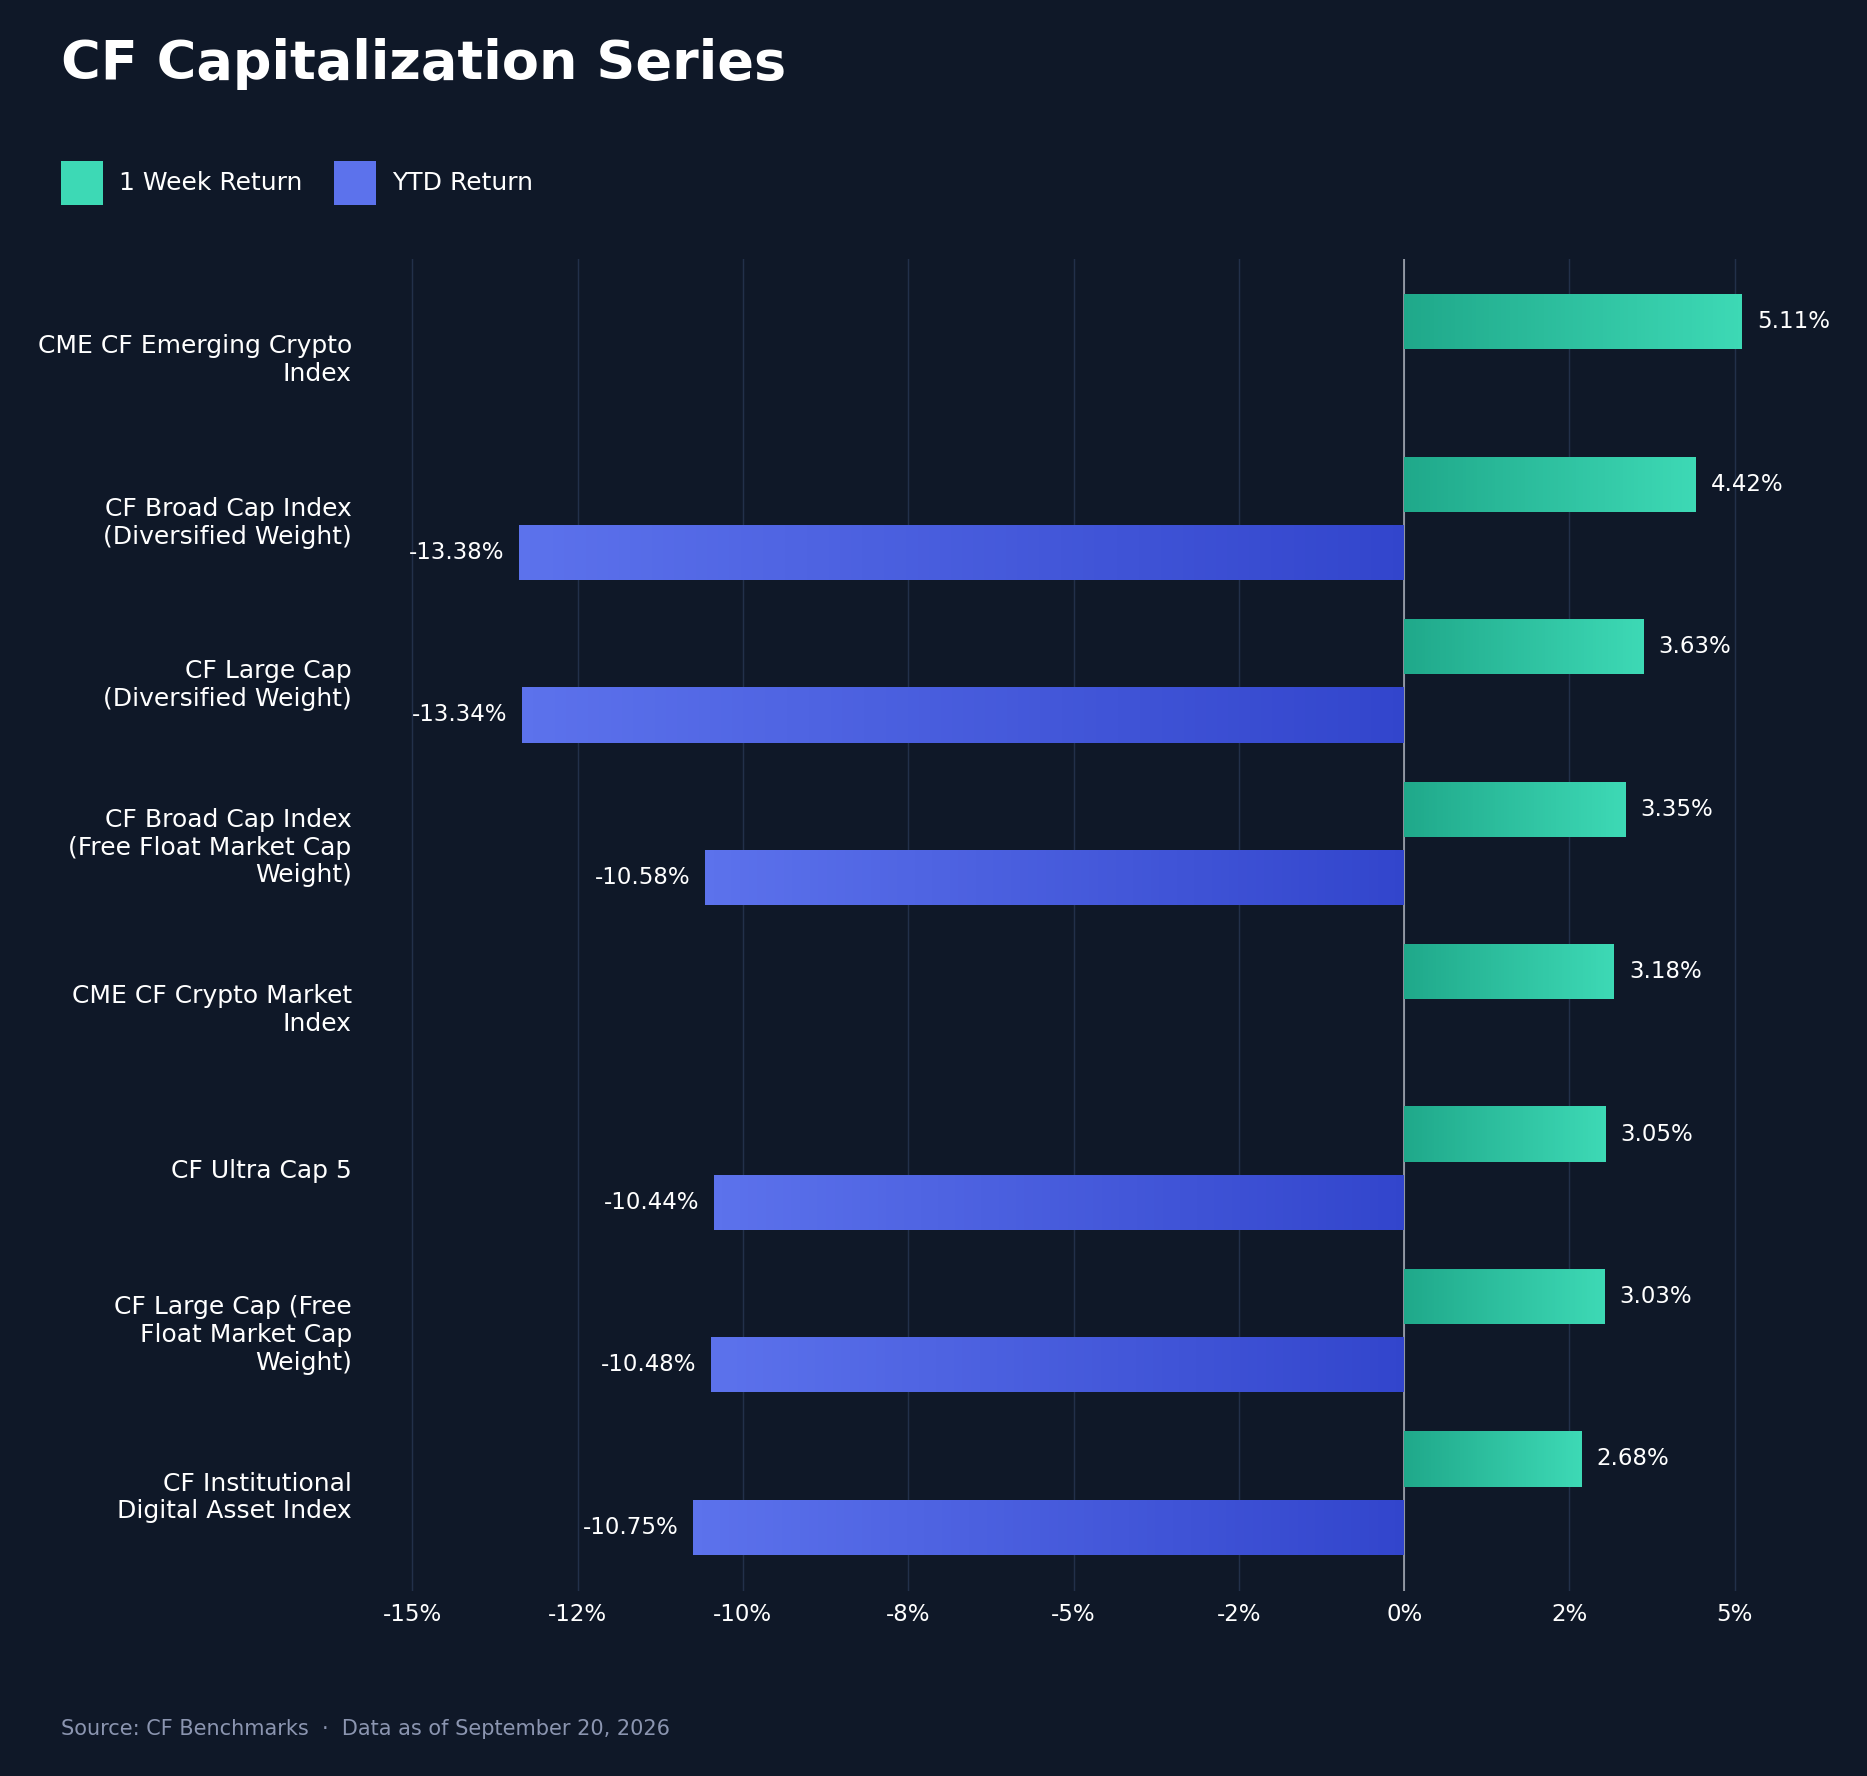
All eight CF Capitalization Series indices advanced, reversing the prior week's uniformly negative performance, even as US spot Bitcoin ETF flows finished near flat at +$6.2 million and spot Ether funds recorded $140 million of net redemptions. That split shows that the broad index rebound was not matched by uniform demand through US institutional vehicles. The CME CF Emerging Crypto Index led at +5.11% w/w, followed by CF Broad Cap Index (Diversified Weight) at +4.42% (YTD -13.38%), CF Large Cap (Diversified Weight) at +3.63% (YTD -13.34%), CF Broad Cap Index (Free Float Market Cap Weight) at +3.35% (YTD -10.58%), the CME CF Crypto Market Index at +3.18%, CF Ultra Cap 5 at +3.05% (YTD -10.44%), CF Large Cap (Free Float Market Cap Weight) at +3.03% (YTD -10.48%), and CF Institutional Digital Asset Index at +2.68% (YTD -10.75%). The 2.43 pp range between the best and worst index was similar to the prior week's 2.62 pp range, but the ranking reversed. Large Cap Diversified beat its free-float counterpart by 0.59 pp and Broad Cap Diversified by 1.07 pp, after lagging by 0.50 pp and 0.73 pp respectively a week earlier. That weighting comparison confirms that the rebound strengthened beyond the most heavily capitalized assets. YTD values for the Crypto Market and Emerging Crypto indices remain unavailable because their start-of-year fixes are missing.
Factors Analysis
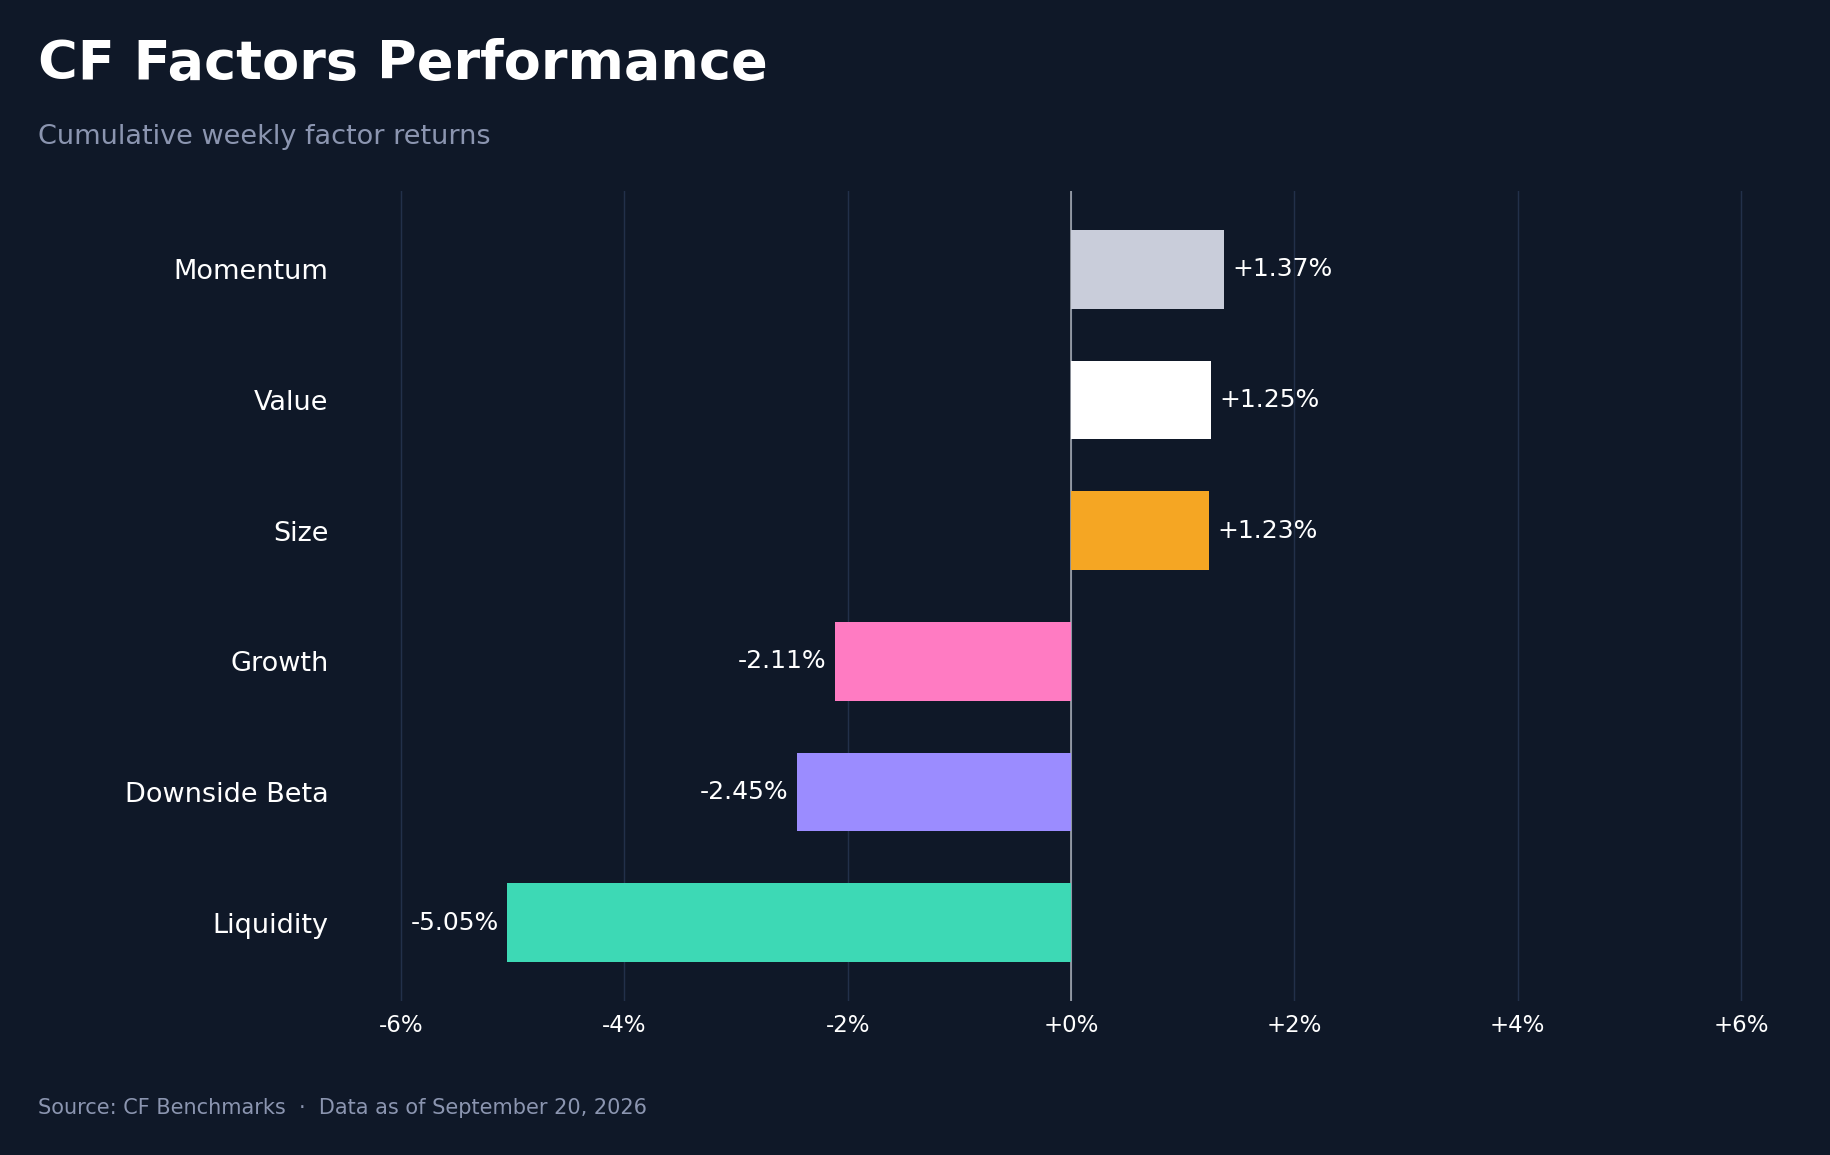
Momentum led the six CF factors at +1.37% cumulative for the week, followed by Value at +1.25% and Size at +1.23%. Growth returned -2.11%, Downside Beta -2.45% and Liquidity -5.05%, leaving a 6.42 pp range compared with 5.02 pp in the prior week. Momentum improved 2.49 pp from -1.11% and moved from fifth place to first, while Value and Size remained positive. Liquidity recorded the largest deterioration, falling 5.70 pp from +0.65%, followed by Downside Beta's 4.62 pp reversal from +2.16%. Growth remained negative but improved 0.75 pp from -2.86%. Three factor portfolios gained and three declined despite the broad spot advance. Leadership favored Momentum, Value and Size, while Liquidity's sharp underperformance was the clearest exception to the positive index backdrop.
Read our latest weekly crypto factors report: Factor Friday - September 18, 2026
Classification Series Analysis
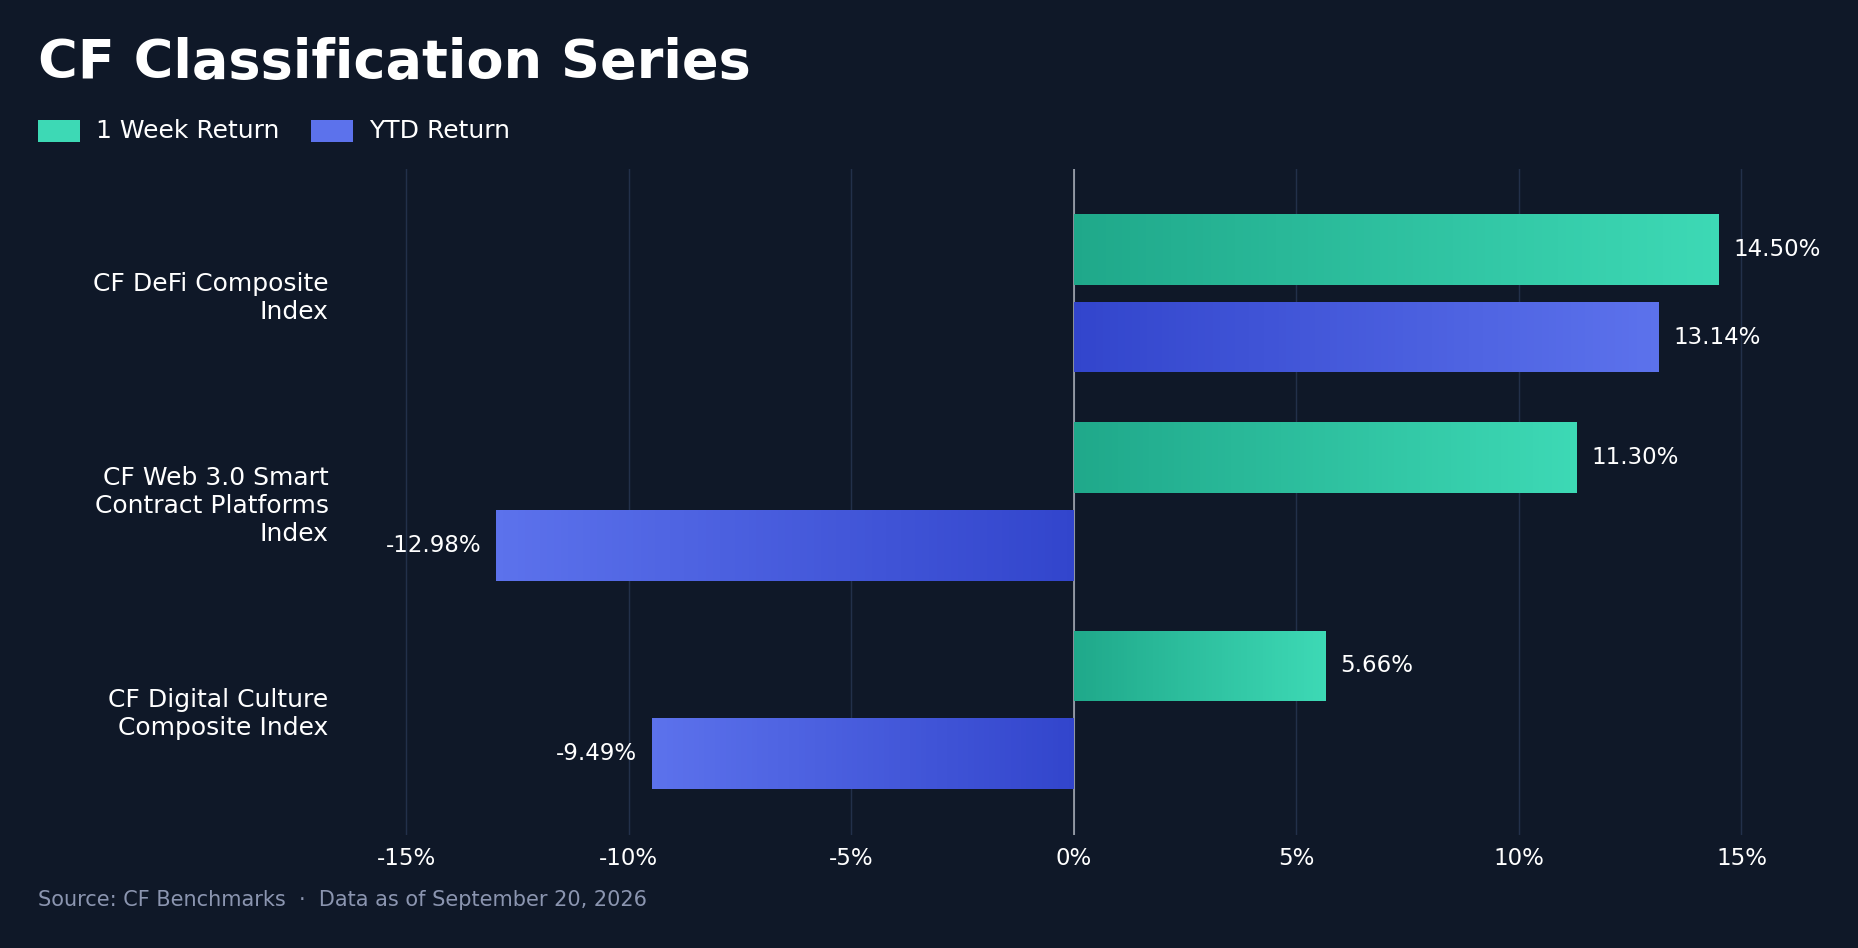
All three CF Classification Series composites advanced, reversing the prior week's declines. The CF DeFi Composite Index led at +14.50% w/w after falling 8.41% a week earlier, a 22.91 pp improvement that lifted its YTD return to +13.14%. The CF Web 3.0 Smart Contract Platforms Index gained 11.30% (YTD -12.98%), while the CF Digital Culture Composite Index rose 5.66% (YTD -9.49%). The weekly return range widened to 8.84 pp from 3.15 pp, with DeFi separating most clearly from Digital Culture. Each composite improved by at least 10.92 pp from its prior weekly result, but DeFi's reversal was the largest and restored its positive YTD lead. The rebound was broad across classifications and concentrated in decentralized finance and smart-contract platforms.
Sector Analysis
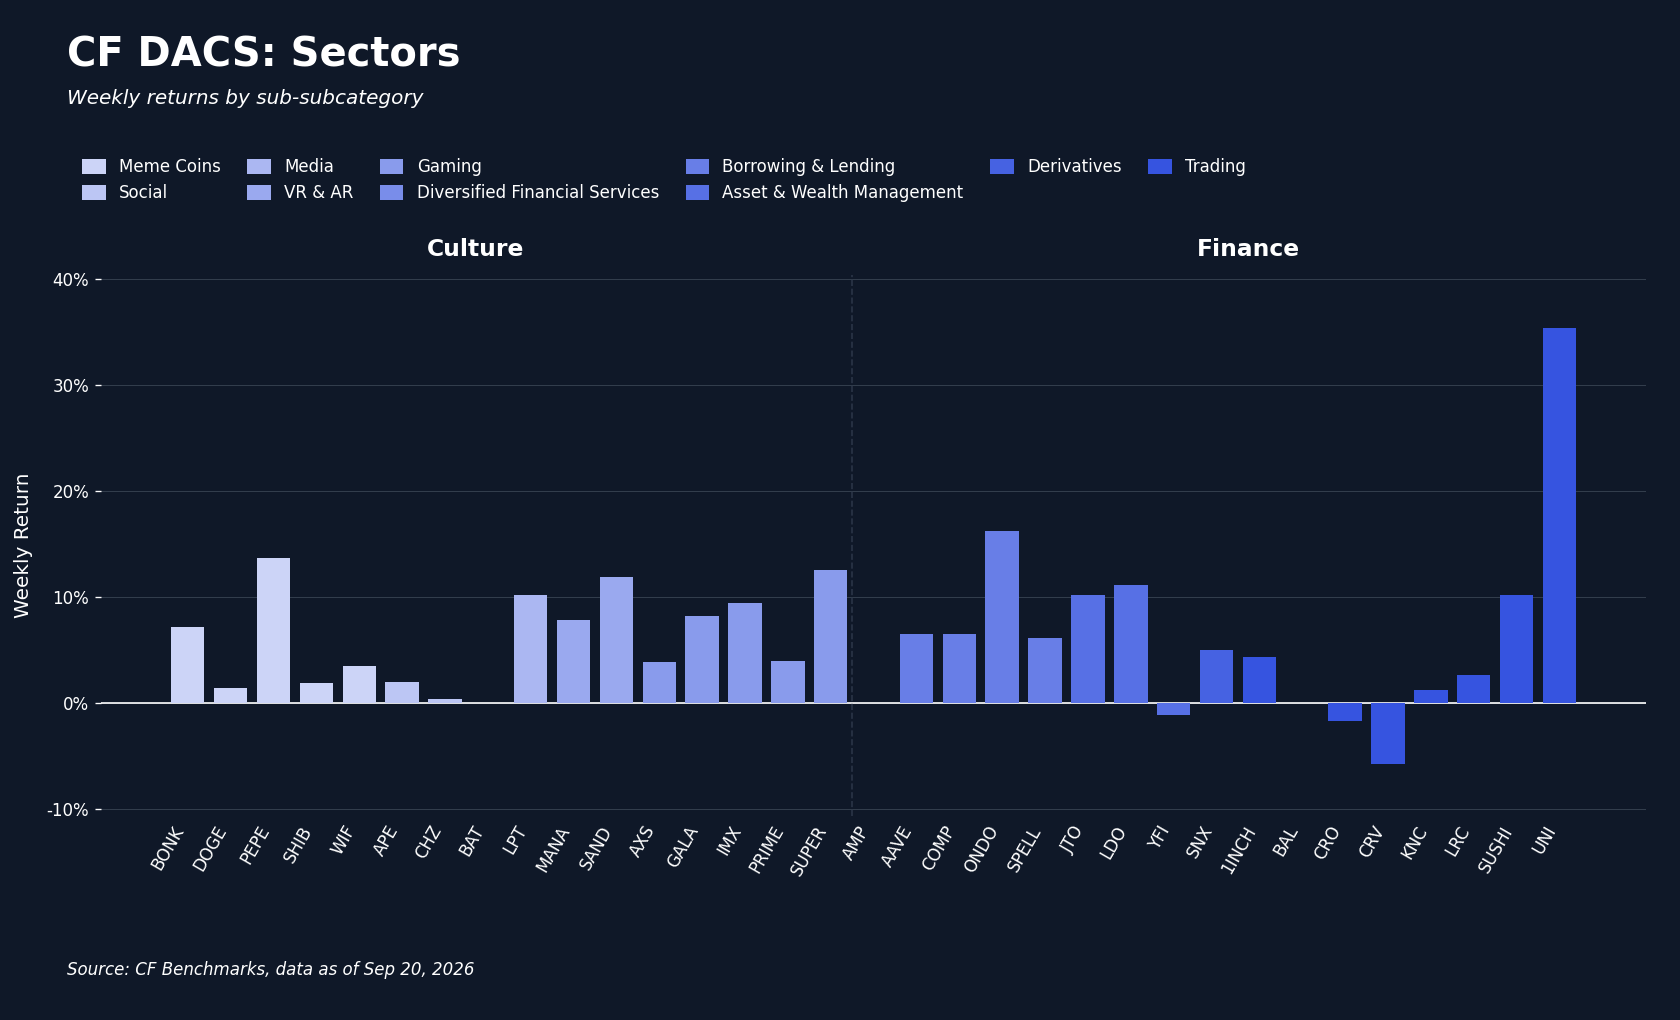
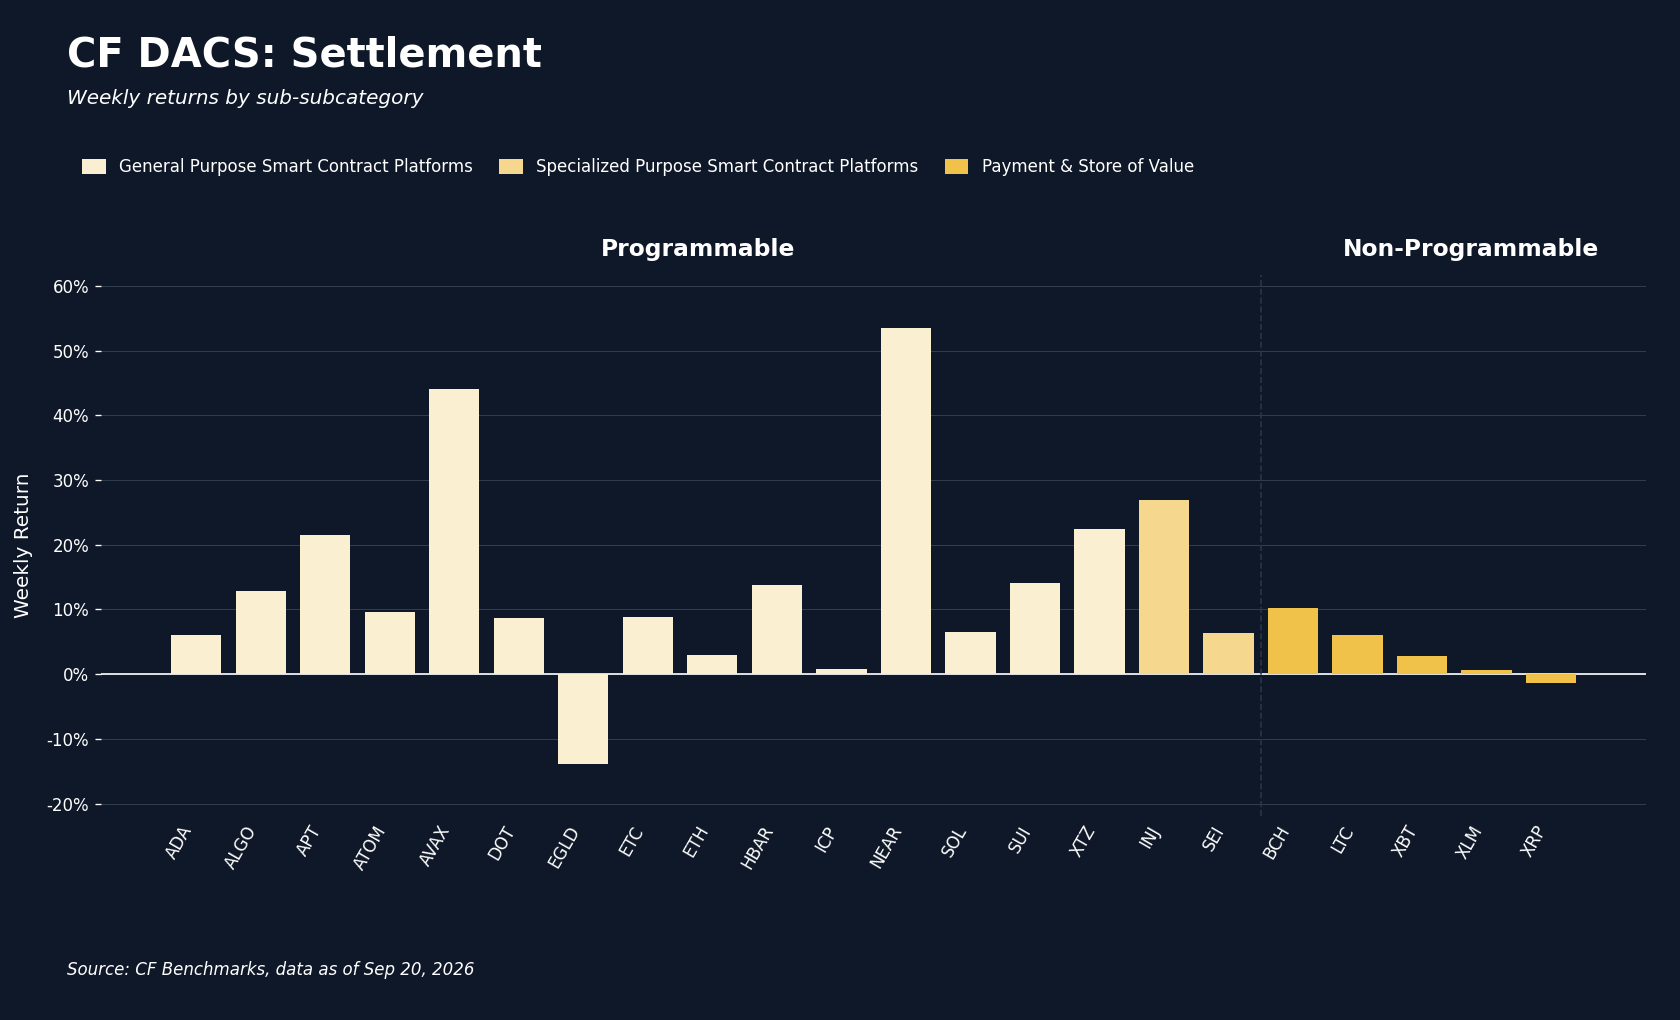
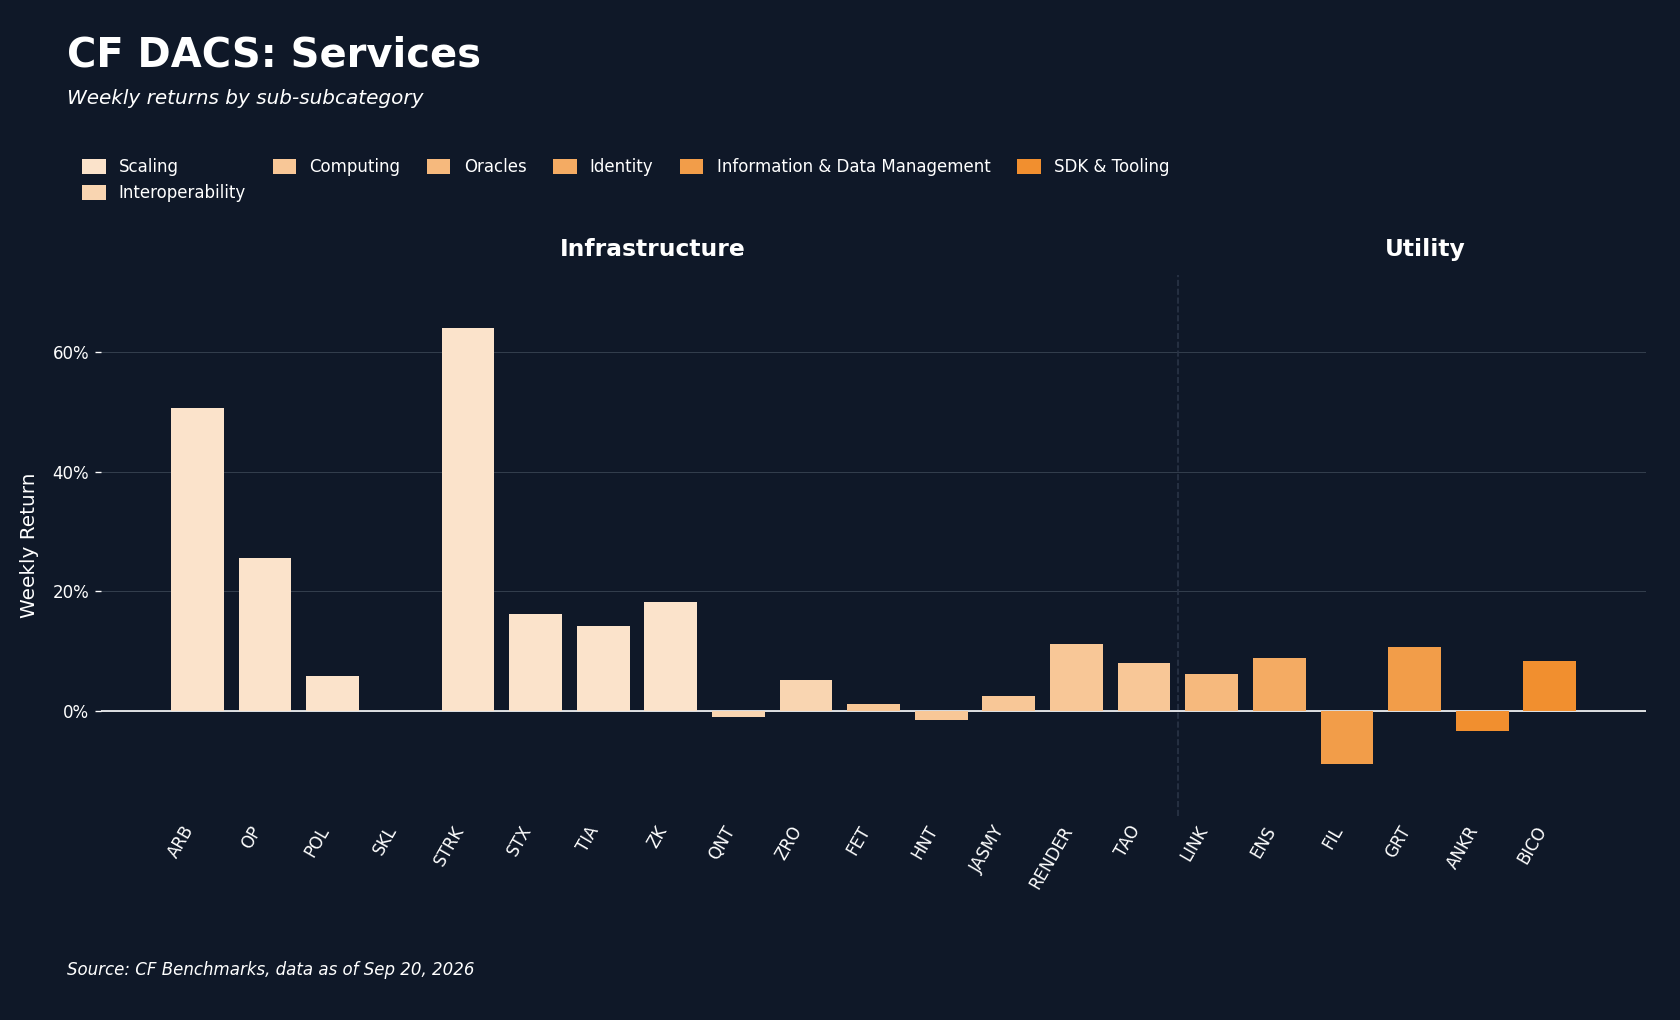
Every CF DACS sub-category recorded a positive average. Infrastructure gained 14.70% and Programmable 14.43%, followed by Finance at 6.30%, Culture at 6.14%, Utility at 3.68% and Non-Programmable at 3.65%. The 11.06 percentage point (pp) gap between Infrastructure and Non-Programmable shows that the rebound reached all six groups but favored higher-beta network activity. Infrastructure contained two of the four strongest constituents, with Starknet (STRK) up 64.11% and Arbitrum (ARB) 50.71%, while Optimism (OP) gained 25.56%. Those moves formed part of a broad Layer 2 and decentralized finance advance after the Fed meeting. Programmable also had concentrated leadership. Near Protocol (NEAR) gained 53.53% during a week when disclosed network metrics included confidential value locked above $70 million and staking-based computing credits across 43 artificial intelligence models. Avalanche (AVAX) rose 44.14% after the UAE PASS Digital Vault announced an upgrade to a dedicated Avalanche L1 and New York Life Investment Management announced its first tokenized fund on the network. Those gains coincided with the wider market rebound. Excluding NEAR and AVAX lowers the Programmable average to 9.84%, a 4.59 pp difference, showing how much of the sub-category result was concentrated in the pair without establishing causation. Uniswap (UNI) led Finance at 35.41%. The week's largest declines were MultiversX (EGLD) at -13.82%, Filecoin (FIL) at -8.81% and Curve (CRV) at -5.71%. Across 76 constituents with valid weekly returns, STRK and EGLD defined a 77.93 pp spread.
CF Staking Series
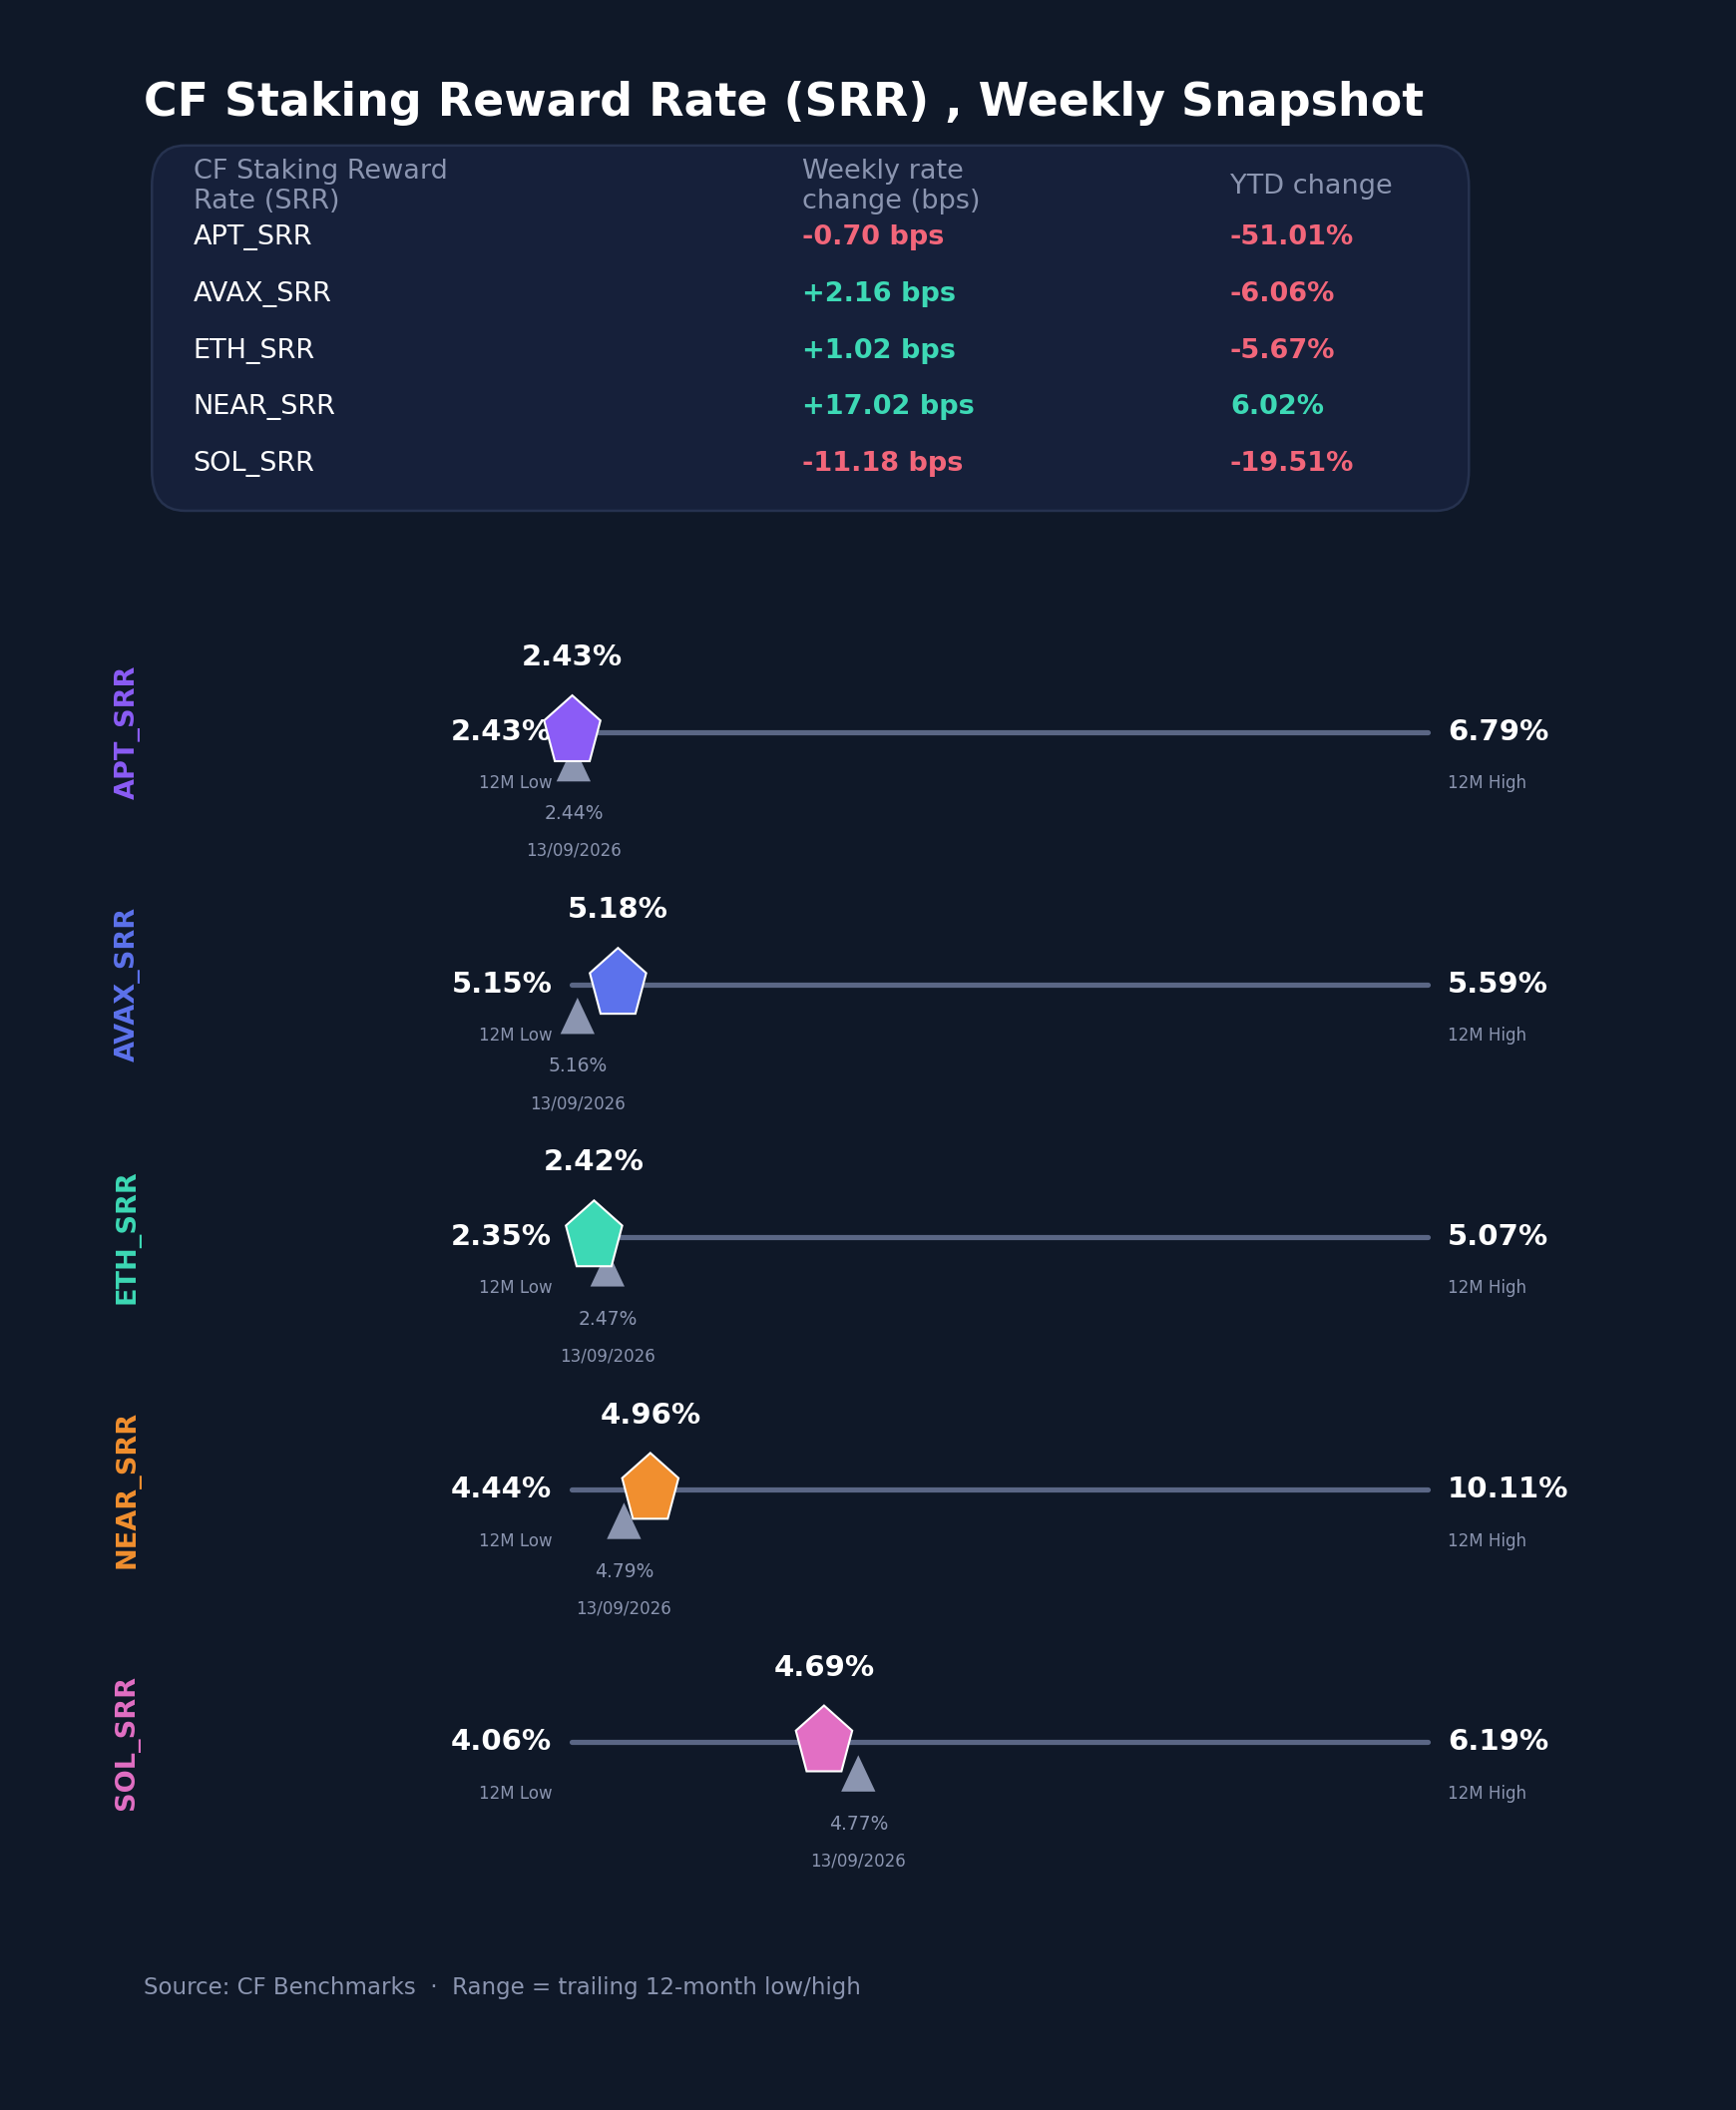
The CF Staking Series again showed a different ordering from spot performance. Near Protocol (NEAR) led the relative rate-index returns at +3.55% w/w, followed by Ether (ETH) at +0.42% and Avalanche (AVAX) at +0.42%, while Aptos (APT) declined 0.29% and Solana (SOL) fell 2.33%. These are relative changes in the series, not staking income earned during the week. Within-week reward-rate changes were +17.0 basis points (bps) for NEAR, +2.2 bps for AVAX and +1.0 bps for ETH, while APT fell 0.7 bps and SOL fell 11.2 bps. Comparing the reference levels with the prior Sunday, NEAR increased to 4.9638% from 4.7893% and AVAX to 5.1783% from 5.1575%, while ETH eased to 2.4228% from 2.4653%, APT to 2.4313% from 2.4380% and SOL to 4.6884% from 4.7738%. The within-week changes use the Monday reference, so they need not equal the Sunday-to-Sunday differences. Current reward rates spanned 2.76 pp, with ETH now the lowest and AVAX the highest. NEAR's increase and SOL's decline widened their separation despite both tokens participating in the spot rally.
Interest Rate Analysis
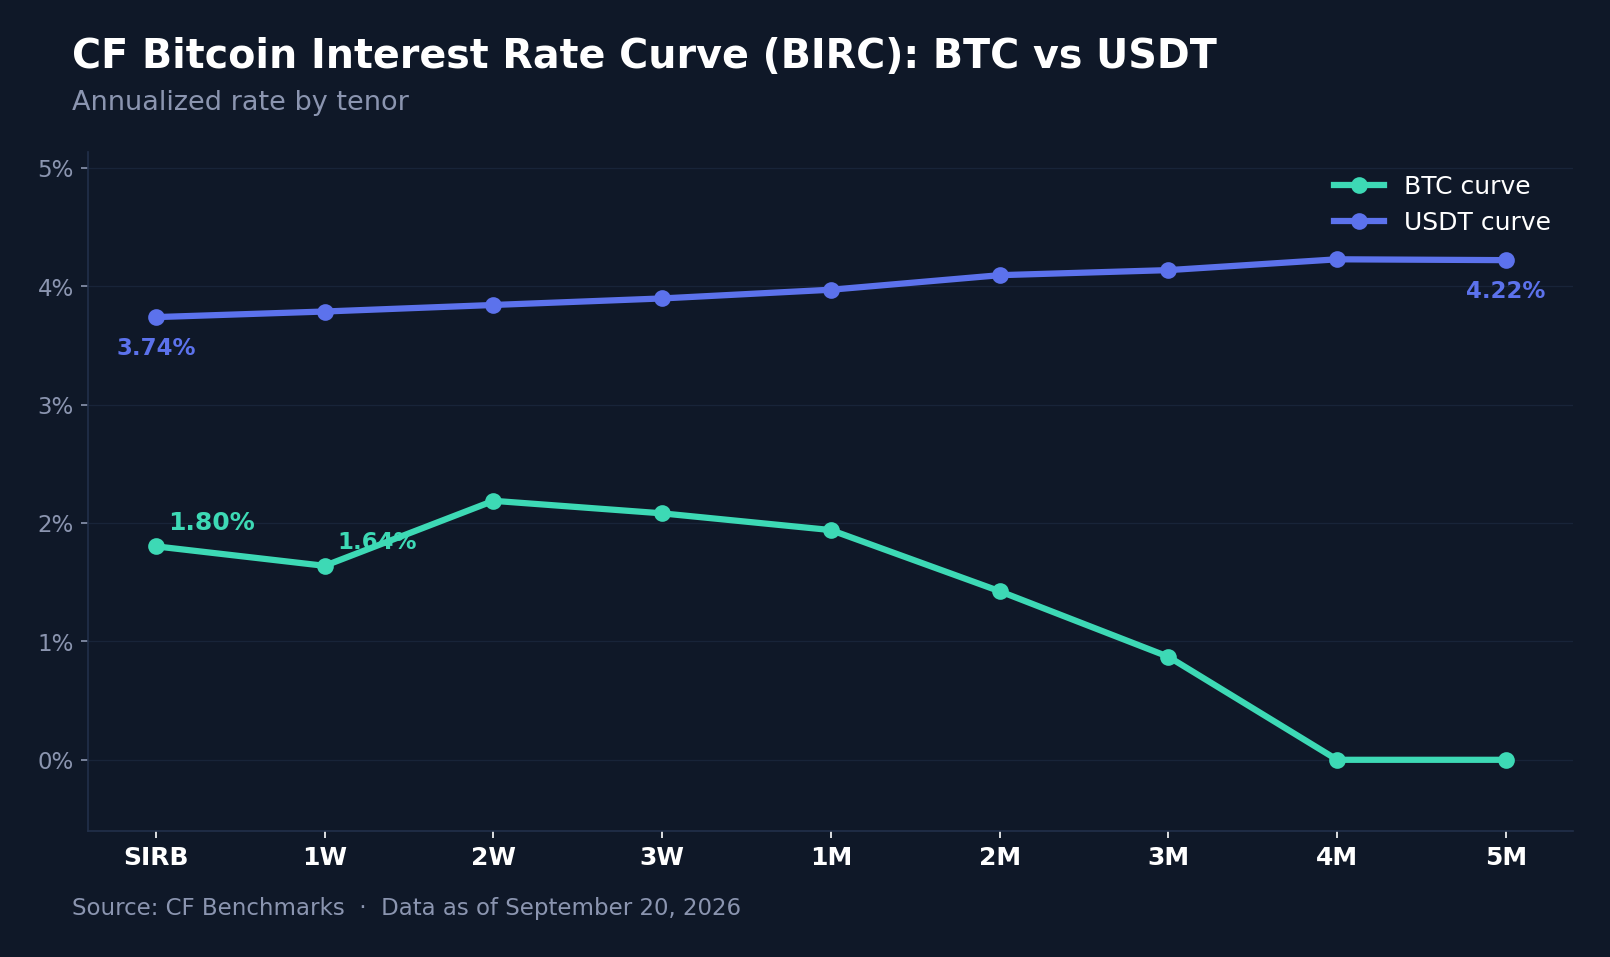
The CF Bitcoin Interest Rate Curve (BIRC) showed a much larger rise in BTC funding than in USDT funding. On the weekly-average basis, BTC's Short-term Interest Rate Benchmark (SIRB) increased 100.3 bps to 1.8037% from 0.8006%, and the 1-week (1W) rate rose 87.6 bps to 1.6391%. The 2-week (2W) tenor increased 168.1 bps to 2.1886%, the largest move on the curve; 3-week (3W) rose 155.5 bps to 2.0826%, 1-month (1M) 131.7 bps to 1.9413%, 2-month (2M) 66.8 bps to 1.4244%, and 3-month (3M) 35.8 bps to 0.8706%. The reported BTC 4-month and 5-month rates remained at 0.0000%. USDT rates rose at every tenor by between 1.9 and 8.1 bps, with SIRB at 3.7410%, 1W at 3.7884% and 3M at 4.1381%. Its curve remained generally upward-sloping, reaching 4.2296% at 4M before a small dip to 4.2224% at 5M. USDT's premium over BTC at SIRB narrowed to 193.7 bps from 292.1 bps. The much larger BTC adjustment points to a currency-specific normalization in funding alongside the spot rebound, not an equal shift in both curves.
Closing Synthesis
The Fed's first rate increase since 2023 drew little immediate Bitcoin reaction. After the meeting, every capitalization and classification index advanced, diversified portfolios beat their free-float counterparts, and all six populated DACS sub-category averages turned positive as Layer 2 and DeFi tokens led the rebound. NEAR and AVAX announcements coincided with concentrated strength within Programmable, while mixed ETF flows showed that the breadth was not mirrored across institutional vehicles. The cross-section remained uneven. Momentum, Value and Size gained while Liquidity, Downside Beta and Growth declined; NEAR's reward rate rose as SOL's fell; and XRP lagged a six-asset advance. Implied and realized volatility fell, while BTC funding rose more than USDT funding. The result was a broad post-Fed risk-on rotation with concentrated network leadership and separate adjustments in volatility, style returns, reward rates and funding.
The information contained within is for educational and informational purposes ONLY. It is not intended nor should it be considered an invitation or inducement to buy or sell any of the underlying instruments cited including but not limited to cryptoassets, financial instruments or any instruments that reference any index provided by CF Benchmarks Ltd. This communication is not intended to persuade or incite you to buy or sell security or securities noted within. Any commentary provided is the opinion of the author and should not be considered a personalised recommendation. Please contact your financial adviser or professional before making an investment decision.
Note: Some of the underlying instruments cited within this material may be restricted to certain customer categories in certain jurisdictions.
Digital Assets Move Higher After the Rate Hike
An expected Fed hike gave way to a broad crypto rebound led by Infrastructure, DeFi and Programmable assets, while lower volatility and firmer Bitcoin funding pointed to normalization rather than uniform stress.
Mark Pilipczuk
Factor Friday - September 18, 2026
Value led CF Benchmarks' factor table for a third straight week at 1.85%, even as its pace cooled. Growth flipped positive while Downside Beta turned negative for the first time in three weeks, and the Market's decline eased sharply to 0.70% from last week's near-5% drop.
Mark Pilipczuk
Changes to the Token Market Price Benchmarks Series - Market Prices – 15 September 2026
The Administrator has confirmed changes to the Token Market Price Family for the period 08 September 2026 to 15 September 2026
CF Benchmarks
By clicking Accept, you consent to CF Benchmarks's use of cookies.
Visit Cookie Settings to learn how CF Benchmarks uses cookies and to adjust your preferences.