
Sep 18, 2026
Factor Friday - September 18, 2026
Value Extends Its Lead as Downside Beta Falls
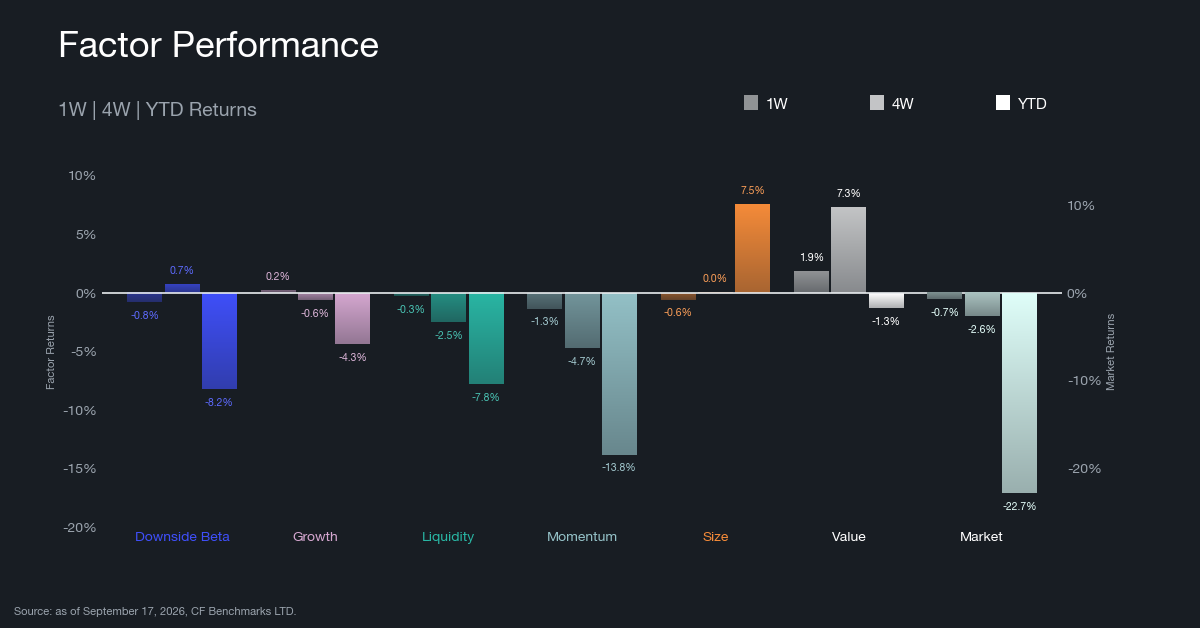
Value led the weekly factor table for a third consecutive week, gaining 1.85%. Growth reversed from last place to second, rising 0.20% after a 2.74% decline, while Liquidity (-0.25%) and Size (-0.55%) posted only modest losses. The Market slipped 0.70%, a far milder retracement than last week's 4.98% drop, and Downside Beta turned negative at -0.80% after sitting essentially flat at 0.05% the week before, its third straight week of fading from the 3.20% lead it held two weeks ago. Over four weeks, Value's advance has compounded to 7.30%, the strongest of any factor by a wide margin, while Momentum remains the deepest laggard at -4.73%. Year to date, Size is still the only factor decisively positive at 7.53%; the Market carries the year's steepest drawdown at -22.71%, with Momentum next worst at -13.79%. This week's performance looked like that of a market rewarding fundamentally grounded exposure over broad beta or defensive positioning.
Rolling Factor Rankings and Rotation
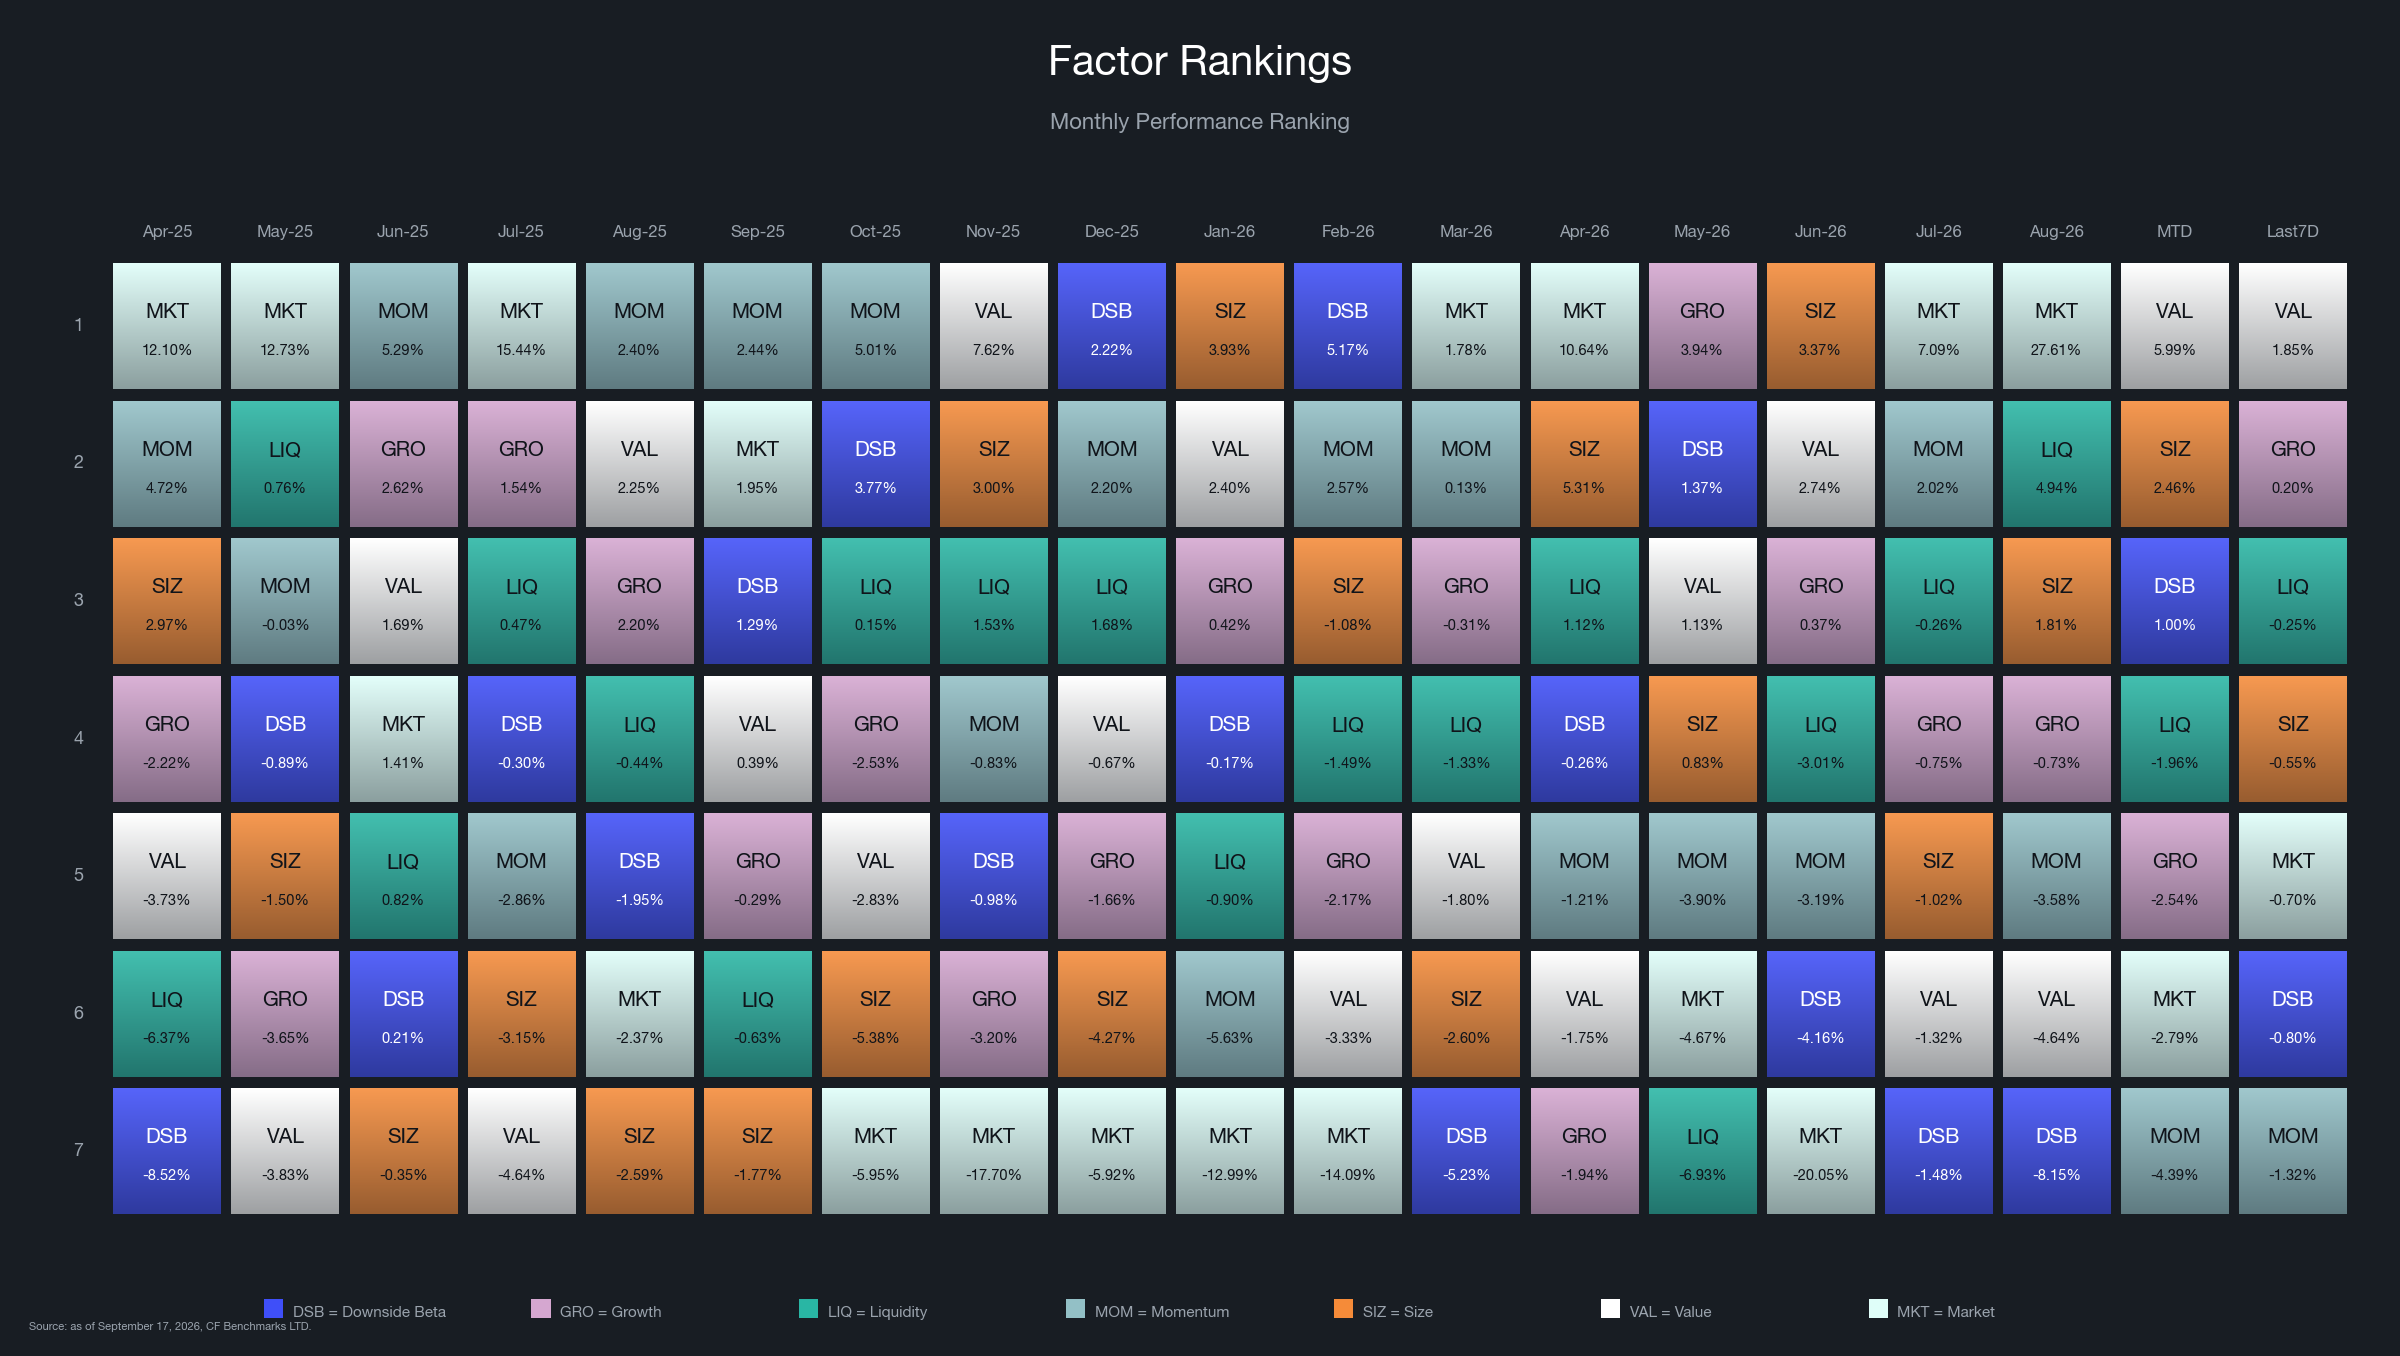
The rotation extended further than the reversal seen seven days ago. Growth, last week's bottom performer at -2.74%, jumped to second at 0.20%, while Downside Beta, third last week at a flat 0.05%, slid to sixth at -0.80%. The Market climbed two spots even while still posting a loss, rising from last place to fifth as its weekly decline eased from 4.98% to 0.70%. Momentum moved the other way, dropping from fifth to last as its return worsened only slightly, from -1.95% to -1.32%. Value held the top spot for a third straight week, its margin over second place widening from 0.10 percentage points seven days ago to 1.65 points now as the pack behind it cooled. The month-to-date ranking has barely moved: Value, Size and Downside Beta still occupy the top three spots at 5.99%, 2.46% and 1.00% respectively, the same order as a week ago, with Momentum (-4.39%) again last. A shuffling weekly table sitting on top of an unchanged monthly one says the rotation beneath Value is more noise than trend, at least until the monthly ranking itself starts to move.
Market and Key Factor Betas
Market Beta
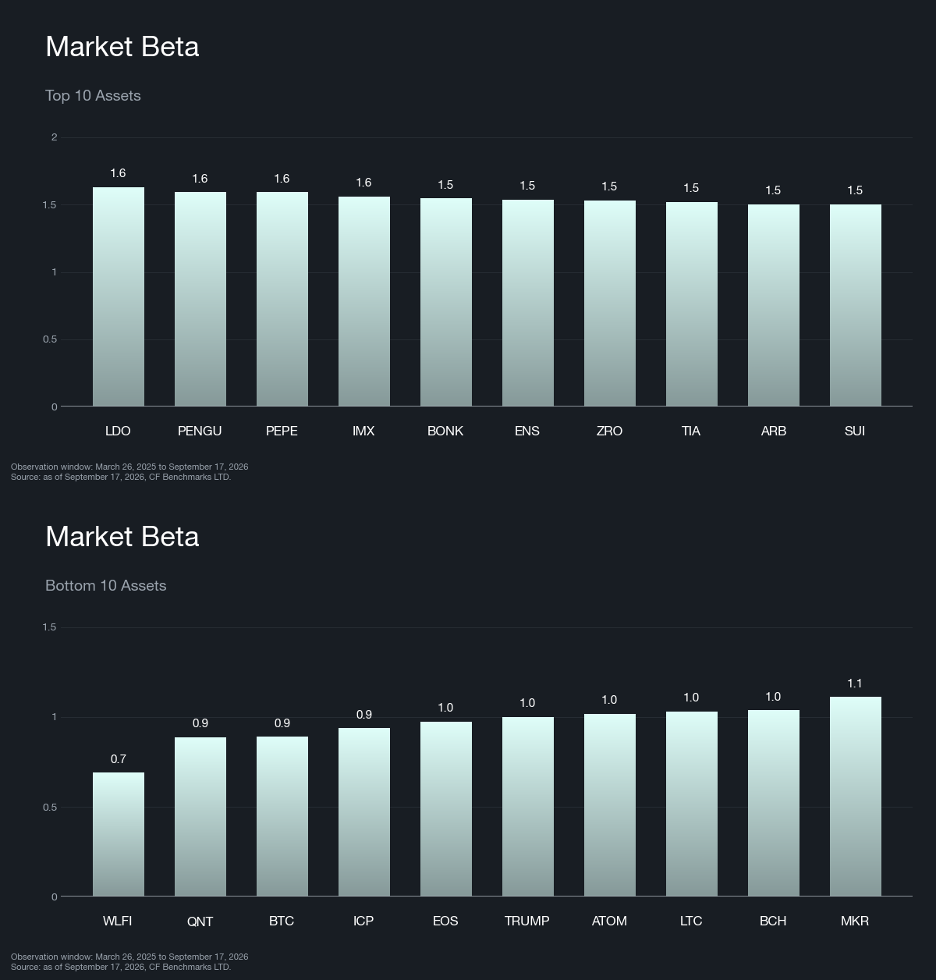
Market-beta composition held for a ninth straight week, the same ten names anchoring both ends of the list. Lido (LDO) remains alone at the top, unchanged at 1.62, while Zero (ZRO) cooled from second to seventh as its beta eased from 1.60 to 1.53; meme coins and gaming tokens, alongside modular infrastructure names, fill out the rest of the high-beta cohort in largely the same order. The defensive end is just as static: WLFI still sits lowest at 0.69, with Quant (QNT) edging fractionally below Bitcoin (BTC) for the second-lowest slot as enterprise interoperability and legacy payment names round out the floor. A ninth straight week of an unchanged roster, spanning both last week's Market selloff and this week's milder one, says broad-beta positioning has not moved even as the Market's own return has swung sharply in both directions. The risk is that this static book turns out to be complacency if the Market's next move is sharp enough to force a reshuffle.
Value
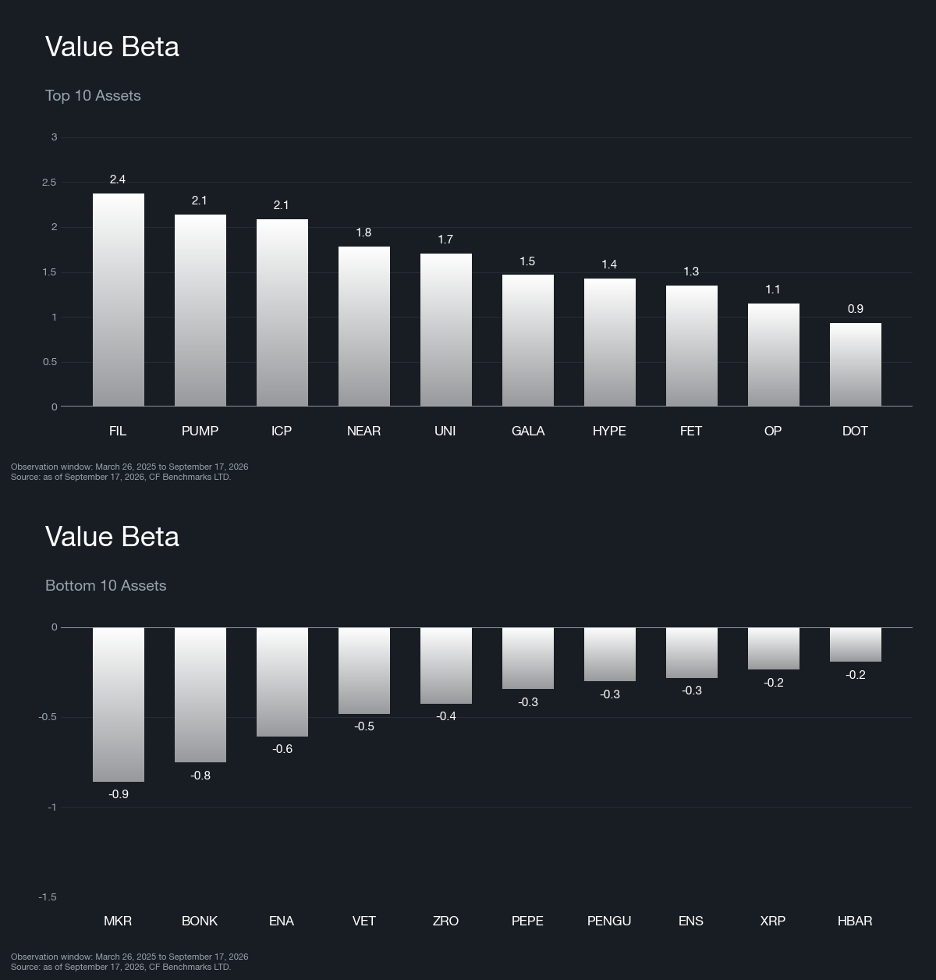
Value's third straight week atop the factor table has not required any change in its cohort. Filecoin (FIL) leads the high value-beta list, essentially unchanged at 2.37. The rest of the top ten holds the same order as last week, running from Pump (PUMP) and an interoperability name through Uniswap (UNI) and Hyperliquid (HYPE) down to Fetch.ai (FET) near the bottom. The negative end saw its only turnover of the month: Bitcoin Cash (BCH) dropped out of the bottom ten and Hedera (HBAR) took its place at the floor, while Zero (ZRO) eased from -0.60 to -0.42, its least negative reading of the rotation, trading places with Vet (VET) along the way. Pump's underlying value score also saw the sharpest re-rating in the long book this week, rising from 0.66 to 2.74, a sign of a genuine shift in its value characteristics rather than a beta drifting on price alone. A leader whose composition has not turned over even as its weekly return has cooled in each of the last two weeks reads as a maturing trade rather than an unwinding one; the earlier and larger any turnover shows up in this cohort, the sooner the leadership itself would be in question.
Downside Beta
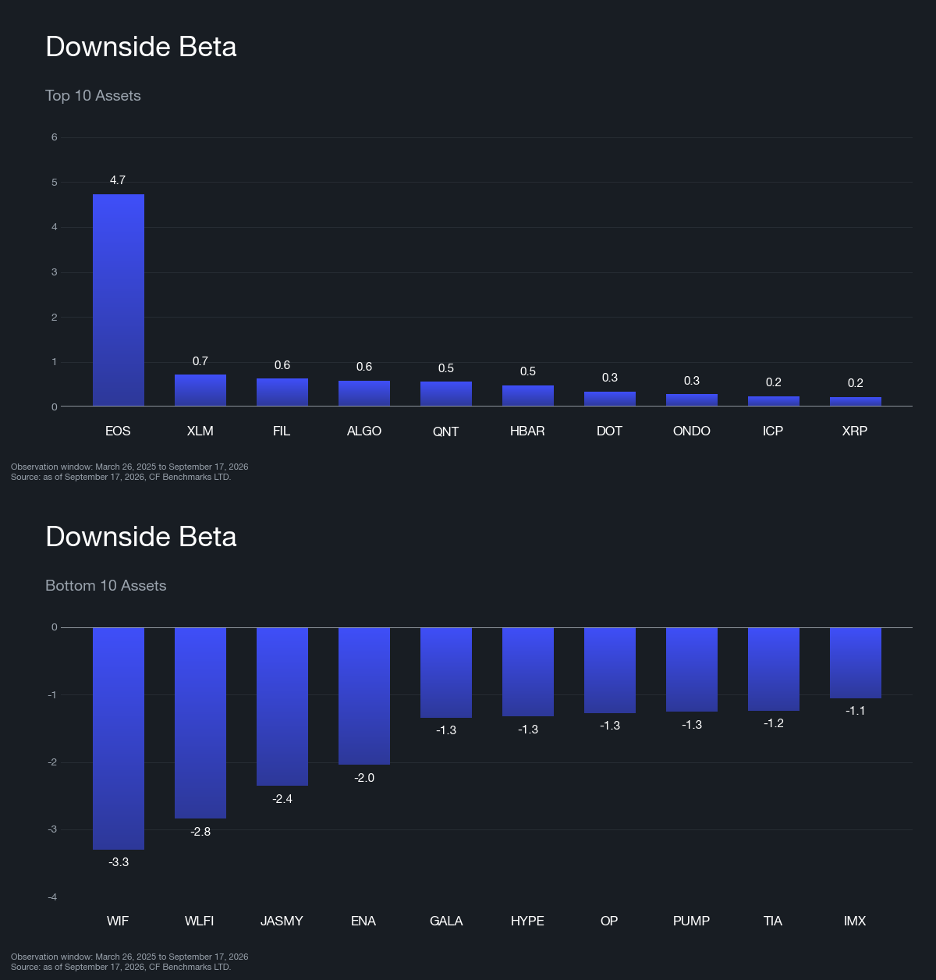
Downside Beta's fade continued into a third week, slipping from the 3.20% lead it held two weeks ago to a flat 0.05% last week and now to -0.80%, meaning the market is once again paying for exposure to its worst days rather than shelter from them. EOS still sits alone atop the high-beta list at 4.72, more than seven times the next name, Stellar (XLM) at 0.70, but underneath it Filecoin (FIL) climbed two spots to third as its beta rose from 0.44 to 0.61, and Ripple (XRP) entered the cohort for the first time this rotation, displacing TRUMP. The negative end saw a sharper move: Hyperliquid (HYPE) jumped three spots as its beta fell from -1.11 to -1.33, now more negatively exposed to drawdowns than Optimism (OP) and Celestia (TIA), both unchanged. Pump (PUMP), the same name behind this week's sharpest value re-rating, saw its downside-beta score fall further into short-book territory, from -0.35 to -1.60, the largest score move on either side of this factor's portfolio and a sign the market is pricing it as more differentiated risk on both fronts at once. With last week's flagged churn now showing up as a real repositioning rather than a one-off swap, and the factor's return itself turning negative, the defensive bid that led the table as recently as two weeks ago looks to be unwinding, not merely pausing; a fourth straight week of decay would confirm the reversal.
What Factors are Driving Markets
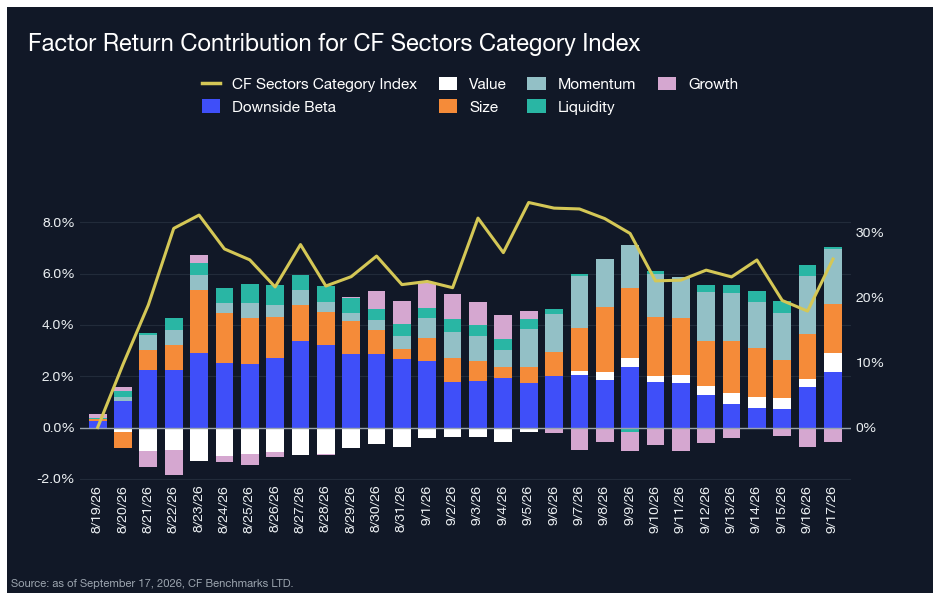
Factor contributions across the CF DACS Sectors universe total 6.45% over the trailing 30 days, against an index return of 25.89%, leaving the index 19.45 percentage points (pp) ahead of the factor sleeve, essentially unchanged from the 19.49 pp gap a week earlier even as the index itself rose from 24.85% to 25.89%. Downside Beta (2.18%) and Momentum (2.14%) lead, with Size (1.95%) close behind and Growth (-0.58%) the lone drag. A gap that has held steady for two straight weeks, even as the leading contributor rotates beneath it, says Sectors performance is still driven mostly by forces this factor set does not capture. Sectors' own return this week was concentrated, not broad-based: Uniswap (UNI) led every constituent at 25.46%, 22.80 pp above the category's 2.65% weekly return, while Morpho (MORPHO) lagged furthest at -3.68%.
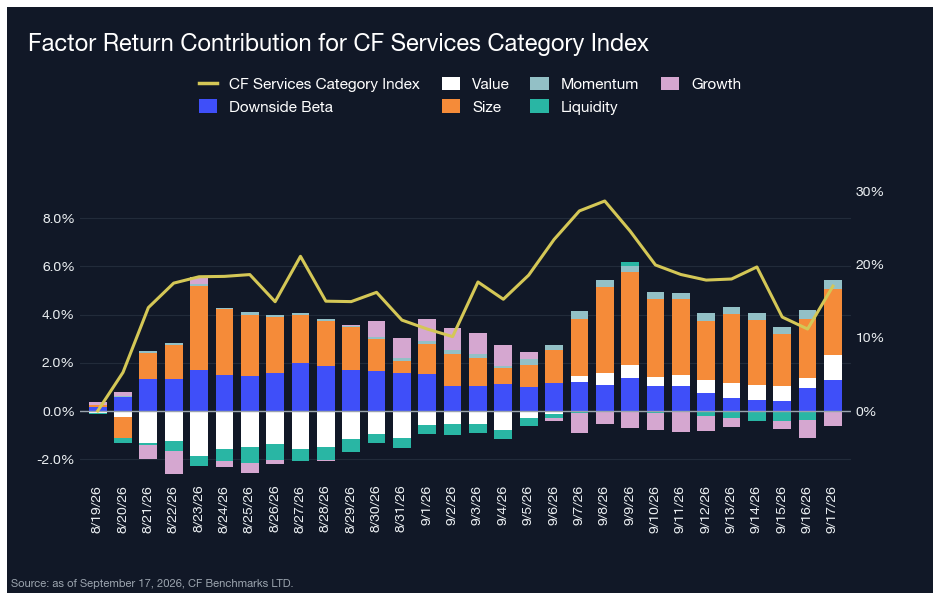
In the CF DACS Services universe, factor contributions total 4.80% against an index return of 17.10%, a 12.29 pp gap that has narrowed sharply from 26.96 pp a week earlier as the index itself cooled hard, from 30.20% to 17.10%. Size remains the clear leading contributor at 2.76%, with Downside Beta adding a further 1.28%, while Growth (-0.56%) is again the largest drag. The gap's sharp narrowing traces almost entirely to the index side; the factor sleeve barely moved, so Services still looks like an index-led category rather than one where selection is doing more work. Polygon (POL) led the category's own weekly return at 5.24%, 7.55 pp above the -2.31% category average, while Quant (QNT) trailed furthest at -6.75%.
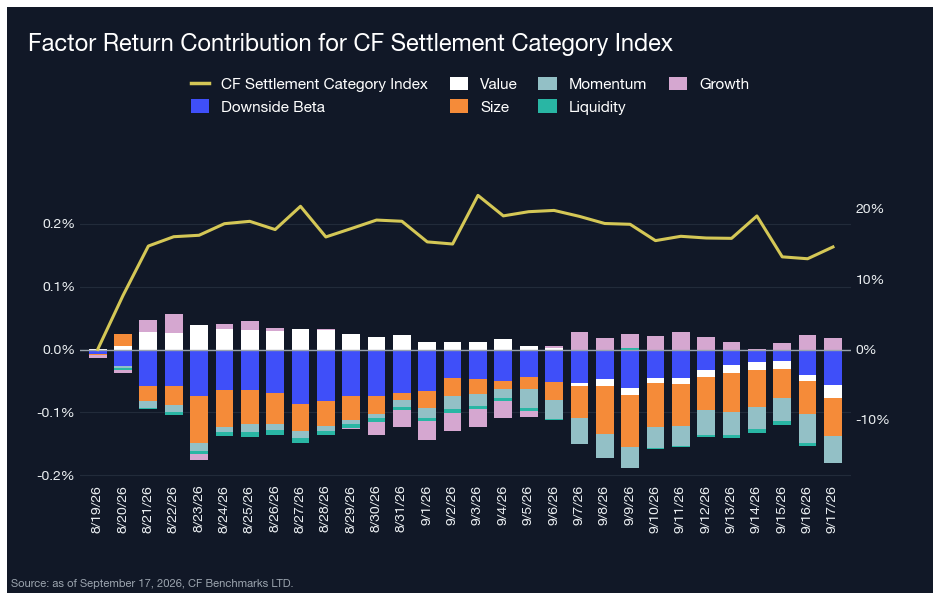
The Settlement universe, dominated by Bitcoin, again carries the clearest index-level signal of the three. Factor contributions are effectively flat, totaling -0.16% over the trailing 30 days, while the index returned 14.57%, a 14.73 pp gap that has narrowed from 24.36 pp the week before, again almost entirely because the index cooled, this time from 24.24% to 14.57%. No single factor contributed more than a few hundredths of a percentage point in either direction, so the month's advance sits almost entirely outside the systematic style basket, exactly as it did last week. Settlement's return continues to reflect forces the factor set simply does not capture, and that has now held for three straight weeks running. Near (NEAR) was the one outlier in the category's own weekly return, gaining 20.97% against Settlement's -0.74% average, a gap of 21.70 pp; every other constituent, Bitcoin included, stayed within a tighter band around that average.
Appendix: CF Factor Methodology
Market Factor
The market factor captures the broad, systematic risk that permeates the digital asset ecosystem. It reflects aggregate influences such as macroeconomic conditions, investor sentiment, and overall market volatility. As such, this factor is defined by the daily returns of the CF Broad Cap (Free Float Market Cap Weight) Index, offering a comprehensive and capitalization-weighted representation of the asset class.
Size Factor
The size factor captures the return differential associated with asset scale, reflecting the hypothesis that smaller-cap digital assets tend to outperform their larger-cap counterparts. This effect is understood to compensate for elevated operational and financial risks while exploiting potential market inefficiencies. In this framework, the size factor is defined by each asset’s fully diluted market capitalization. The value is sign-inverted so that higher z-scores are assigned to smaller assets and vice-versa.
Value Factor
The value factor reflects a protocol’s ability to generate economic output relative to its capital base and market valuation, combining measures of both efficiency and user engagement. It is constructed as the average z-score of two key ratios: transaction fees relative to total value locked (Fees/TVL) and daily active users relative to market capitalization (DAU/MCap). This composite metric captures how productively a protocol utilizes its resources while also serving as a proxy for user-driven demand. A higher combined score indicates efficient resource utilization and strong user engagement.
Momentum Factor
The momentum factor captures short-term price persistence by identifying assets that have recently exhibited strong performance. It is computed as the average z-score of two metrics: the 2 weeks cumulative performance and the 2 weeks risk-adjusted cumulative performance. This approach aligns with established findings in traditional financial literature and demonstrates empirical relevance in digital assets, where price trends tend to exhibit momentum over short horizons.
Growth Factor
The growth factor captures the expansion of a protocol’s network activity and user adoption. In the context of digital assets, it reflects metrics such as fee generation and user engagement, which serve as indicators of increased platform utilization and operational scale. The factor is defined as the average z-score of 30-day fee growth and 30-day weekly active user growth, thereby identifying assets exhibiting consistent and measurable increases in underlying network usage.
Downside Beta
The downside beta factor captures an asset’s sensitivity to adverse market conditions by isolating its behavior during periods of negative market returns. Empirical evidence shows that assets with lower downside beta tend to outperform their higher-beta counterparts over the long-term, due to their reduced participation in market drawdowns and more stable return profiles during periods of elevated volatility. As such, it is estimated through a regression of the asset’s daily returns over the most recent four-week period against market returns observed exclusively during negative sessions. The resulting value is sign-inverted to ensure that assets with lower downside exposure are assigned higher z-scores.
Liquidity Factor
The liquidity factor captures the ease with which a digital asset can be traded without significantly impacting its price. Empirical evidence shows that illiquid assets tend to command a higher risk premium than their more liquid counterparts, serving as compensation for trading friction and price volatility. To quantify this, the factor is measured using token turnover, defined as trading volume as a percentage of circulating supply. The value is sign-inverted such that higher z-scores are assigned to less liquid assets.
For further detail, view the CF Factors Methodology Document, the CF Factor Data Suite, and Our paper “A Factor Model for Digital Assets” in Springer Nature’s Mathematical Research for Blockchain Economy.
The information contained within is for educational and informational purposes ONLY. It is not intended nor should it be considered an invitation or inducement to buy or sell any of the underlying instruments cited including but not limited to cryptoassets, financial instruments or any instruments that reference any index provided by CF Benchmarks Ltd. This communication is not intended to persuade or incite you to buy or sell security or securities noted within. Any commentary provided is the opinion of the author and should not be considered a personalised recommendation. Please contact your financial adviser or professional before making an investment decision.
Note: Some of the underlying instruments cited within this material may be restricted to certain customer categories in certain jurisdictions.
Factor Friday - September 18, 2026
Value led CF Benchmarks' factor table for a third straight week at 1.85%, even as its pace cooled. Growth flipped positive while Downside Beta turned negative for the first time in three weeks, and the Market's decline eased sharply to 0.70% from last week's near-5% drop.
Mark Pilipczuk
Changes to the Token Market Price Benchmarks Series - Market Prices – 15 September 2026
The Administrator has confirmed changes to the Token Market Price Family for the period 08 September 2026 to 15 September 2026
CF Benchmarks
Emerging Leaders, Established Activity
The CME CF Emerging Crypto Index provides rules-based exposure beyond Bitcoin and Ether, capturing networks that account for most observed protocol fees and user activity while applying the institutional standards required for a credible benchmark.
CF Benchmarks
By clicking Accept, you consent to CF Benchmarks's use of cookies.
Visit Cookie Settings to learn how CF Benchmarks uses cookies and to adjust your preferences.