
Oct 09, 2026
Factor Friday - October 9, 2026
Size Holds the Lead As the Market Falls
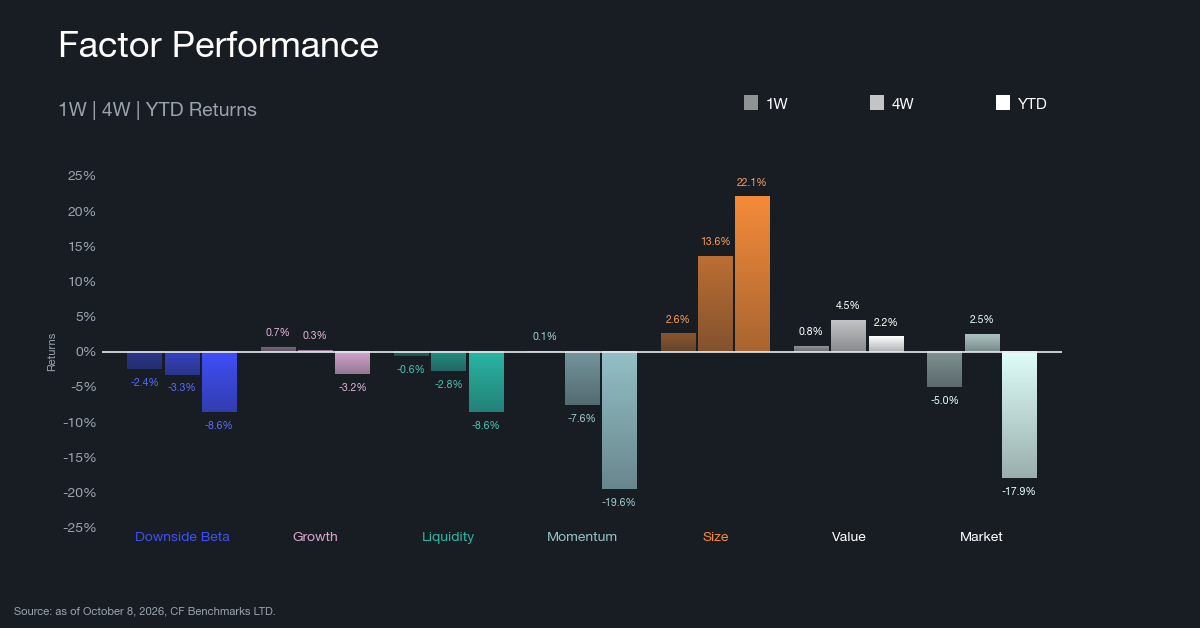
Size held the top of the factor table for a second week at 2.58% while the Market fell 4.98% to finish last. Value (0.79%) and Growth (0.70%) closed modestly higher, Momentum edged up 0.08%, and Liquidity (-0.62%) and Downside Beta (-2.44%) reversed part of last week's gains. Over four weeks Size leads at 13.65%, ahead of Value (4.49%) and the Market (2.53%), with Momentum (-7.58%) last. Year to date, Size extended its lead to 22.09% from 19.01% a week earlier, Value held positive at 2.15%, and Momentum (-19.55%) and the Market (-17.92%) are the two weakest. The selling was broad. The median CF Broad Cap constituent fell 8.68%, only 2 of 35 closed higher, and Bitcoin (BTC), down 3.61%, cushioned the cap-weighted Market. Because Size is a long-short factor, a positive print here means smaller assets lost less than larger ones. Last week's report asked whether Size would hold once Quant (QNT) cooled. QNT fell 9.58% and Size still led, though the spread behind it leans on a few tokens. For investors, the signal to watch is whether smaller assets keep outperforming if large caps stabilize, since that would confirm a broad bias down the market cap curve rather than a defensive reshuffle.
Rolling Factor Rankings and Rotation
The order beneath Size reshuffled almost completely. Value rose from fifth to second at 0.79%, Growth from fourth to third at 0.70%, and Momentum from last to fourth as a 5.80% loss last week became a 0.08% gain. Liquidity slipped from third to fifth after 4.61% last week, Downside Beta fell from second to sixth as 5.59% turned into -2.44%, and the Market dropped from sixth to last at -4.98%, following a flat 0.07% last week and 11.70% the week before. Last week's report cautioned that the sign-inverted factors holding the top three places leaned heavily on QNT. With QNT down 9.58%, two of the three retreated and only Size stayed ahead. Month to date, Size leads at 2.15%, ahead of Value (1.22%) and Growth (1.21%), with the Market last at -4.18%. The Market's four-week return of 2.53% still ranks third, but it now rests on the 11.70% gain from two weeks ago. If large caps rebound faster than the rest of the market, Size would give back gains, because the factor is long smaller assets and short larger ones by construction.
Market and Key Factor Betas
Market Beta
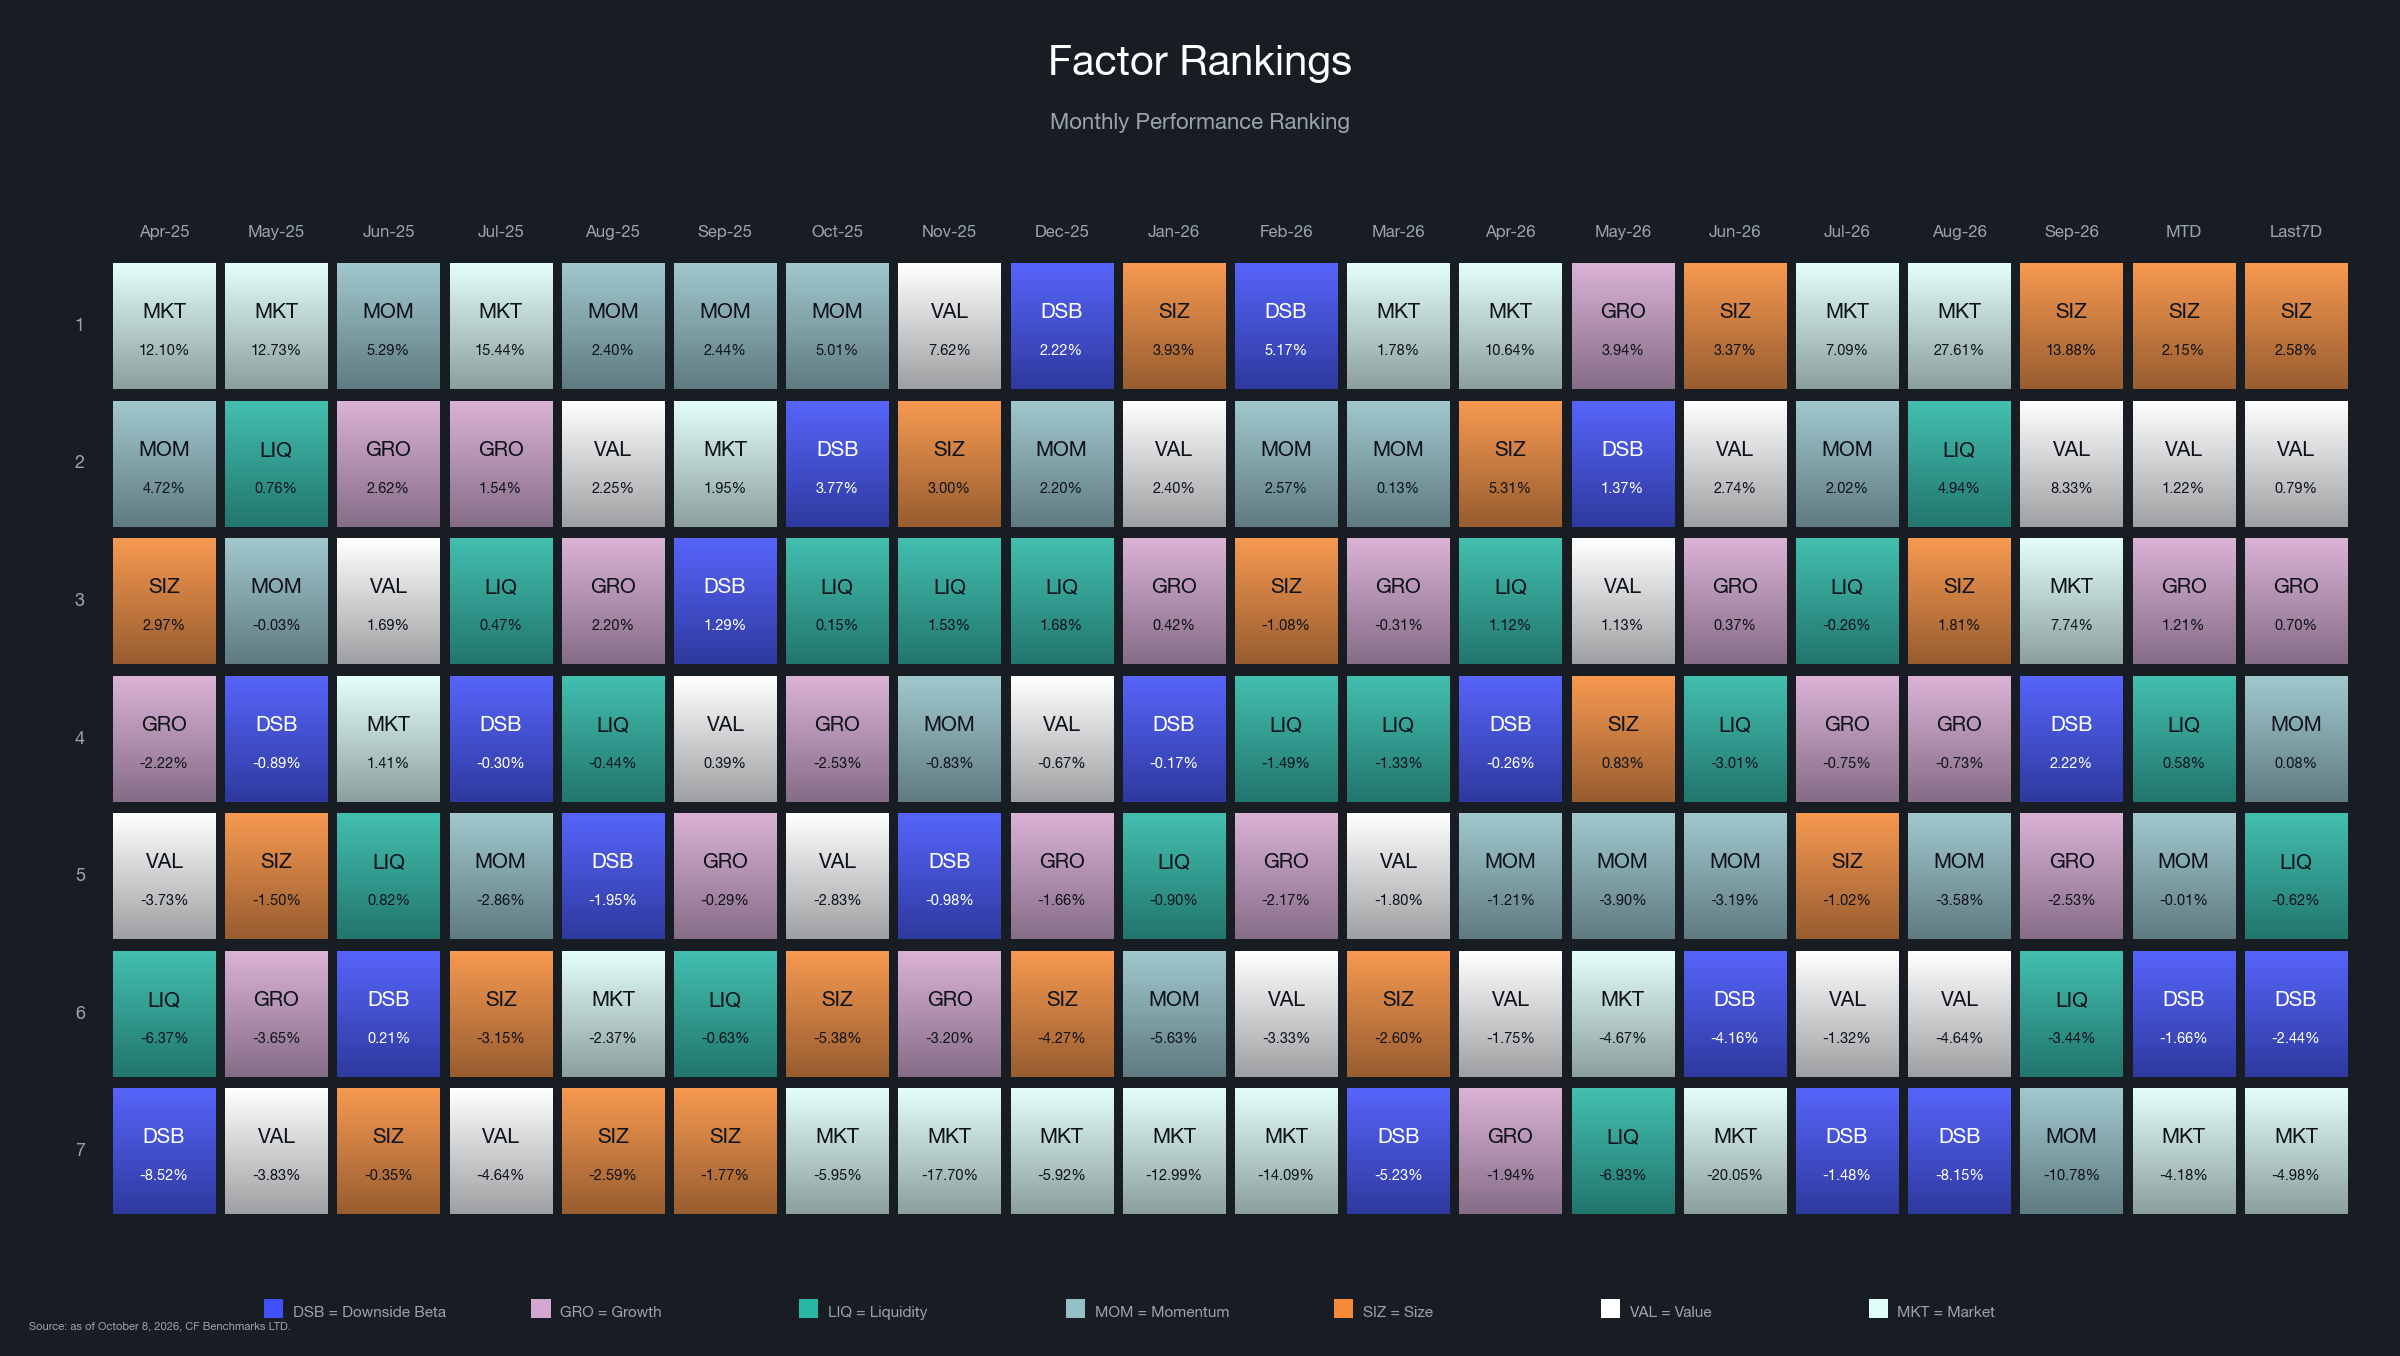
Broad beta lost 4.98% and the selling reached nearly every constituent. The median CF Broad Cap token fell 8.68% against a gain of 1.85% last week, and only 2 of 35 finished higher where 22 did a week ago. Bitcoin's 3.61% decline, from a market beta of 0.89, held the cap-weighted Market well above the typical token. The high market-beta roster kept the same ten names, a mix of meme-linked tokens, DeFi protocols, AI compute and real-world-asset names and alternative layer-1 platforms, with only the order shifting. The low-beta ten is also unchanged, and its newest members moved up toward the pack as their regression windows filled. Venice (VVV) rose from 0.50 to 0.95 and Toncoin (TON) from 0.53 to 0.75, with Morpho (MORPHO) also rising from 0.79 to 1.02. The ten highest market-beta names returned an average -8.58% against -8.89% for the ten lowest, a gap of 0.3 percentage points (pp) that runs marginally against a falling Market. Excluding QNT, which sat in the lowest ten, the gap is 0.2 pp, against a lead of 11.7 pp for the high-beta group a week ago on the same basis. Beta did not sort the losers, which is less surprising given how compressed the range is. The low-beta ten sit between roughly 0.75 and 1.1 and the high-beta ten between 1.4 and 1.6, so the two groups differ less in market exposure than the labels suggest. Uniswap (UNI, -20.21%) and Ethena (ENA, -16.74%), the two weakest tokens in the universe, both sit in the high-beta ten, while Ondo (ONDO) and Aave (AAVE) in the same group lost less than 2%. That puts the dispersion inside the cohort at 19.7 pp, wide enough that a market-beta tilt did little to predict which holdings suffered. A sell-off this broad across constituents but this uneven in size means broad beta exposure alone offered little protection.
Size
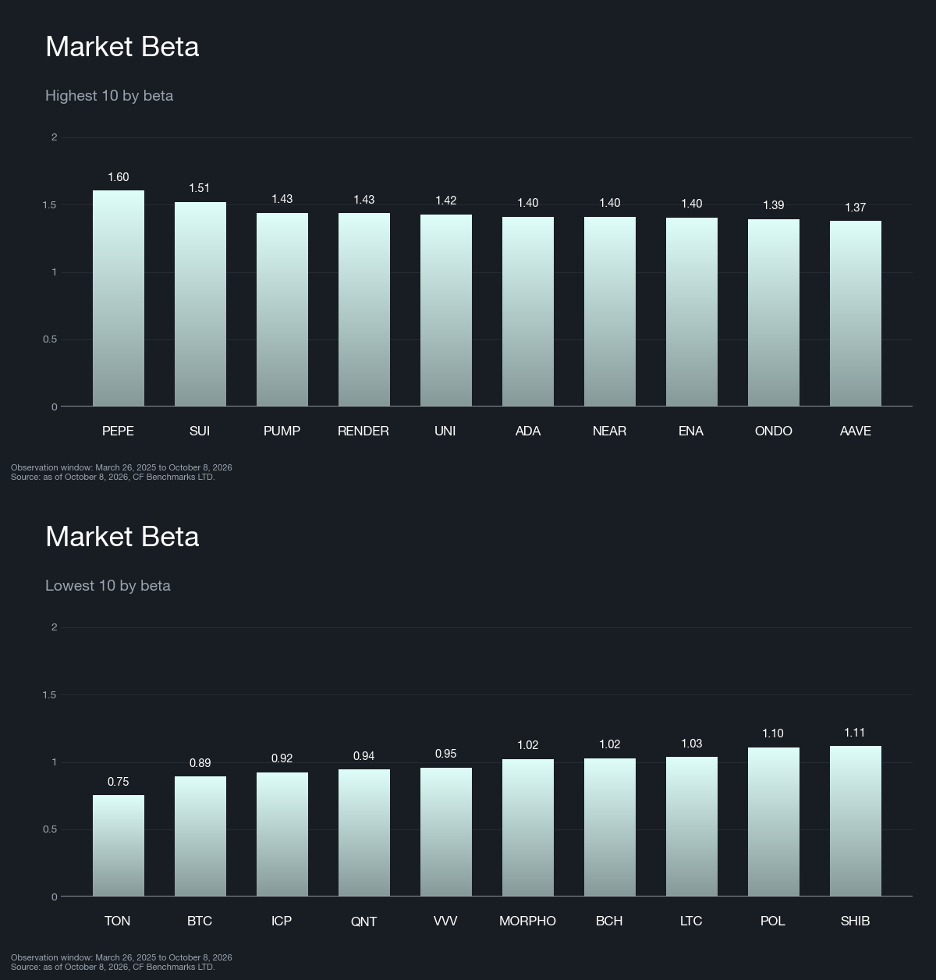
Size rose 2.58% and leads the table on every horizon shown. The factor is sign-inverted, so a positive print means smaller assets outperformed larger ones. In a week when 33 of 35 constituents fell, that means smaller names lost less. The ten highest size-beta names returned an average -4.92% against -9.29% for the ten lowest, a 4.4 pp spread in favor of smaller caps, and it does not hinge on QNT. Excluding QNT the cohort averages -4.40%, a spread of 4.9 pp, compared with 8.5 pp a week ago on the same excluding-QNT basis. Concentration is the caveat, and it runs through both ends of the cohorts. LayerZero (ZRO, 10.38%) and Filecoin (FIL, 2.85%) were the only two Broad Cap tokens to rise, and both sit in the high size-beta ten. Without them the cohort averages -7.80%. The low end has its own outlier. UNI, the weakest token in the universe at -20.21%, carries the most negative size beta, and excluding it lifts the low-beta cohort to -8.08%. Removing ZRO, FIL and UNI together leaves a spread of 0.3 pp, although the spread between the two cohorts' medians, which single tokens move less, is 4.5 pp. QNT kept the top spot with a beta of 3.00, down from 3.19, with FIL close behind and Worldcoin (WLD) third, and the cohort is still drawn from storage, AI compute, interoperability and DeFi tokens. VVV entered at 1.76 as Polygon (POL) left. The opposite end is unchanged. UNI sits at the bottom of it, followed mainly by the largest networks and payment chains, including Bitcoin, Ether (ETH), Solana (SOL) and XRP. Size scores barely moved because they track market capitalization, and the only side changes were ENA, which joined the long side, and Shiba Inu (SHIB), which joined the short side. Both sit at about 0.22, the line between the two sides rather than zero, so a short-side name can carry a positive score. This week's Size return therefore reflects price action, with only two of 35 names switching sides in the portfolio behind it. How broad the bid down the market cap curve really is sits between the 0.3 pp spread with the three outliers removed and the 4.5 pp spread between medians.
Liquidity
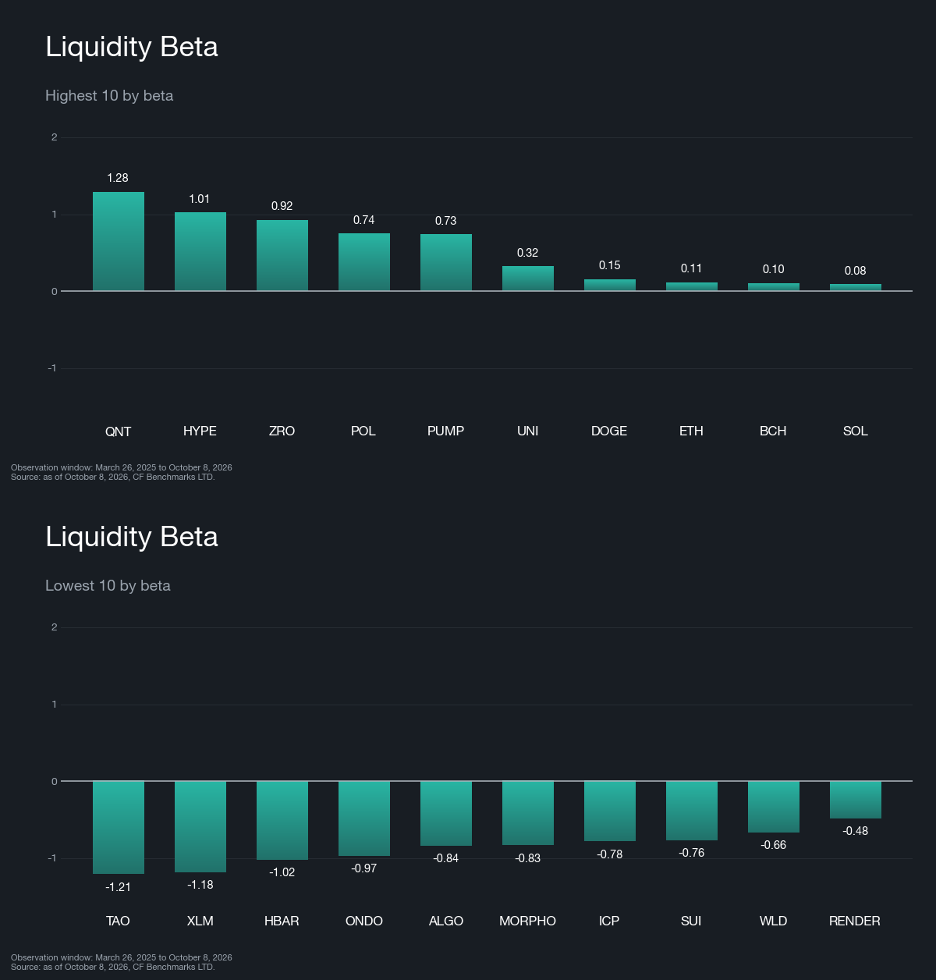
Liquidity fell 0.62%, finishing fifth after a 4.61% gain last week and widening its four-week loss to 2.80% from 0.40%. Because the factor is sign-inverted, a negative print means more liquid tokens edged out less liquid ones. The beta cohorts do not explain the move. The ten highest liquidity-beta names returned an average -7.42% against -7.52% for the ten lowest, a 0.1 pp gap that runs marginally against the factor, compared with a 21.2 pp gap last week (26.03% against 4.84%). Excluding ZRO, the one riser among the highest ten, that cohort averaged -9.39%, 1.9 pp behind the lowest ten, which is the direction the print implies. The high-beta list is effectively five names, made up of two interoperability tokens, a perpetuals exchange token, a scaling network and a meme-coin launchpad, after which betas fall to 0.32 and below. Bitcoin Cash (BCH) and SOL entered that tail as FIL and SHIB left, which says little given betas near zero. The low end is the same ten names, led by an AI network token and a payments chain at betas near -1.2, with MORPHO easing from -1.17 to -0.83 as its window fills. The sharpest score swings sit with the top of the list. ZRO's liquidity score fell from 0.28 to -2.98, moving it from the less liquid long side of the portfolio to the more liquid short side, consistent with a jump in turnover alongside its 10.38% gain, the best in the universe. QNT's score rose 3.25 points, from -5.05 to -1.80, a move toward the less liquid side that is consistent with turnover cooling after last week's 200% rally, though it remains on the short side. The two tokens most tied to the factor's recent moves have shifted in opposite directions, ZRO toward the more heavily traded side and QNT back toward the less liquid end, so a Liquidity print currently reflects a handful of names. If a flight to liquidity were under way, the high-beta cohort would lag by a wide margin. This week it finished marginally ahead, and it lagged only once ZRO is removed.
What Factors are Driving Markets
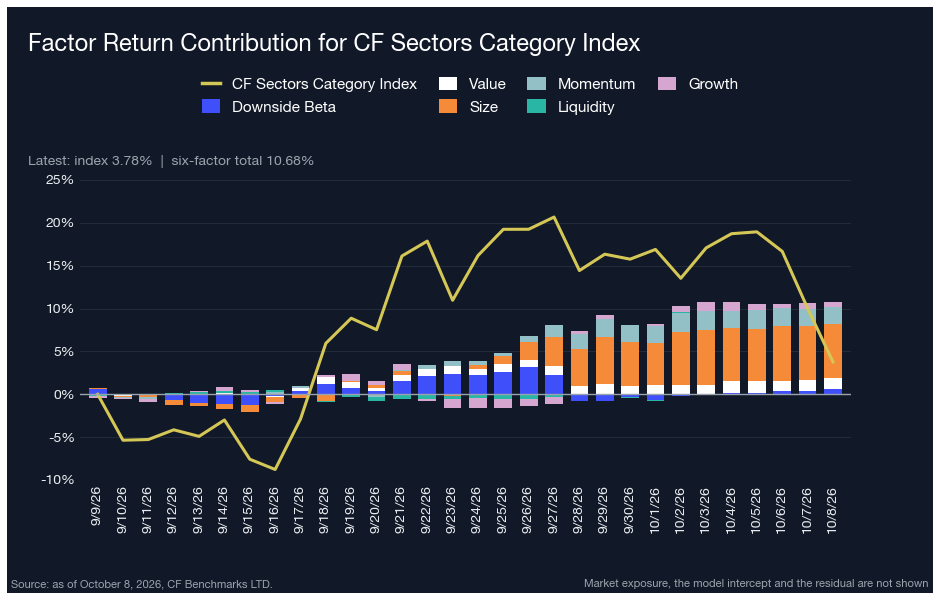
Factor contributions across the CF DACS Sectors universe total 10.68% over the trailing 30 days against an index return of 3.78%, so factors now exceed the index by 6.9 pp, a reversal from last week, when the index led by 16.4 pp. The index fell from 24.79%, but only 13.1 pp of that 21.0 pp decline is this week's move. The other 7.9 pp is early-September gains rolling out of the 30-day window. The factor sleeve rose from 8.40% to 10.68%, a 3.2 pp gain this week after the roll took off 0.9 pp. Size (6.26%) remains the dominant contributor, followed by Momentum (1.99%) and Value (1.30%), with Downside Beta (0.61%) and Growth (0.59%) turning positive from last week's drags and Liquidity (-0.07%) the only negative. The index lost 11.38% on the week, with Dogecoin (DOGE), at 44.97% of the weight, down 11.80% and UNI, at 13.02%, down 20.21%. ONDO (-0.54%) led, 10.8 pp ahead of the index, with AAVE (-1.61%) 9.8 pp ahead, while UNI trailed by 8.8 pp and ENA by 5.4 pp. The six factors shown leave out Market exposure, which the model also includes along with an intercept and a token-specific residual. Market exposure added 4.31% over the window, while the intercept and residual together subtracted 12.9 pp, so the index sits below the factor sleeve because of what neither Market nor the six style factors explain.
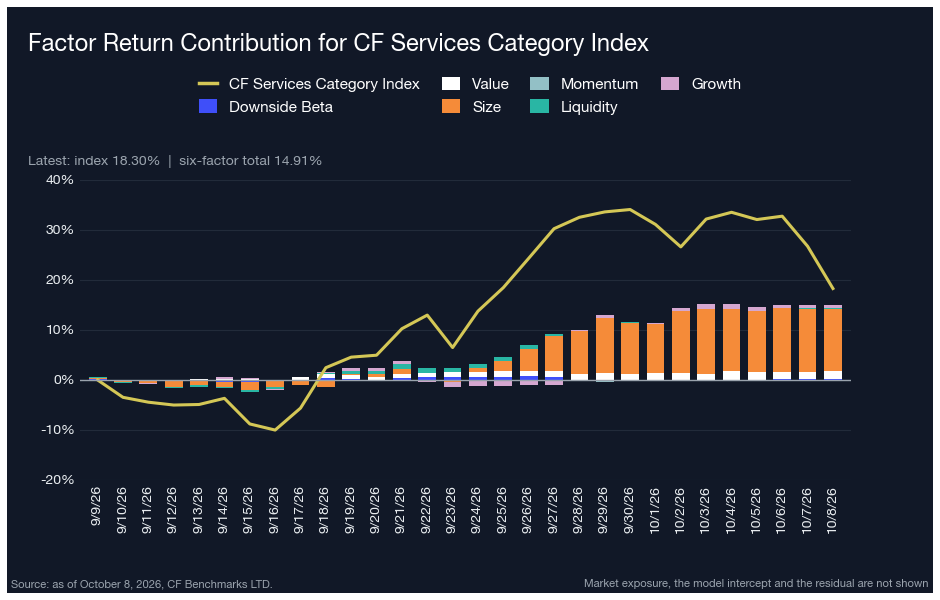
In the CF DACS Services universe, factor contributions total 14.91% against an index return of 18.30%, a 3.4 pp gap that narrowed sharply from 34.4 pp. Size accounts for almost the entire sleeve at 12.54%, with Value adding 1.57% and Momentum (-0.10%) the only drag. The index fell 10.01% on the week, with Chainlink (LINK), at 41.83% of the weight, down 13.48% and QNT, at 14.01%, down 9.58%. Last week's report noted that a QNT reversal would reach the index before it reached the Size contribution. The 30-day index return fell by 29.9 pp, from 48.21% to 18.30%, but 17.1 pp of that is early-September gains rolling out of the window and 12.8 pp is this week's move. On the same like-for-like basis the Size contribution rose 2.7 pp, so the decline reached the index and not the sleeve, although QNT accounts for only about 1.3 pp of the index's weekly fall against about 5.9 pp for LINK. ZRO led at 10.38%, 20.4 pp ahead of the index, and no constituent trailed by more than 4.4 pp, with VVV the weakest at -14.41%. The six style factors now equal about 81% of the 30-day index return, up from 29%, although part of that move is the window roll and the model's Market exposure, which added 4.28% over the window, is not in the sleeve. That leaves Size as the exposure to watch.
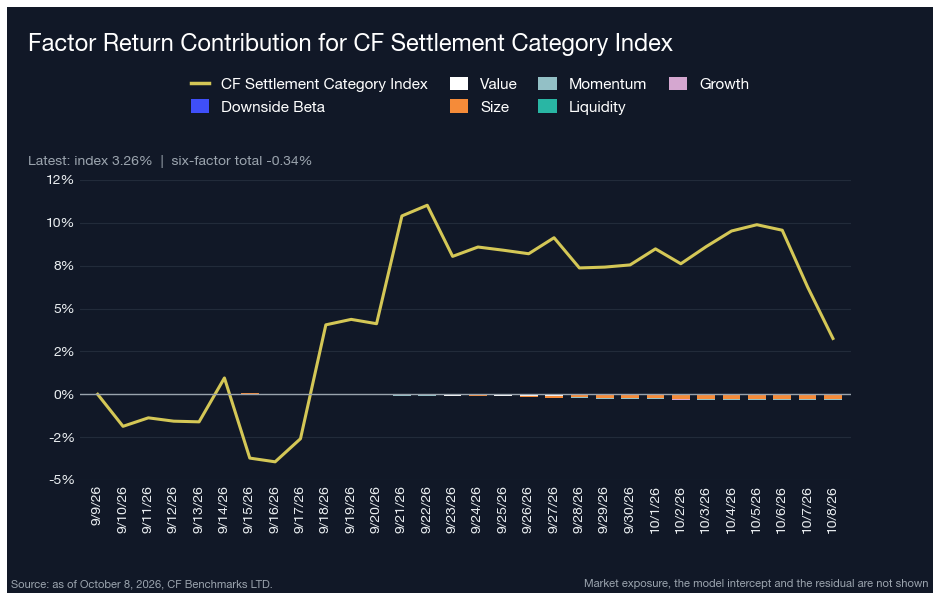
The Settlement universe, dominated by Bitcoin, still shows the weakest link to the style factors, which is expected because Market exposure sits outside the set and Bitcoin is about 74% of the index. Factor contributions total -0.34% against an index return of 3.26%, a 3.6 pp gap that narrowed from 11.2 pp, and Size (-0.23%) was the only factor to contribute more than 0.04 pp in either direction. Market exposure alone contributed 3.18% over the window, nearly all of the index return. The index fell 4.82% on the week, with Bitcoin (-3.61%, 74.21% of the weight) holding up better than ETH (-8.97%, 11.34%) and XRP (-8.68%, 4.95%). Bitcoin was the top performer, 1.2 pp ahead of the index, while Stellar (XLM, -13.26%) was the weakest, 8.4 pp behind on a 0.32% weight, and Sui (SUI) and Hedera (HBAR) also trailed by 6.8 and 6.0 pp. The gap narrowed because the index return fell while the style-factor sleeve stayed near zero, which makes Settlement a read on Bitcoin and Market exposure more than on the style factors.
Appendix: CF Factor Methodology
Market Factor
The market factor captures the broad, systematic risk that permeates the digital asset ecosystem. It reflects aggregate influences such as macroeconomic conditions, investor sentiment, and overall market volatility. As such, this factor is defined by the daily returns of the CF Broad Cap (Free Float Market Cap Weight) Index, offering a comprehensive and capitalization-weighted representation of the asset class.
Size Factor
The size factor captures the return differential associated with asset scale, reflecting the hypothesis that smaller-cap digital assets tend to outperform their larger-cap counterparts. This effect is understood to compensate for elevated operational and financial risks while exploiting potential market inefficiencies. In this framework, the size factor is defined by each asset’s fully diluted market capitalization. The value is sign-inverted so that higher z-scores are assigned to smaller assets and vice-versa.
Value Factor
The value factor reflects a protocol’s ability to generate economic output relative to its capital base and market valuation, combining measures of both efficiency and user engagement. It is constructed as the average z-score of two key ratios: transaction fees relative to total value locked (Fees/TVL) and daily active users relative to market capitalization (DAU/MCap). This composite metric captures how productively a protocol utilizes its resources while also serving as a proxy for user-driven demand. A higher combined score indicates efficient resource utilization and strong user engagement.
Momentum Factor
The momentum factor captures short-term price persistence by identifying assets that have recently exhibited strong performance. It is computed as the average z-score of two metrics: the 2 weeks cumulative performance and the 2 weeks risk-adjusted cumulative performance. This approach aligns with established findings in traditional financial literature and demonstrates empirical relevance in digital assets, where price trends tend to exhibit momentum over short horizons.
Growth Factor
The growth factor captures the expansion of a protocol’s network activity and user adoption. In the context of digital assets, it reflects metrics such as fee generation and user engagement, which serve as indicators of increased platform utilization and operational scale. The factor is defined as the average z-score of 30-day fee growth and 30-day weekly active user growth, thereby identifying assets exhibiting consistent and measurable increases in underlying network usage.
Downside Beta
The downside beta factor captures an asset’s sensitivity to adverse market conditions by isolating its behavior during periods of negative market returns. Empirical evidence shows that assets with lower downside beta tend to outperform their higher-beta counterparts over the long-term, due to their reduced participation in market drawdowns and more stable return profiles during periods of elevated volatility. As such, it is estimated through a regression of the asset’s daily returns over the most recent four-week period against market returns observed exclusively during negative sessions. The resulting value is sign-inverted to ensure that assets with lower downside exposure are assigned higher z-scores.
Liquidity Factor
The liquidity factor captures the ease with which a digital asset can be traded without significantly impacting its price. Empirical evidence shows that illiquid assets tend to command a higher risk premium than their more liquid counterparts, serving as compensation for trading friction and price volatility. To quantify this, the factor is measured using token turnover, defined as trading volume as a percentage of circulating supply. The value is sign-inverted such that higher z-scores are assigned to less liquid assets.
For further detail, view the CF Factors Methodology Document, the CF Factor Data Suite, and Our paper “A Factor Model for Digital Assets” in Springer Nature’s Mathematical Research for Blockchain Economy.
The information contained within is for educational and informational purposes ONLY. It is not intended nor should it be considered an invitation or inducement to buy or sell any of the underlying instruments cited including but not limited to cryptoassets, financial instruments or any instruments that reference any index provided by CF Benchmarks Ltd. This communication is not intended to persuade or incite you to buy or sell security or securities noted within. Any commentary provided is the opinion of the author and should not be considered a personalised recommendation. Please contact your financial adviser or professional before making an investment decision.
Note: Some of the underlying instruments cited within this material may be restricted to certain customer categories in certain jurisdictions.
Factor Friday - October 9, 2026
Size led CF Benchmarks' factor table for a second week at 2.58% as the Market fell 4.98%. Size held after QNT's reversal, though its cohort spread narrows sharply without three outlier tokens, and Downside Beta and Liquidity gave back part of last week's gains.
Mark Pilipczuk
Small Cap Tokens Outperform in September
The CF Free-Float Broad Cap Index rose 10.28% in September as Bitcoin supplied 59% of the gain while trailing the index. Returns across the Capitalization Series ran from +7.74% for Ultra Cap 5 to +14.01% for Emerging Crypto, which holds no Bitcoin, as altcoins outpaced Bitcoin.
Mark Pilipczuk
CF Digital Asset Index Family Multi Asset Series – Extraordinary Rebalance Announcement
CF Digital Asset Index Family Multi Asset Series - Extraordinary Rebalance Announcement
CF Benchmarks
By clicking Accept, you consent to CF Benchmarks's use of cookies.
Visit Cookie Settings to learn how CF Benchmarks uses cookies and to adjust your preferences.