Oct 30, 2026
Factor Friday - October 30, 2026
Liquidity Leads as The Market Slides
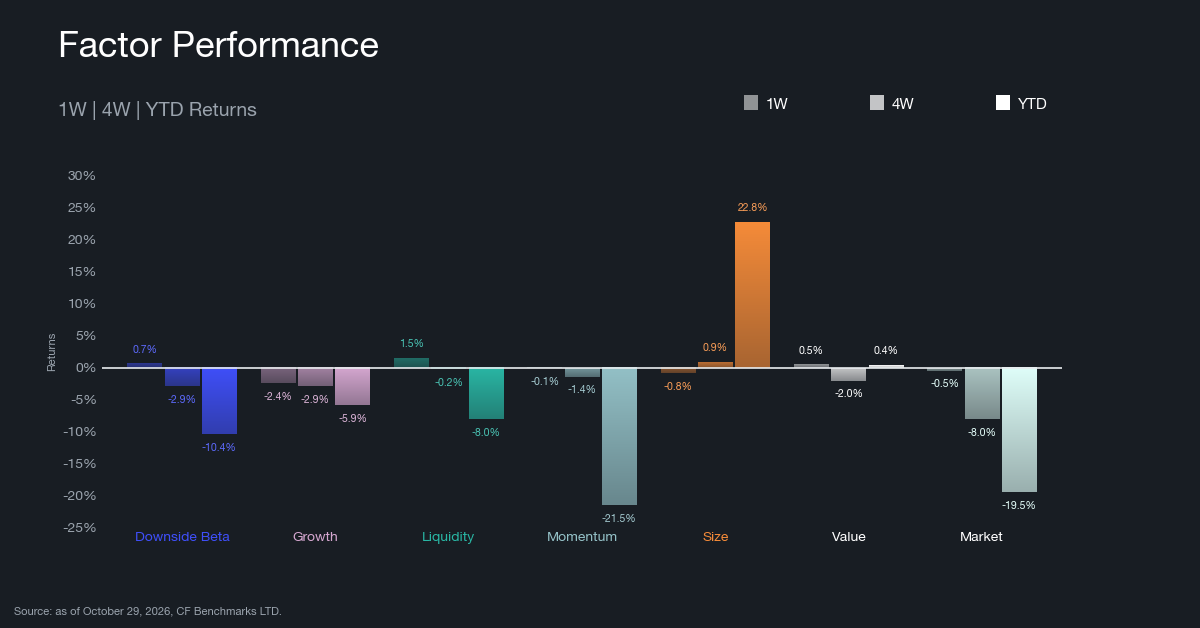
Liquidity led the factor table at 1.54% after a 1.03% loss last week, as less liquid assets outperformed more liquid ones. Downside Beta (0.68%) and Value (0.47%) were the only other gains, while Momentum (-0.08%), the Market (-0.46%), Size (-0.79%) and Growth (-2.39%) declined, ending Size's four-week run at the top. Over four weeks Size still leads at 0.88%, ahead of Liquidity (-0.19%), Momentum (-1.39%), Value (-2.01%), Downside Beta (-2.85%) and Growth (-2.90%), with the Market (-8.02%) last. Year to date Size leads at 22.76%, down from 23.74% a week earlier, Value has turned positive at 0.38%, and Growth (-5.86%), Liquidity (-7.99%) and Downside Beta (-10.41%) sit ahead of the Market (-19.51%) and Momentum (-21.49%). Breadth improved from a weak base, with 8 of 35 CF Broad Cap constituents closing higher against 4 a week ago, and the median constituent lost 3.18% after losing 5.27% the week before. Bitcoin (BTC) fell 0.69%, 2.5 percentage points (pp) ahead of the median. Because Liquidity is a long-short factor, a positive print means less liquid assets outperformed, and the ten highest liquidity-beta tokens beat the ten lowest by 10.4 pp, a gap that stays positive when the week's largest single moves are removed. Growth is the exposure to watch. It fell from second to last in one week, and its four-week return turned negative at -2.90% from 0.27%.
Rolling Factor Rankings and Rotation
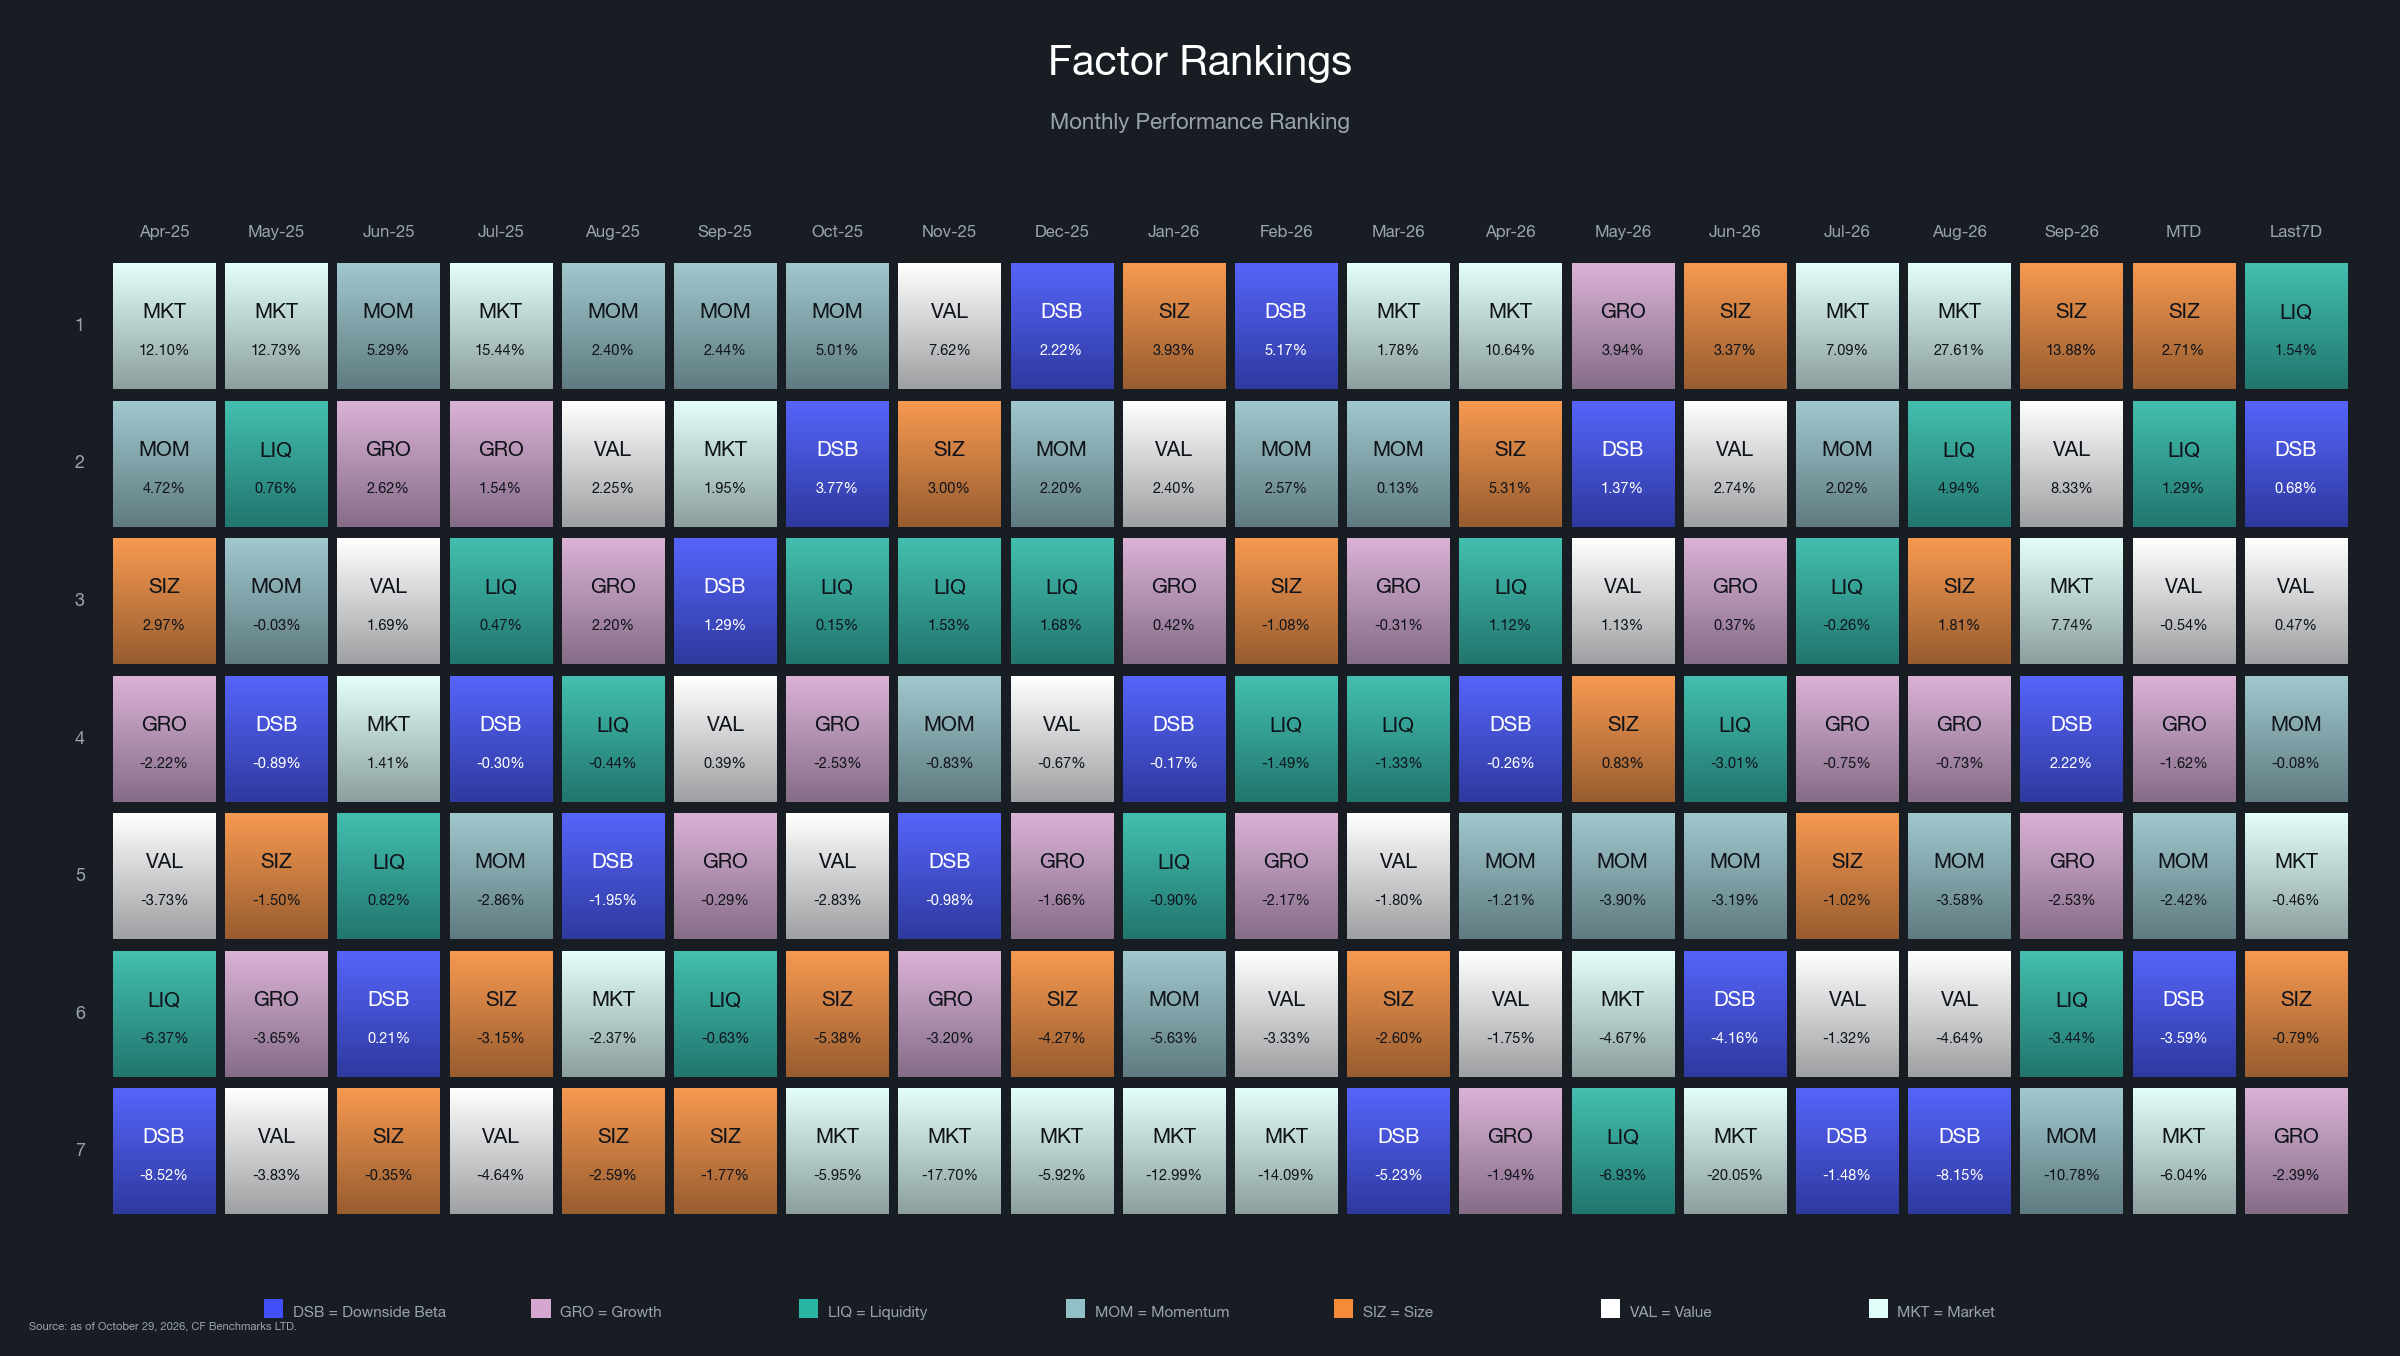
Liquidity moved from fifth to first on the weekly table at 1.54%, Downside Beta from fourth to second at 0.68% and Value from sixth to third at 0.47%. Momentum slipped from third to fourth at -0.08%, the Market rose from last to fifth at -0.46%, Size fell from first to sixth at -0.79%, and Growth dropped from second to last at -2.39%. Liquidity has now alternated sign for five straight weeks, at 4.61%, -0.62%, 0.22%, -1.03% and 1.54%, so a single week's lead says little about direction. Month to date Size still leads at 2.71%, down from 3.52%, followed by Liquidity (1.29%), Value (-0.54%) and Growth (-1.62%), while Momentum (-2.42%), Downside Beta (-3.59%) and the Market (-6.04%) trail. Liquidity rose from third to second on the month, and Growth fell from second to fourth. Much of the change in the four-week table is the window, as the days from September 29 to October 5 left it. Size's four-week return fell to 0.88% from 5.26%, a 4.4 pp decline against a 0.79% loss on the week, and the Market's fell to -8.02% from -5.42% despite a 0.46% weekly loss. Size is still first on the four-week, month-to-date and year-to-date tables and is now the only factor with a positive four-week return, but its weekly prints for the five weeks to October 29 have run 8.86%, 2.58%, 0.59%, 0.75% and -0.79%, so the lead rests on gains made around the turn of the month.
Market and Key Factor Betas
Market Beta
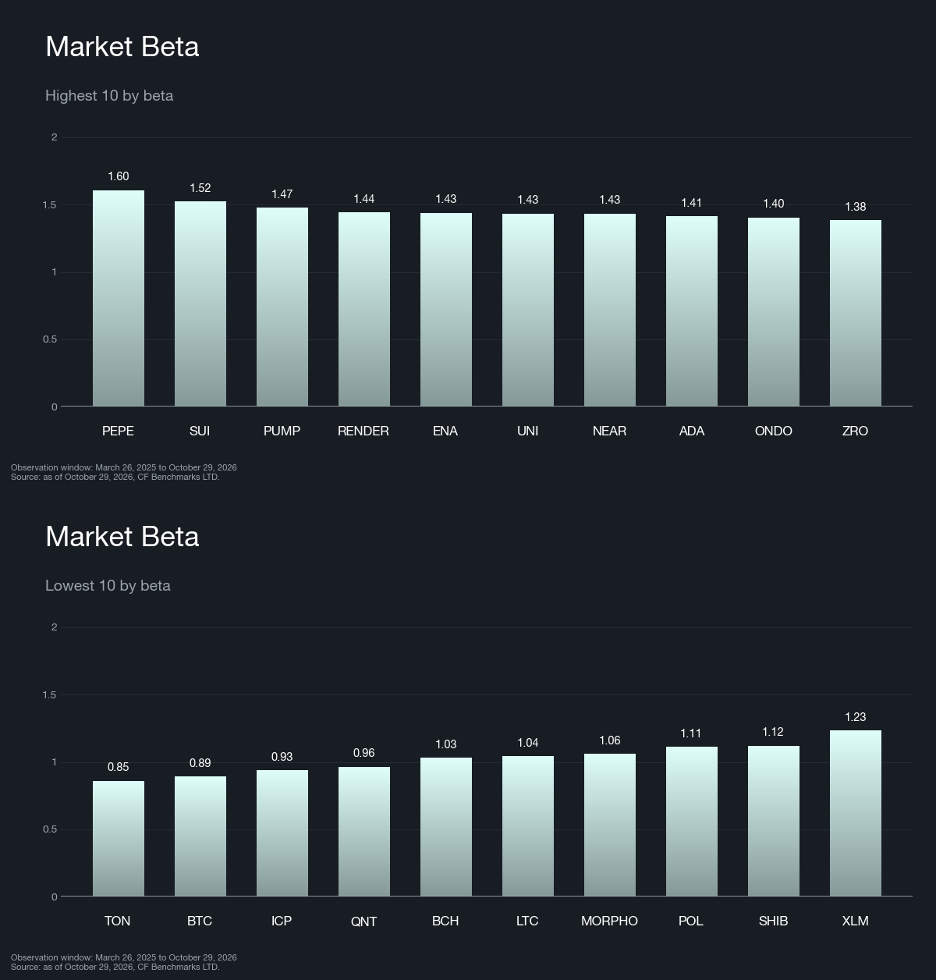
The Market fell 0.46%, a smaller loss than last week's 1.88%, and breadth improved, with 8 of 35 CF Broad Cap constituents finishing higher against 4 a week ago. The median constituent lost 3.18% compared with 5.27% last week, and BTC, at a market beta of 0.89, fell 0.69% to finish 0.2 pp behind the Market. Hyperliquid (HYPE, +21.23%) and Pepe (PEPE, +20.05%) led the constituents, while Worldcoin (WLD, -25.28%) fell furthest. The high market-beta roster changed by one name, with LayerZero (ZRO) entering at 1.38 as Aave (AAVE) left, and it remains a mix of meme-linked and launchpad tokens, DeFi protocols, AI compute and real-world-asset names and alternative layer-1 platforms, now with an interoperability token. The low-beta ten is unchanged, with Toncoin (TON) edging up from 0.83 to 0.85. The ten highest market-beta names returned an average -1.28% against -1.24% for the ten lowest, within 0.1 pp of each other, compared with a 0.4 pp gap that ran against a falling Market last week. The medians point the other way, at -4.67% and -0.73%, a gap of -3.9 pp that runs with the print. The average leans on PEPE, which sits at the top of the list at 1.60, and excluding it the ten highest average -3.65%, 2.4 pp below the lowest ten. Returns inside the high-beta cohort ranged 30.4 pp, from PEPE to NEAR Protocol (NEAR, -10.39%). With the low ten between 0.85 and 1.23 and the high ten between 1.38 and 1.60, beta was a useful guide only once PEPE is set aside, and on that basis higher-beta names lagged as the Market fell.
Liquidity
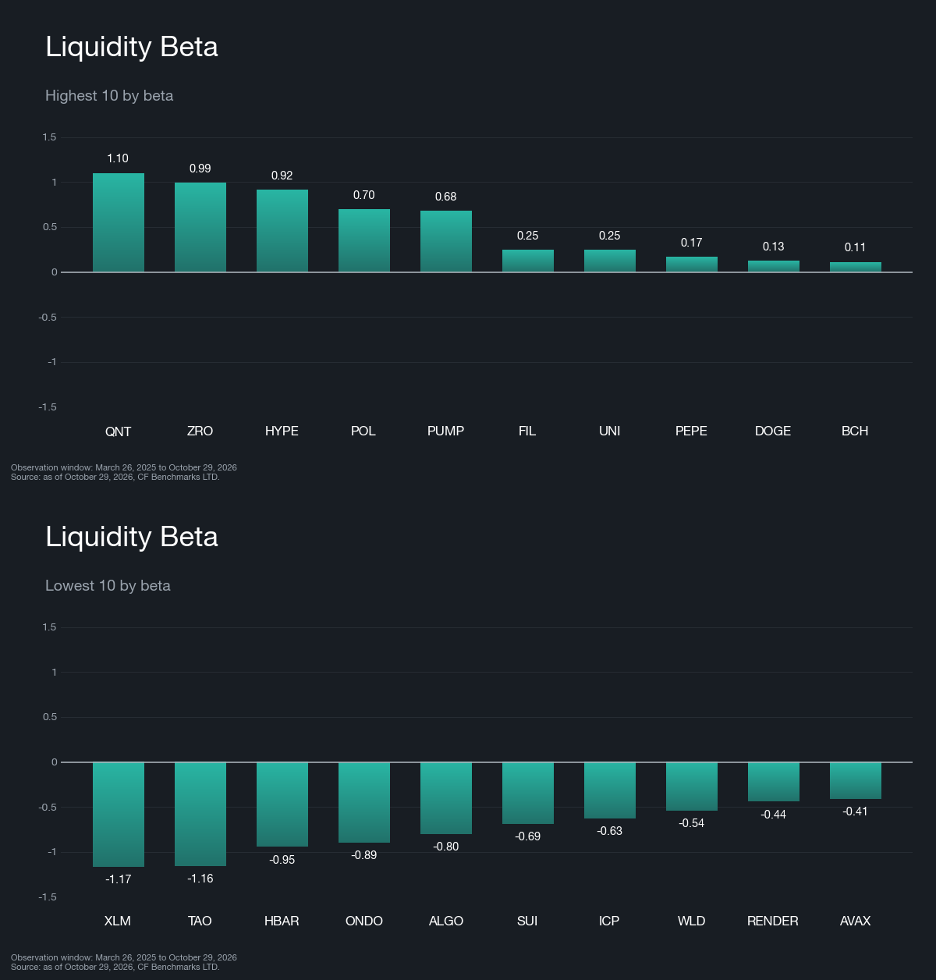
Liquidity gained 1.54% to rank first, up from fifth last week. The factor is sign-inverted, so a positive print means less liquid assets outperformed more liquid ones, the reverse of last week's 1.03% loss. Month to date Liquidity is 1.29%, up from -0.24%, and its four-week return improved to -0.19% from -1.20%. This time the beta cohorts confirm the print. The ten highest liquidity-beta names returned an average 3.52% against -6.92% for the ten lowest, a 10.4 pp gap in the factor's direction, and the medians (1.77% and -5.44%) are 7.2 pp apart in the same direction. Last week the cohorts ran against the print by 0.4 pp. Two tokens supply much of the average, with HYPE (+21.23%) and PEPE (+20.05%) both in the highest ten, and WLD (-25.28%) sits in the lowest. Excluding HYPE and PEPE, the highest ten average -0.76%, still 6.2 pp ahead of the lowest ten, and with WLD also excluded from the lowest ten, which then average -4.88%, the gap is 4.1 pp, so the cohorts run with the print under each cut. The highest ten mixes interoperability, perpetuals-exchange, scaling, meme-launchpad, storage and DeFi tokens with two meme coins and a payments chain at the low end, after Bitcoin Cash (BCH) entered at 0.11 and PEPE at 0.17 as Ethena (ENA) and Venice (VVV) left. ZRO's beta rose from 0.77 to 0.99 and Quant's (QNT) eased from 1.25 to 1.10. The lowest ten is unchanged, a group of payment and enterprise chains, layer-1 platforms, and AI, identity and real-world-asset tokens. Portfolio turnover was light. Uniswap (UNI) moved from the short to the long side at a score of 0.39 and Ether (ETH) moved the other way at 0.26, both close to the median split between the two sides. Pump.fun's (PUMP) score rose by 3.02, a move toward the less liquid side, while QNT's fell by 2.92 toward the more liquid side, and neither changed sides. Liquidity has alternated sign for five weeks, so a second positive week would be the first sign that the tilt toward less liquid tokens is holding.
Growth
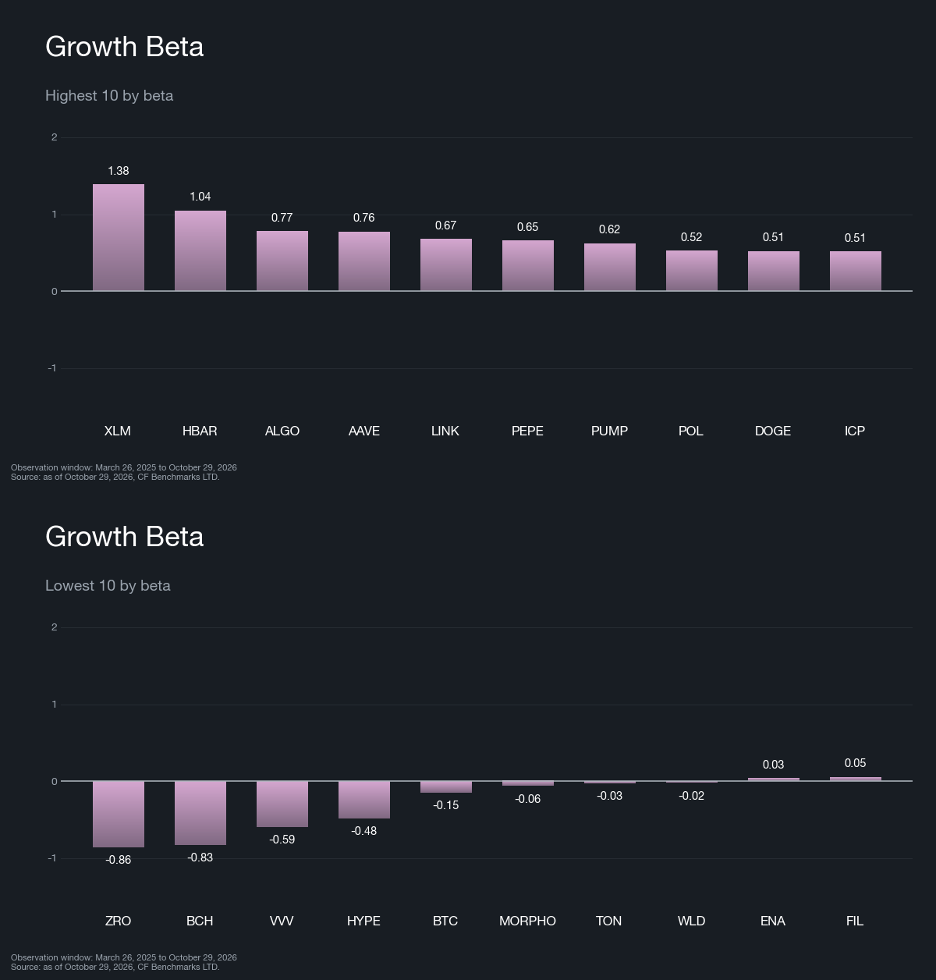
Growth fell 2.39% to rank last, down from second last week when it gained 0.49%. Its four-week return turned negative at -2.90% from 0.27%, and it is -1.62% month to date. The factor is not sign-inverted, so a negative print means tokens with stronger network activity and adoption trends underperformed those with weaker ones. The beta cohorts give a split answer. The ten highest growth-beta names returned an average -1.78% against -2.14% for the ten lowest, a 0.4 pp gap that runs against the print, while the medians (-4.23% and -2.62%) are 1.6 pp apart in the factor's direction. The average rests on one token. PEPE (+20.05%) sits in the highest ten, and excluding it the cohort averages -4.21%, 2.1 pp below the lowest ten. The lowest ten holds both of the week's extremes, HYPE (+21.23%) and WLD (-25.28%), and excluding the pair leaves that cohort at -2.17%, so with PEPE also out the high-beta names lag by 2.0 pp, in the factor's direction. The highest ten is drawn from payment and enterprise chains, layer-1 platforms, DeFi lending and oracle tokens, meme coins, a launchpad and a scaling network, with Internet Computer (ICP) entering at 0.51 as ETH left. The lowest ten mixes BTC and BCH with interoperability, perpetuals-exchange, AI, identity, DeFi, storage and layer-1 tokens, after ENA entered at 0.03 as Ondo (ONDO) left. Several low-end betas moved. HYPE's fell from about zero to -0.48 and VVV's from -0.15 to -0.59, while TON's rose from -0.36 to -0.03. Scores moved more than in Liquidity, with six names changing sides. WLD recorded the largest swing, from 3.95 to -0.95, moving from the long to the short side, and Hedera (HBAR) moved the other way, from -0.65 to 1.43. With the four-week return now below zero, Growth needs its long side to recover before the year-to-date deficit of 5.86% can narrow.
What Factors are Driving Markets
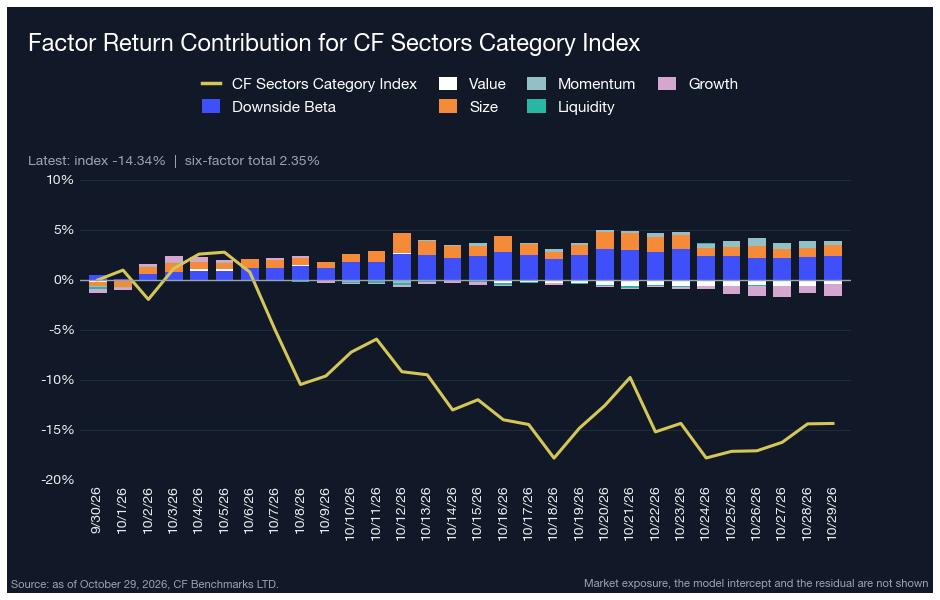
Across the CF DACS Sectors universe, factor contributions total 2.35% over the trailing 30 days against an index return of -14.34%, so the factors sit 16.7 pp above the index, compared with 20.6 pp above it last week as published. Both readings sit on a rolling window. The roll took 4.33 pp off the index and 5.73 pp off the six-factor sleeve, which accounts for 1.4 pp of the 3.9 pp narrowing in the gap, and this week's moves of 0.85 pp for the index and -1.67 pp for the sleeve account for the other 2.5 pp. Downside Beta (2.43%) is now the largest contributor, followed by Size (1.04%) and Momentum (0.47%), with Liquidity at zero, Value (-0.36%) a slight drag and Growth (-1.22%) the largest drag. Size was the dominant contributor last week at 7.05%, and the roll alone brought it to 1.47% as late-September gains left the window. The index gained 1.00% on the week while the Market fell. PEPE (+20.05%), at 5.93% of the weight at the start of the week, added about 1.2 pp, more than the whole index gain, and DOGE, at 44.71%, added about 0.3 pp on a 0.75% rise, while AAVE (-8.77%) took off about 0.6 pp and trailed the index by 9.8 pp. ENA (+4.55%) finished 3.6 pp ahead of the index. The six factors shown leave out Market exposure, which the model also includes along with an intercept and a token-specific residual. The Sectors model carries a Market beta of 1.35 with an R2 of 0.81, and of the index's -16.07% log return over the window, Market exposure accounts for about -8.2%, the intercept -3.3% and the residual -6.9%, against 2.35% for the six factors.
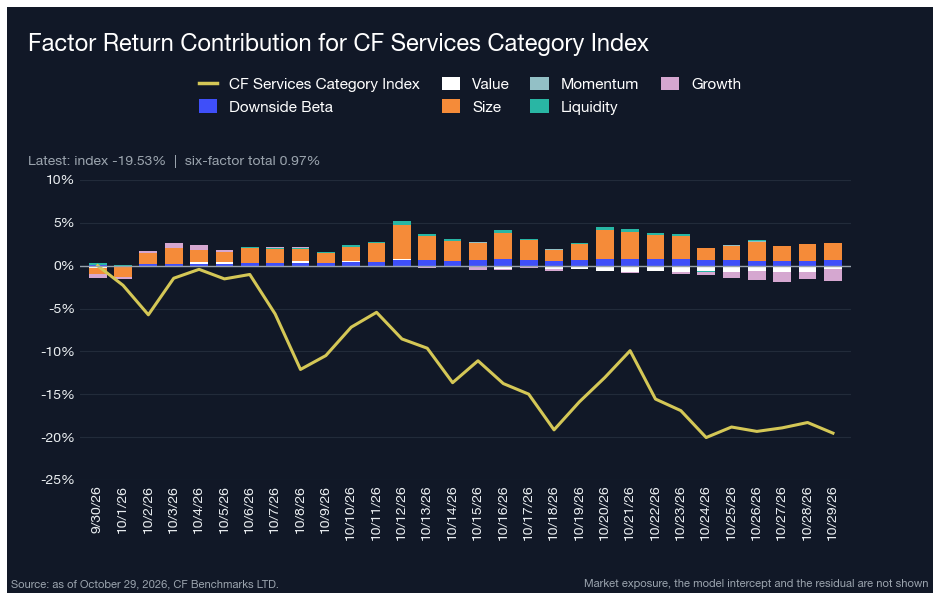
In the CF DACS Services universe, factor contributions total 0.97% against an index return of -19.53%, so the factors sit 20.5 pp above the index, compared with 7.2 pp above it last week as published. The widening is mostly the window. The roll took 22.2 pp off the index as late-September gains left it, and 10.6 pp off the sleeve, which accounts for 11.6 pp of the 13.3 pp change in the gap, and this week's moves of -4.0 pp for the index and -2.3 pp for the sleeve account for the other 1.7 pp. Size (2.04%) is still the largest contributor and again exceeds the whole six-factor total, though it stood at 13.94% last week, followed by Downside Beta (0.64%), with Momentum (0.02%) and Liquidity near zero, and Value (-0.43%) and Growth (-1.30%) the drags. The index lost 4.69% on the week, and one token accounts for more than half of it. WLD, at 11.21% of the weight at the start of the week, fell 25.28% for about 2.8 pp of the decline, trailing the index by 20.6 pp, while Chainlink (LINK), at 41.73%, fell 2.33% for about 1.0 pp. Polygon (POL, +1.88%) and QNT (+1.66%) led, 6.6 pp and 6.4 pp ahead of the index. The Services model carries a Market beta of 1.34, and over the window the token-specific residual, at about -11.8% in log terms, is larger than Market exposure (-8.2%) or the intercept (-2.3%), consistent with large single-token moves such as this week's WLD decline. None of those components sits in the six-factor chart, which is why the sleeve sits so far above the index.
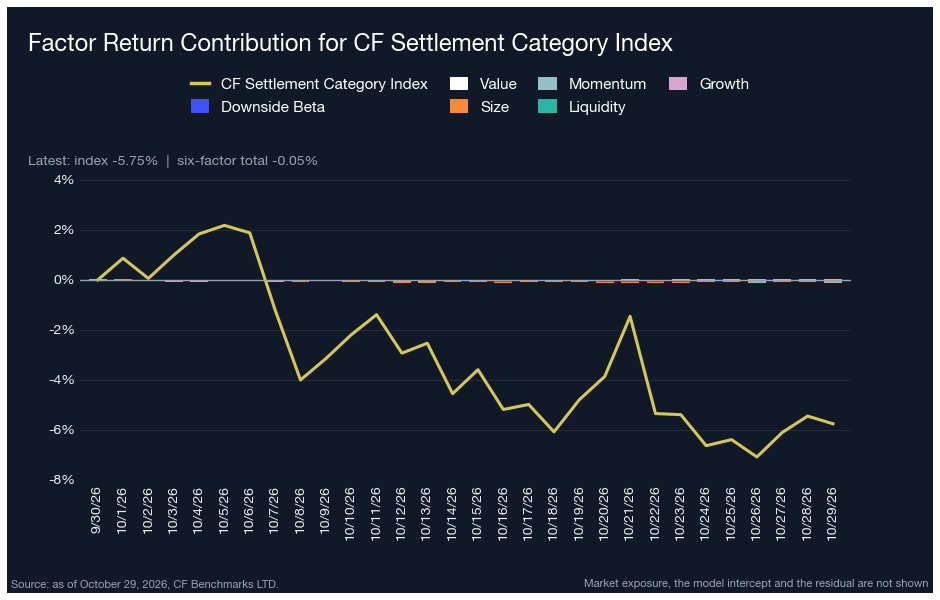
The Settlement universe, dominated by Bitcoin at about 75% of the index, again shows the weakest link to the style factors, which is expected because Market exposure sits outside the set. Factor contributions total -0.05% against an index return of -5.75%, so the factors sit 5.7 pp above the index, compared with 5.3 pp above it last week as published, and no single factor contributes more than 0.05% in either direction. The roll added 0.3 pp to the index and this week's move took off 0.4 pp. The model's Market beta for Settlement is 0.99 with an R2 of 1.00, so the index tracks Market exposure almost one for one. The index lost 0.43% on the week. BTC fell 0.69% for about 0.5 pp of the decline and ETH fell 2.20% for about 0.2 pp, while HYPE (+21.23%), at 3.05% of the weight, added about 0.6 pp, more than offsetting BTC's drag. BCH (+4.99%) was the only other riser, on a 0.24% weight, and the other 15 constituents fell. The largest laggards, Polkadot (DOT, -11.82%) and NEAR (-10.39%), each carried 0.34% of the weight or less. That leaves Settlement a read on Bitcoin and Market exposure more than on the style factors.
Appendix: CF Factor Methodology
Market Factor
The market factor captures the broad, systematic risk that permeates the digital asset ecosystem. It reflects aggregate influences such as macroeconomic conditions, investor sentiment, and overall market volatility. As such, this factor is defined by the daily returns of the CF Broad Cap (Free Float Market Cap Weight) Index, offering a comprehensive and capitalization-weighted representation of the asset class.
Size Factor
The size factor captures the return differential associated with asset scale, reflecting the hypothesis that smaller-cap digital assets tend to outperform their larger-cap counterparts. This effect is understood to compensate for elevated operational and financial risks while exploiting potential market inefficiencies. In this framework, the size factor is defined by each asset’s fully diluted market capitalization. The value is sign-inverted so that higher z-scores are assigned to smaller assets and vice-versa.
Value Factor
The value factor reflects a protocol’s ability to generate economic output relative to its capital base and market valuation, combining measures of both efficiency and user engagement. It is constructed as the average z-score of two key ratios: transaction fees relative to total value locked (Fees/TVL) and daily active users relative to market capitalization (DAU/MCap). This composite metric captures how productively a protocol utilizes its resources while also serving as a proxy for user-driven demand. A higher combined score indicates efficient resource utilization and strong user engagement.
Momentum Factor
The momentum factor captures short-term price persistence by identifying assets that have recently exhibited strong performance. It is computed as the average z-score of two metrics: the 2 weeks cumulative performance and the 2 weeks risk-adjusted cumulative performance. This approach aligns with established findings in traditional financial literature and demonstrates empirical relevance in digital assets, where price trends tend to exhibit momentum over short horizons.
Growth Factor
The growth factor captures the expansion of a protocol’s network activity and user adoption. In the context of digital assets, it reflects metrics such as fee generation and user engagement, which serve as indicators of increased platform utilization and operational scale. The factor is defined as the average z-score of 30-day fee growth and 30-day weekly active user growth, thereby identifying assets exhibiting consistent and measurable increases in underlying network usage.
Downside Beta
The downside beta factor captures an asset’s sensitivity to adverse market conditions by isolating its behavior during periods of negative market returns. Empirical evidence shows that assets with lower downside beta tend to outperform their higher-beta counterparts over the long-term, due to their reduced participation in market drawdowns and more stable return profiles during periods of elevated volatility. As such, it is estimated through a regression of the asset’s daily returns over the most recent four-week period against market returns observed exclusively during negative sessions. The resulting value is sign-inverted to ensure that assets with lower downside exposure are assigned higher z-scores.
Liquidity Factor
The liquidity factor captures the ease with which a digital asset can be traded without significantly impacting its price. Empirical evidence shows that illiquid assets tend to command a higher risk premium than their more liquid counterparts, serving as compensation for trading friction and price volatility. To quantify this, the factor is measured using token turnover, defined as trading volume as a percentage of circulating supply. The value is sign-inverted such that higher z-scores are assigned to less liquid assets.
For further detail, view the CF Factors Methodology Document, the CF Factor Data Suite, and Our paper “A Factor Model for Digital Assets” in Springer Nature’s Mathematical Research for Blockchain Economy.
The information contained within is for educational and informational purposes ONLY. It is not intended nor should it be considered an invitation or inducement to buy or sell any of the underlying instruments cited including but not limited to cryptoassets, financial instruments or any instruments that reference any index provided by CF Benchmarks Ltd. This communication is not intended to persuade or incite you to buy or sell security or securities noted within. Any commentary provided is the opinion of the author and should not be considered a personalised recommendation. Please contact your financial adviser or professional before making an investment decision.
Note: Some of the underlying instruments cited within this material may be restricted to certain customer categories in certain jurisdictions.
Factor Friday - October 30, 2026
Less liquid tokens led CF Benchmarks' factor table as Liquidity gained 1.54% after last week's loss, ending Size's four-week run at the top. Growth fell 2.39% to rank last, while Size, down 0.79% on the week, still leads year to date at 22.76%.
Mark Pilipczuk
How CF Benchmarks treats a Bitcoin hard fork: the ECX case
Published thresholds, applied to observed trading, decide whether a new coin earns an index of its own or counts as a distribution in multi-asset indices. The eCash (ECX) fork around 31 October is a live test of both.
Mark Pilipczuk
CF Institutional Digital Asset Index – Update on the Q3 2026 Reconstitution and Rebalance
Further to the announcement of August 28th, 2026, the Administrator announces that the postponed Q3 2026 Reconstitution and Rebalance of the CF Institutional Digital Asset Index (IDAX) will not be implemented. The Q3 2026 Reconstitution and Rebalance is therefore suspended.
CF Benchmarks
By clicking Accept, you consent to CF Benchmarks's use of cookies.
Visit Cookie Settings to learn how CF Benchmarks uses cookies and to adjust your preferences.