
Nov 20, 2026
Factor Friday - November 20, 2026
Downside Beta leads a deeper sell-off
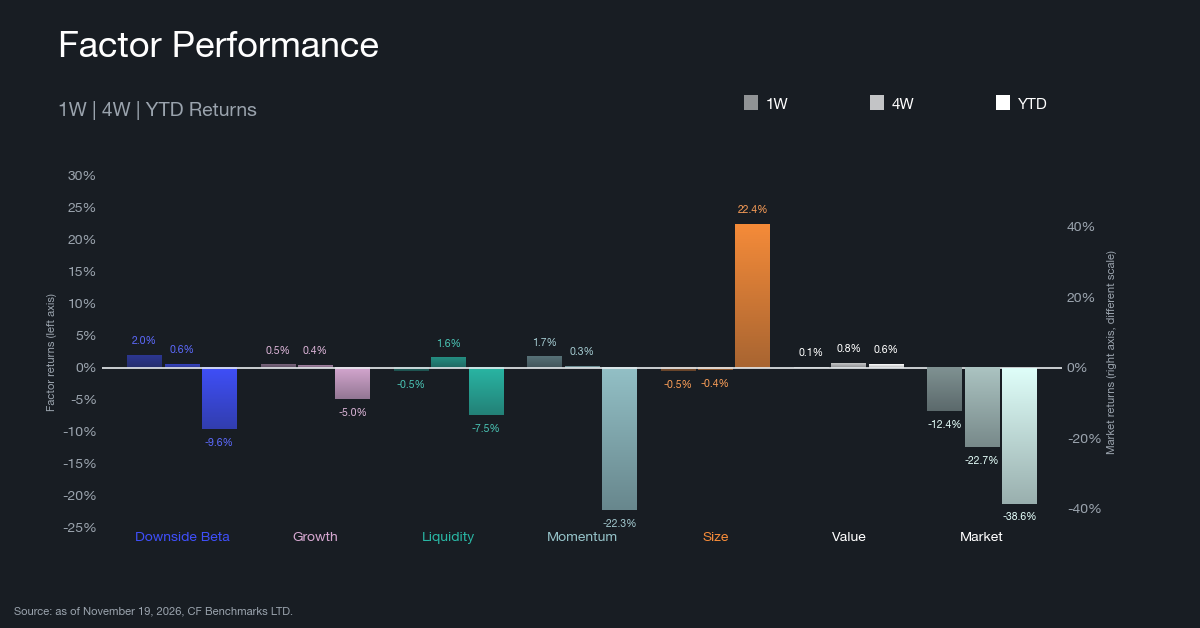
Downside Beta led the factor portfolios up 1.95% in a week the Market fell 12.40%, its largest weekly loss since the week to June 5. Momentum (1.74%), Growth (0.53%) and Value (0.07%) also gained, while Liquidity (-0.51%) and Size (-0.52%) declined, so the six style factors finished within 2.5 percentage points (pp) of each other, against 3.4 pp a week earlier. Over four weeks Liquidity leads at 1.61%, ahead of Value (0.78%), Downside Beta (0.56%), Growth (0.40%), Momentum (0.26%) and Size (-0.44%), with the Market (-22.68%) last. Year to date Size leads at 22.45%, down from 23.09%, followed by Value (0.61%), Growth (-4.98%), Liquidity (-7.46%), Downside Beta (-9.56%) and Momentum (-22.31%), with the Market (-38.64%) at the bottom. Breadth narrowed further, with 1 of 35 CF Broad Cap constituents closing higher against 2 a week ago, and the median constituent lost 11.94% after losing 7.30%. Bitcoin (BTC) fell 13.10%, 1.2 pp behind the median. The Market is down 20.66% month to date, more than double its 9.72% loss for all of October. Neither leading factor has firm support from its beta cohorts. The ten highest downside-beta tokens beat the ten lowest by only 0.1 pp, a lead that rests on one token, and Momentum's 0.9 pp cohort gap reverses once its one riser is removed. The style factor returns are small beside the Market's loss, so exposure to the broad decline remains the main driver of portfolio outcomes.
Rolling Factor Rankings and Rotation
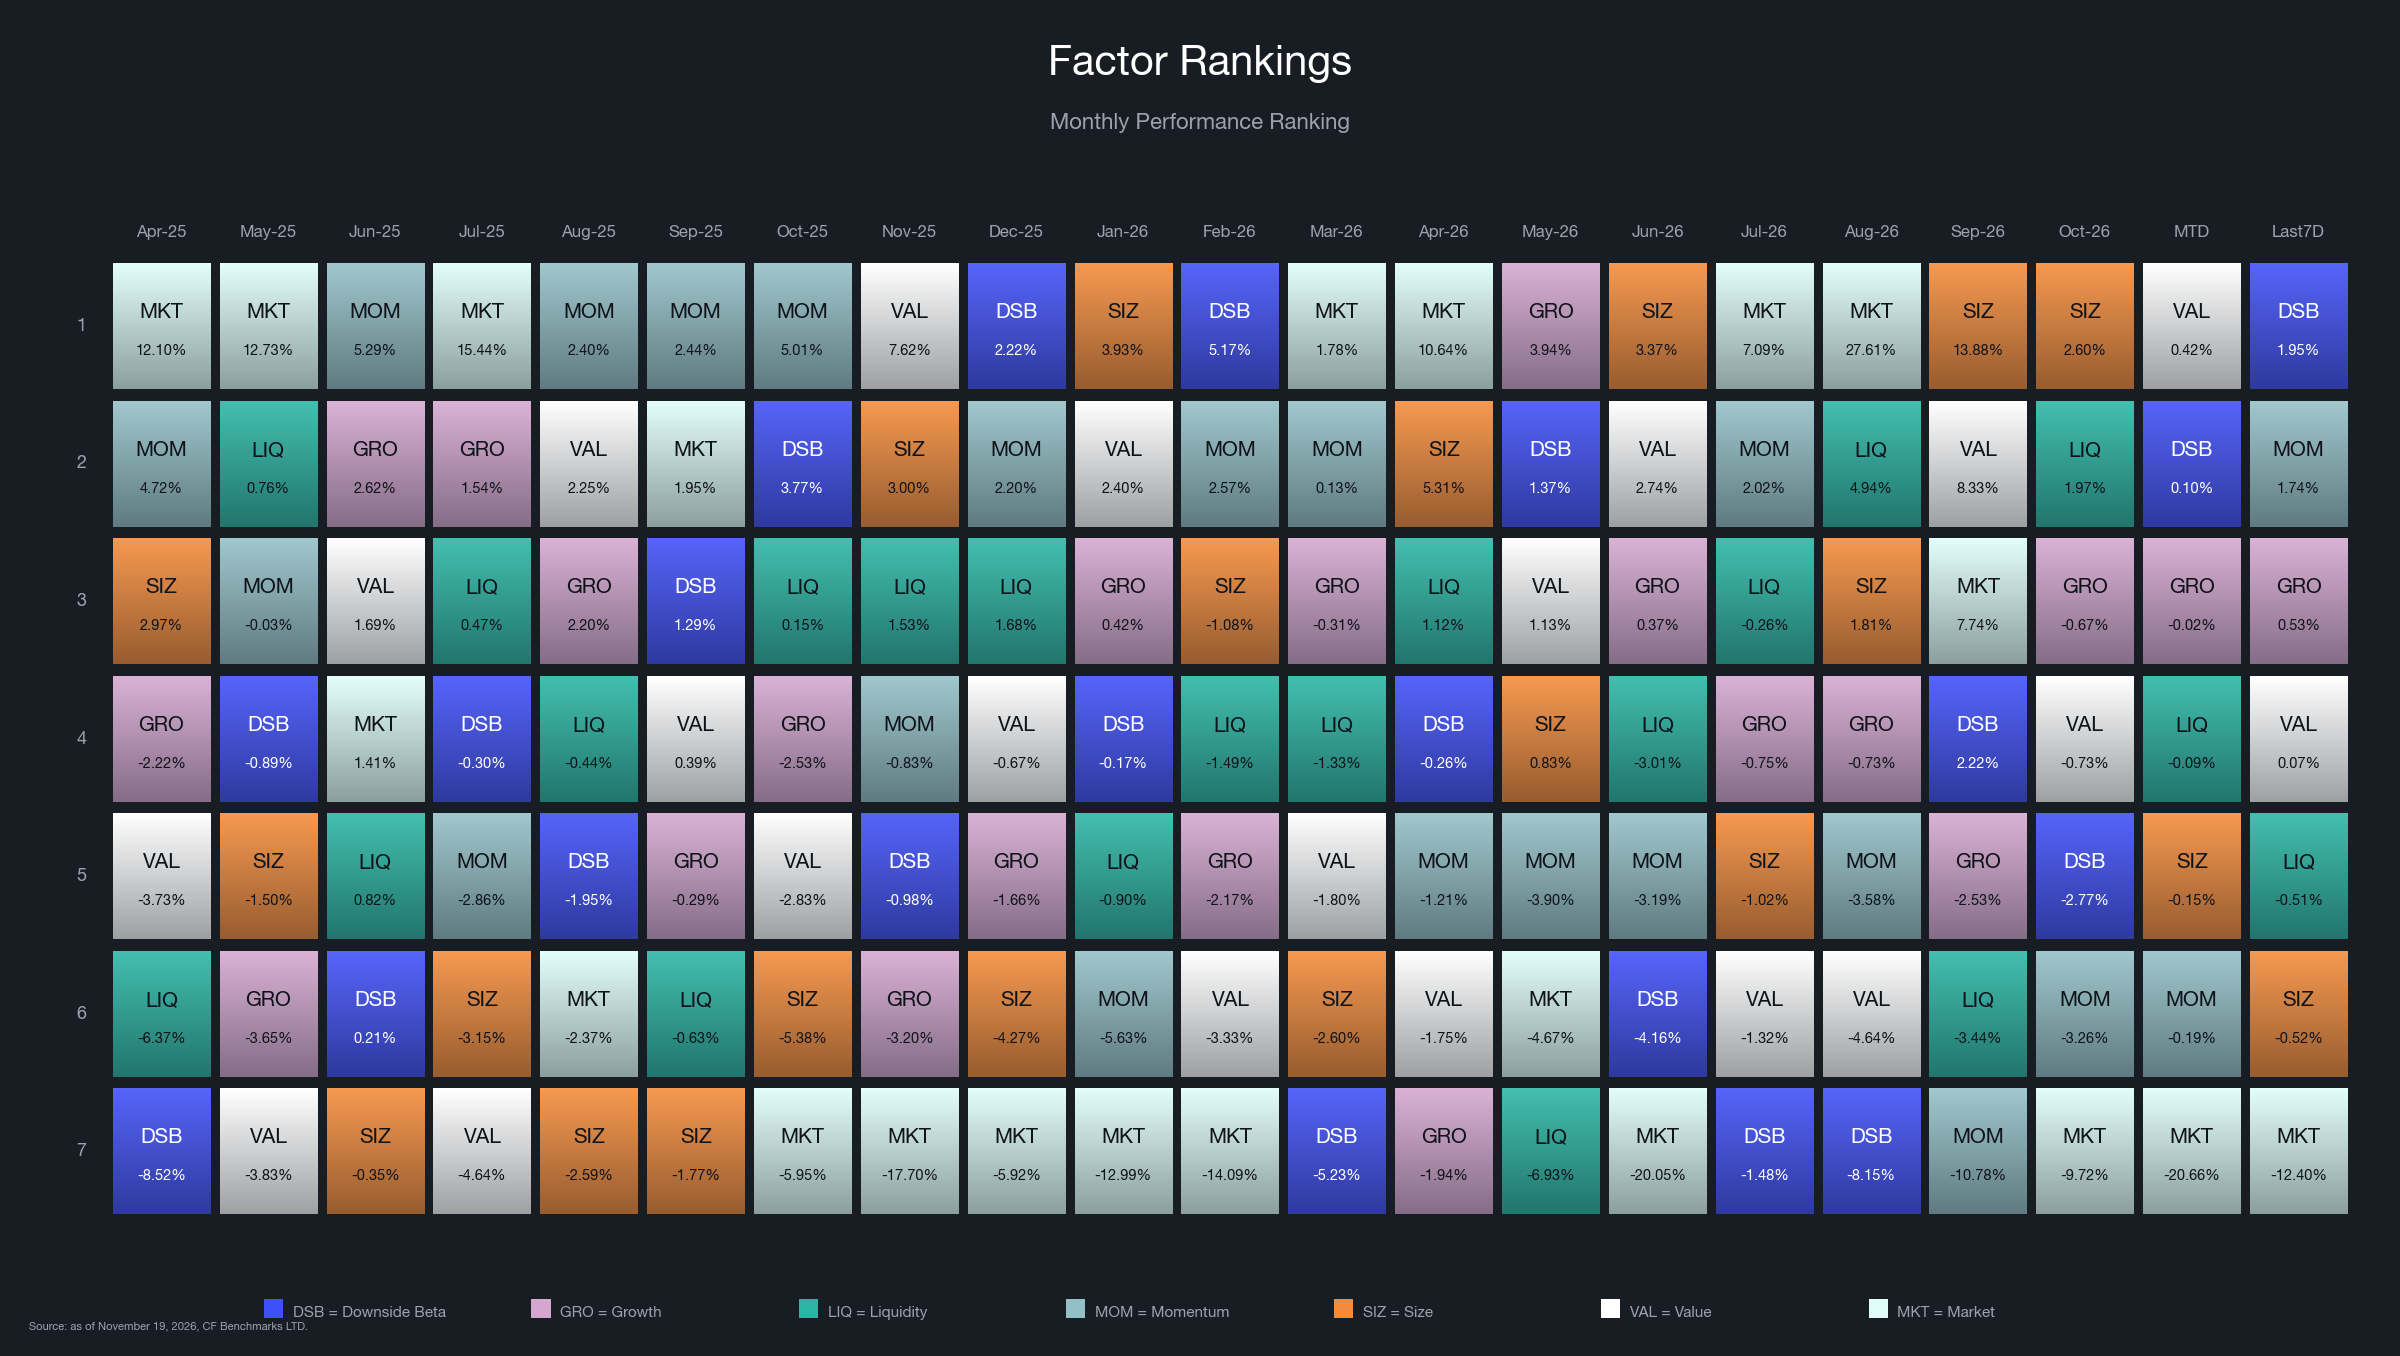
Leadership moved from Size to Downside Beta on the weekly table. Downside Beta rose from sixth to first at 1.95%, after -2.60% a week earlier, and Momentum rose from fifth to second at 1.74%, after -2.34%. Growth stayed third at 0.53%, Value slipped from second to fourth at 0.07%, Liquidity from fourth to fifth at -0.51%, and Size fell from first to sixth at -0.52%. The Market stayed last at -12.40%, its fifth straight weekly loss and the third in a row larger than 6%. Downside Beta and Momentum have now moved together for two weeks, falling together last week and rising together this week. Momentum's gain is its first since the week to October 8 and its largest since the week to July 30. Liquidity leads the four-week table for a third week at 1.61%, up from 1.57%, and five style factors are now positive over four weeks, against two a week ago. Momentum moved from sixth to fifth on that table, with its four-week return rising to 0.26% from -3.68%, a 3.9 pp improvement against a 1.74% gain on the week, and the rest is the window as the days from October 20 to October 26 left it. Size fell from second to sixth at -0.44%, down from 0.45%. Month to date Value leads at 0.42%, ahead of Downside Beta (0.10%), Growth (-0.02%), Liquidity (-0.09%), Size (-0.15%), Momentum (-0.19%) and the Market (-20.66%). Liquidity and Size, first and second month to date a week ago at 0.42% and 0.38%, have fallen to fourth and fifth. Size still leads year to date at 22.45%, well ahead of Value (0.61%). The Market's four-week return fell to -22.68% from -13.87%, and its year-to-date loss widened to -38.64% from -29.95%. With the style factors bunched within 2.5 pp and weekly leadership turning over, no single factor tilt has offered durable protection in this decline.
Market and Key Factor Betas
Market Beta
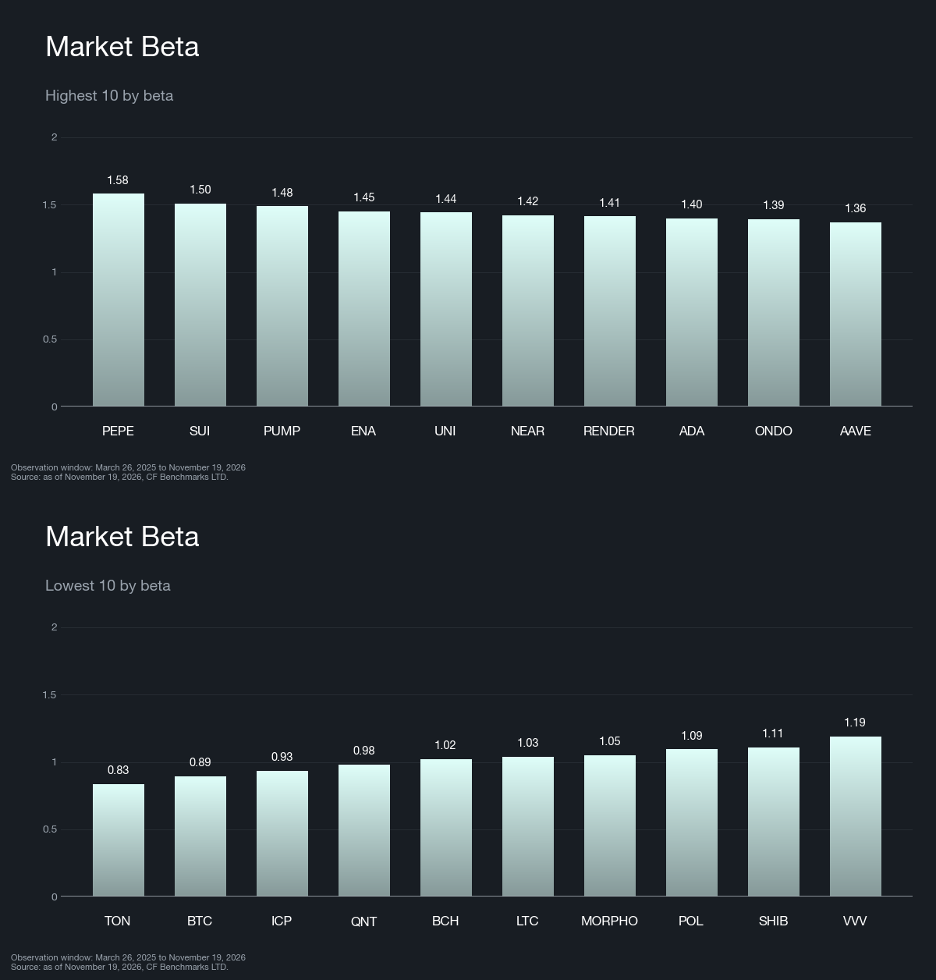
Broad exposure took the loss again. The Market fell 7.25%, and only 2 of 35 CF Broad Cap constituents finished higher, Internet Computer (ICP) at +3.18% and Toncoin (TON) at +1.02%, against 1 a week ago. The median constituent, NEAR Protocol (NEAR), lost 7.30% after 7.43% last week. BTC, at a market beta of 0.89, fell 6.01%, 1.2 pp ahead of the Market. The high market-beta roster changed by one name, with Aave (AAVE) entering at 1.36 as Chainlink (LINK) left. It remains a mix of meme coins and a meme launchpad, three layer-1 platforms, DeFi protocols spanning exchange, lending and synthetic-dollar tokens, an AI compute network and a real-world-asset token. The low-beta ten also changed by one name, with Stellar (XLM) entering at 1.21 as Venice (VVV) left. It holds Bitcoin and two of its forks, two layer-1 and computing platforms, an interoperability token, a lending protocol, a scaling network, a meme coin and a payments token. The ten highest market-beta names returned an average -8.90% against -6.12% for the ten lowest, a 2.8 pp shortfall that runs with the print, down from 4.6 pp last week, and the medians (-7.05% and -5.13%) are 1.9 pp apart in the same direction. Returns inside the high-beta cohort ranged 13.3 pp, from Render (RENDER, -1.51%) to Ethena (ENA, -14.80%). The lowest ten holds two risers, ICP and TON, and excluding them the cohort averages -8.2%, so the shortfall narrows to 0.7 pp. Excluding Bitcoin Cash (BCH, -18.49%) and Quant (QNT, -14.93%), the two worst names in the lowest ten, the lowest ten average -3.5% and the shortfall widens to 5.4 pp. The cohorts run with the print under each cut, but the size of the gap depends on two small risers. Beta ordered returns again, so the highest-beta roster carries the most exposure if the decline extends.
Downside Beta
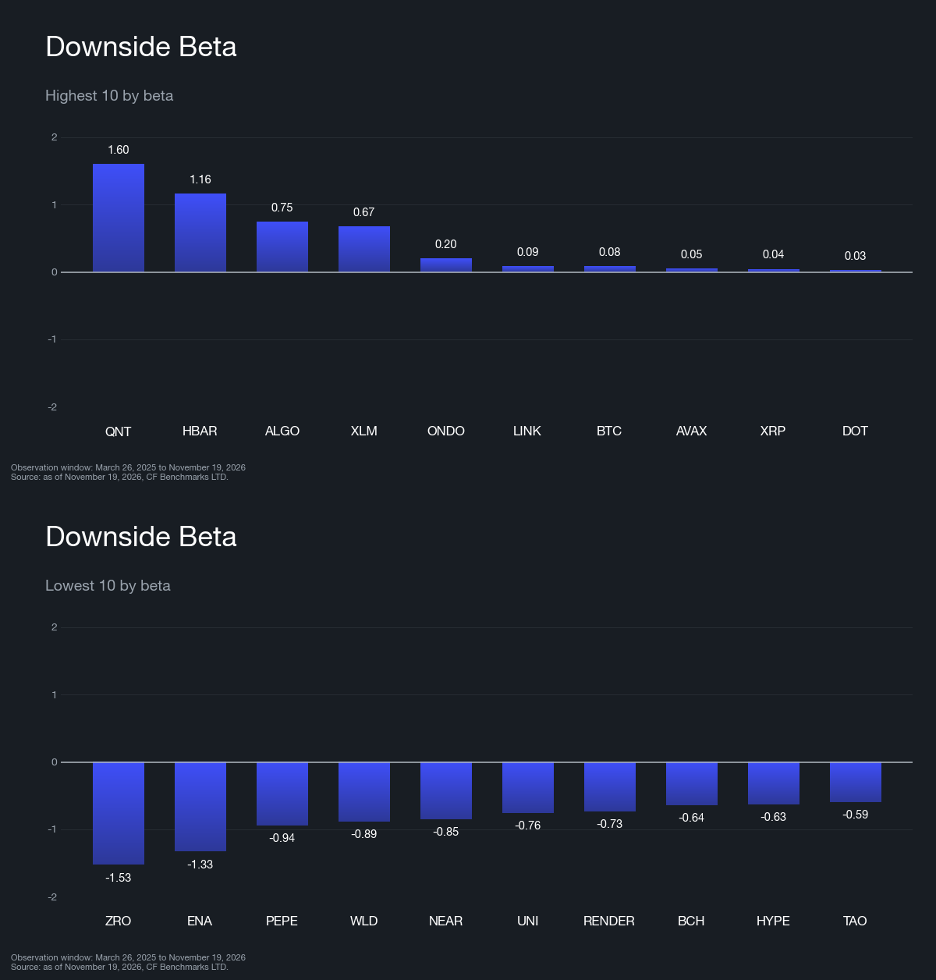
Downside Beta gained 1.95% to rank first, up from sixth last week, reversing a -2.60% loss and resuming the pattern of the two weeks before, when it gained 0.68% and 1.66%. Its four-week return rose to 0.56% from -0.79%, third on that table, it is second month to date at 0.10%, and its year-to-date loss narrowed to -9.56% from -11.29%. The factor is sign-inverted, so a positive print means tokens with lower downside beta outperformed those with higher downside beta, here by falling less. The beta cohorts barely confirm it. The ten highest downside-beta names returned an average -12.06% against -12.20% for the ten lowest, a 0.1 pp gap in the factor's direction, while the medians (-12.70% and -10.85%) are 1.9 pp apart against it. Last week the highest ten led by 1.7 pp on a negative print, against the factor. The gap rests on one token. ENA fell 24.68% in the lowest ten, and excluding it the lowest ten average -10.81%, so the highest ten trail by 1.3 pp, against the print. Exposure is also concentrated at the top. Quant (QNT) leads at 1.60, clear of Hedera (HBAR) at 1.16, and six of the ten sit below 0.21, so the highest ten carries meaningful exposure in only four names. The roster is unchanged from last week, made up of older payments and enterprise networks, two interoperability tokens, an oracle network, a real-world-asset token, Bitcoin and a layer-1 platform. The lowest ten holds DeFi tokens spanning exchange, synthetic-dollar and perpetuals protocols, two AI tokens, an interoperability token, an identity token, a layer-1 platform, a meme coin and a Bitcoin fork, with Bittensor (TAO) entering at -0.59 as VVV left. ZRO still has the lowest beta at -1.53, up from -1.63. Uniswap (UNI) had the largest score move, falling by 1.23 to -2.08, deeper on the short side, while ZRO rose by 1.00 to -0.43 and MORPHO by 0.84 to -0.97. Six names changed sides, Litecoin (LTC), Shiba Inu (SHIB) and TAO to the long side and Aave (AAVE), Algorand (ALGO) and Ether (ETH) to the short. A Downside Beta gain is the expected sign in a falling market, but with the cohorts level the week reads as a narrow factor gain rather than a clear defensive rotation.
Momentum
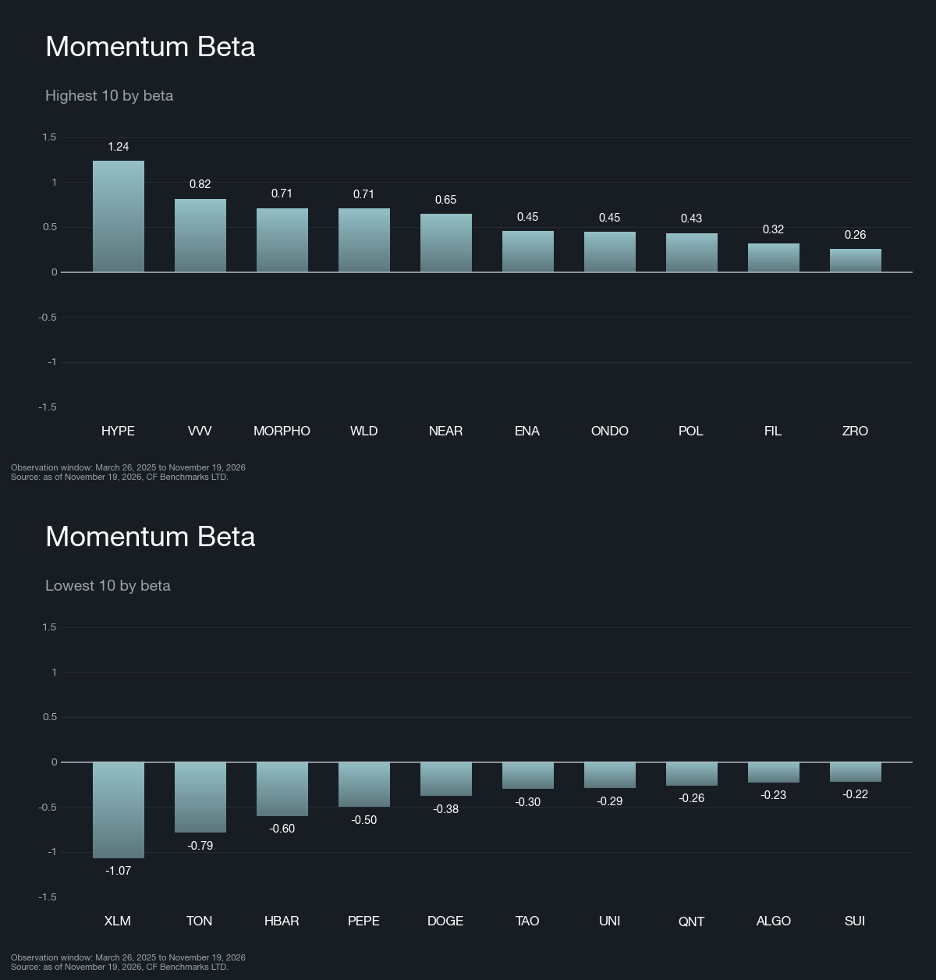
Momentum gained 1.74% to rank second, up from fifth, its first weekly gain since the week to October 8 and its largest since the week to July 30. Its four-week return rose to 0.26% from -3.68%, though most of the 3.9 pp improvement came from the window roll. It is last among the style factors month to date at -0.19%, and its year-to-date loss narrowed to -22.31% from -23.64%, still the weakest of the six. A positive print means tokens with stronger recent returns outperformed those with weaker ones. The beta cohorts confirm it only because of one token. The ten highest momentum-beta names returned an average -11.02% against -11.93% for the ten lowest, a 0.9 pp gap in the factor's direction, but the medians (-12.99% and -11.48%) are 1.5 pp apart against it. VVV, the only riser among the 35 at +16.86%, sits in the highest ten, and excluding it the highest ten average -14.12% and trail the lowest ten by 2.2 pp, against the print. Returns inside the highest ten ranged 41.5 pp, from VVV to ENA. Last week the highest ten trailed by 1.7 pp on a negative print, in the factor's direction. Hyperliquid (HYPE) leads the highest ten at 1.24, clear of VVV, whose beta eased to 0.82 from 0.98. The group otherwise holds lending, identity, synthetic-dollar, real-world-asset, storage and interoperability tokens, a layer-1 platform and a scaling network, with ZRO entering at 0.26 as Polkadot (DOT) left. The lowest ten is unchanged, led by XLM at -1.07, and holds payments and enterprise networks, two meme coins, two layer-1 platforms, an AI token, a DEX token and an interoperability token. Score turnover was heavy, with 18 names changing sides. Pepe (PEPE) fell by 2.93 to 0.64, while Internet Computer (ICP) rose by 2.66 to 2.63, VVV by 2.24 to 1.86 and Toncoin (TON) by 2.10 to 1.34, the last two moving to the long side. UNI fell by 2.03 to -1.04 and moved to the short side, as did HYPE, MORPHO, BTC and ETH. HYPE now carries the highest momentum beta while its score sits on the short side, so its beta reflects past co-movement more than its current trend. Momentum's gain came without a clean cohort result, and the score turnover points to a portfolio still re-sorting after five weeks of Market losses.
What Factors are Driving Markets
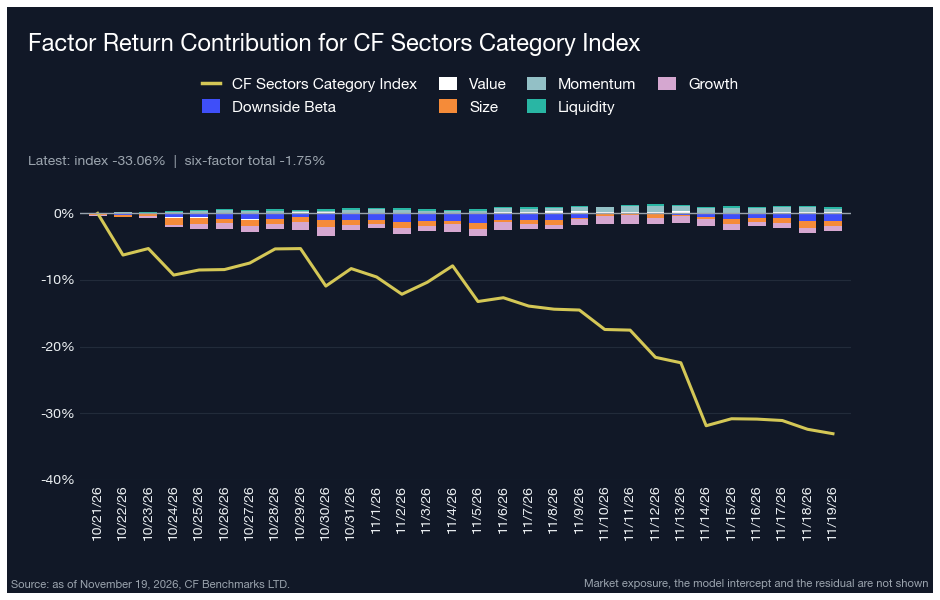
Across the CF DACS Sectors universe, factor contributions total -1.75% over the trailing 30 days against an index return of -33.06%, so the factors sit 31.3 pp above the index, compared with 17.8 pp above it last week as published. That is 13.5 pp wider, and both parts of the change ran the same way. The window roll widened the gap to 21.3 pp, as the sessions from October 14 to October 20, when the index gained, left the window. This week widened it by a further 10.0 pp, with the index down 11.5 pp and the six factors down 1.5 pp. Momentum (0.49%) is the largest contributor for a third week, down from 1.09%, followed by Liquidity (0.21%) and Value (0.21%), while Growth (-0.73%) and Size (-0.81%) are drags and Downside Beta (-1.11%) is now the largest drag, after contributing 0.47% last week. The index fell 14.03% on the week, and two tokens account for more than half of it. Dogecoin (DOGE), at 44.49% of the weight at the start of the week, fell 11.48% for about 5.1 pp of the decline, and UNI, at 13.59%, fell 17.32% for about 2.4 pp. ENA and Pump.fun (PUMP, -22.53%) trailed the index by 10.7 pp and 8.5 pp, while AAVE (-7.79%) and DOGE finished 6.2 pp and 2.6 pp ahead. The six factors shown leave out Market exposure, which the model also includes along with an intercept and a token-specific residual. The Sectors model carries a Market beta of 1.34 with an R2 of 0.81. On a 30-day log basis, the index's -35.42% splits into about -39.09% from Market exposure, -3.06% from the intercept, 8.48% from the residual and -1.75% from the six factors, so Market exposure alone exceeds the whole loss and token-specific moves recovered part of it. Sectors fell with the Market at a beta above one, and the style factors added only a small drag.
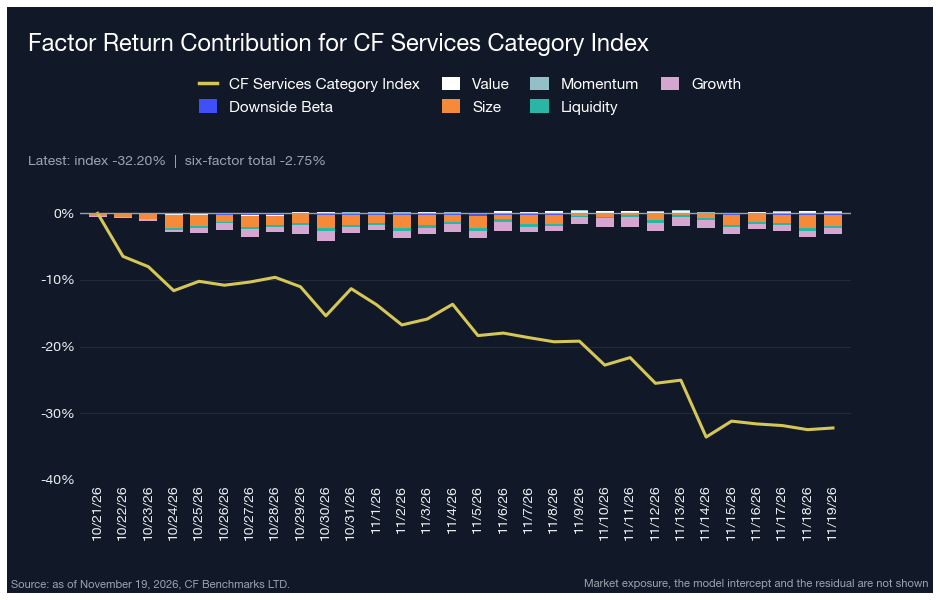
In the CF DACS Services universe, factor contributions total -2.75% against an index return of -32.20%, so the factors sit 29.5 pp above the index, compared with 18.7 pp above it last week as published. The roll widened the gap to 23.2 pp, as the same October sessions left the window, and this week widened it by 6.3 pp, with the index down 6.7 pp and the six factors down 0.4 pp. No factor is a meaningful contributor. Value (0.24%) and Momentum (0.05%) are marginally positive, Downside Beta (-0.28%), Liquidity (-0.37%) and Growth (-0.83%) are drags, and Size (-1.57%) is now the largest drag, down from -0.47%, ending Growth's three weeks in that position. The index lost 8.58% on the week. Chainlink (LINK), at 43.59% of the weight at the start of the week, fell 10.49% for about 4.6 pp, more than half the decline, and TAO, at 12.90%, fell 8.08% for about 1.0 pp. VVV (+16.86%) finished 25.4 pp ahead of the index on about 8% of the weight, while Filecoin (FIL, -23.36%) and Worldcoin (WLD, -14.04%) trailed by 14.8 pp and 5.5 pp. The Services model carries a Market beta of 1.33 with an R2 of 0.81. Of the index's -33.70% log return over the window, Market exposure accounts for about -38.78%, the intercept -1.66%, the residual 9.50% and the six factors -2.75%. The residual swung to 9.50% from -1.58% last week, so Services fell less than its Market exposure implied. With LINK near 44% of the index, one token's move still drove Services more than any factor did.
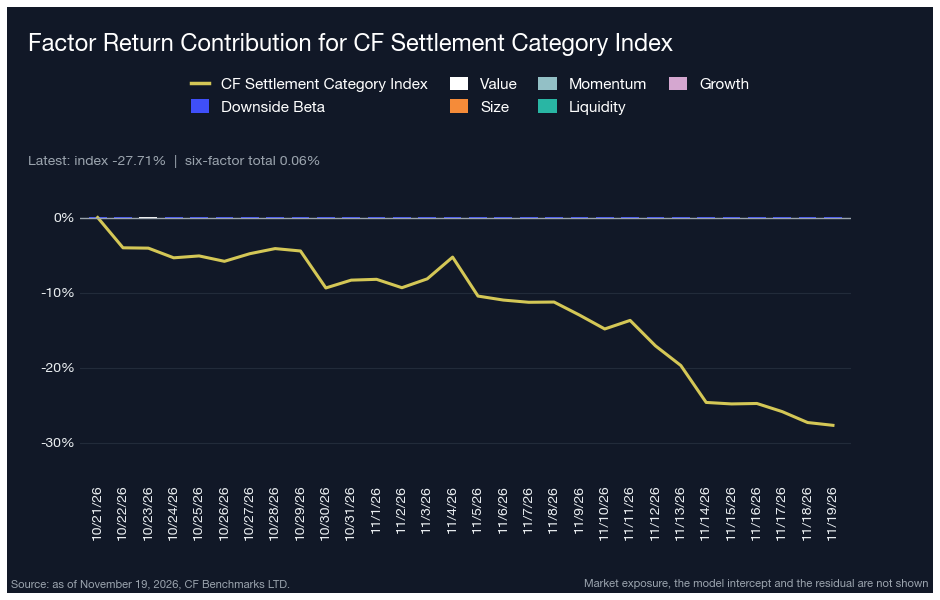
The Settlement universe, dominated by Bitcoin at about three quarters of the index, again shows the weakest link to the style factors, which is expected because Market exposure sits outside the set. Factor contributions total 0.06% against an index return of -27.71%, so the factors sit 27.8 pp above the index, compared with 13.7 pp above it last week as published, and no single factor contributes more than 0.03% in either direction. The roll widened the gap to 17.1 pp, as the October 14 to October 20 gains left the window, and this week took it to 27.8 pp, with the index down a further 10.6 pp and the six factors broadly flat. The model's Market beta for Settlement is 0.99 with an R2 of 1.00, and Market exposure accounts for about -28.90% of the index's -29.05% log return, so the index tracked the Market essentially one for one. The index lost 12.41% on the week, and all 17 constituents fell. BTC fell 13.10% for about 10.0 pp of the decline and ETH fell 12.67% for about 1.4 pp. NEAR (-5.25%), HYPE (-6.04%) and XRP (-6.88%) finished 7.2 pp, 6.4 pp and 5.5 pp ahead of the index, while Avalanche (AVAX, -16.41%) and LTC (-14.98%) trailed by 4.0 pp and 2.6 pp. Style contributions in Settlement read near zero while BTC holds three quarters of the weight.
Appendix: CF Factor Methodology
Market Factor
The market factor captures the broad, systematic risk that permeates the digital asset ecosystem. It reflects aggregate influences such as macroeconomic conditions, investor sentiment, and overall market volatility. As such, this factor is defined by the daily returns of the CF Broad Cap (Free Float Market Cap Weight) Index, offering a comprehensive and capitalization-weighted representation of the asset class.
Size Factor
The size factor captures the return differential associated with asset scale, reflecting the hypothesis that smaller-cap digital assets tend to outperform their larger-cap counterparts. This effect is understood to compensate for elevated operational and financial risks while exploiting potential market inefficiencies. In this framework, the size factor is defined by each asset’s fully diluted market capitalization. The value is sign-inverted so that higher z-scores are assigned to smaller assets and vice-versa.
Value Factor
The value factor reflects a protocol’s ability to generate economic output relative to its capital base and market valuation, combining measures of both efficiency and user engagement. It is constructed as the average z-score of two key ratios: transaction fees relative to total value locked (Fees/TVL) and daily active users relative to market capitalization (DAU/MCap). This composite metric captures how productively a protocol utilizes its resources while also serving as a proxy for user-driven demand. A higher combined score indicates efficient resource utilization and strong user engagement.
Momentum Factor
The momentum factor captures short-term price persistence by identifying assets that have recently exhibited strong performance. It is computed as the average z-score of two metrics: the 2 weeks cumulative performance and the 2 weeks risk-adjusted cumulative performance. This approach aligns with established findings in traditional financial literature and demonstrates empirical relevance in digital assets, where price trends tend to exhibit momentum over short horizons.
Growth Factor
The growth factor captures the expansion of a protocol’s network activity and user adoption. In the context of digital assets, it reflects metrics such as fee generation and user engagement, which serve as indicators of increased platform utilization and operational scale. The factor is defined as the average z-score of 30-day fee growth and 30-day weekly active user growth, thereby identifying assets exhibiting consistent and measurable increases in underlying network usage.
Downside Beta
The downside beta factor captures an asset’s sensitivity to adverse market conditions by isolating its behavior during periods of negative market returns. Empirical evidence shows that assets with lower downside beta tend to outperform their higher-beta counterparts over the long-term, due to their reduced participation in market drawdowns and more stable return profiles during periods of elevated volatility. As such, it is estimated through a regression of the asset’s daily returns over the most recent four-week period against market returns observed exclusively during negative sessions. The resulting value is sign-inverted to ensure that assets with lower downside exposure are assigned higher z-scores.
Liquidity Factor
The liquidity factor captures the ease with which a digital asset can be traded without significantly impacting its price. Empirical evidence shows that illiquid assets tend to command a higher risk premium than their more liquid counterparts, serving as compensation for trading friction and price volatility. To quantify this, the factor is measured using token turnover, defined as trading volume as a percentage of circulating supply. The value is sign-inverted such that higher z-scores are assigned to less liquid assets.
For further detail, view the CF Factors Methodology Document, the CF Factor Data Suite, and Our paper “A Factor Model for Digital Assets” in Springer Nature’s Mathematical Research for Blockchain Economy.
The information contained within is for educational and informational purposes ONLY. It is not intended nor should it be considered an invitation or inducement to buy or sell any of the underlying instruments cited including but not limited to cryptoassets, financial instruments or any instruments that reference any index provided by CF Benchmarks Ltd. This communication is not intended to persuade or incite you to buy or sell security or securities noted within. Any commentary provided is the opinion of the author and should not be considered a personalised recommendation. Please contact your financial adviser or professional before making an investment decision.
Note: Some of the underlying instruments cited within this material may be restricted to certain customer categories in certain jurisdictions.
Factor Friday - November 20, 2026
The Market fell 12.40%, its largest weekly loss since June, and only 1 of 35 Broad Cap tokens rose. Downside Beta led CF Benchmarks' factor table at 1.95% with Momentum second at 1.74%, though neither gain has firm cohort support. Size still leads year to date at 22.45%.
Mark Pilipczuk
Addition of Venice Settlement Prices to the CF Digital Asset Index Family
The Administrator announces the addition of the CF Venice Token-Dollar Settlement Price and CF Venice Token-Dollar US Settlement Price to the CF Digital Asset Index Family - Single Asset Series
CF Benchmarks
Changes to the Token Market Price Benchmarks Series - Market Prices – 17 November 2026
The Administrator has confirmed changes to the Token Market Price Family for the period 10 November 2026 to 17 November 2026
CF Benchmarks
By clicking Accept, you consent to CF Benchmarks's use of cookies.
Visit Cookie Settings to learn how CF Benchmarks uses cookies and to adjust your preferences.