Oct 23, 2026
Factor Friday - Oct 23, 2026
Size Holds The Lead As The Market Falls
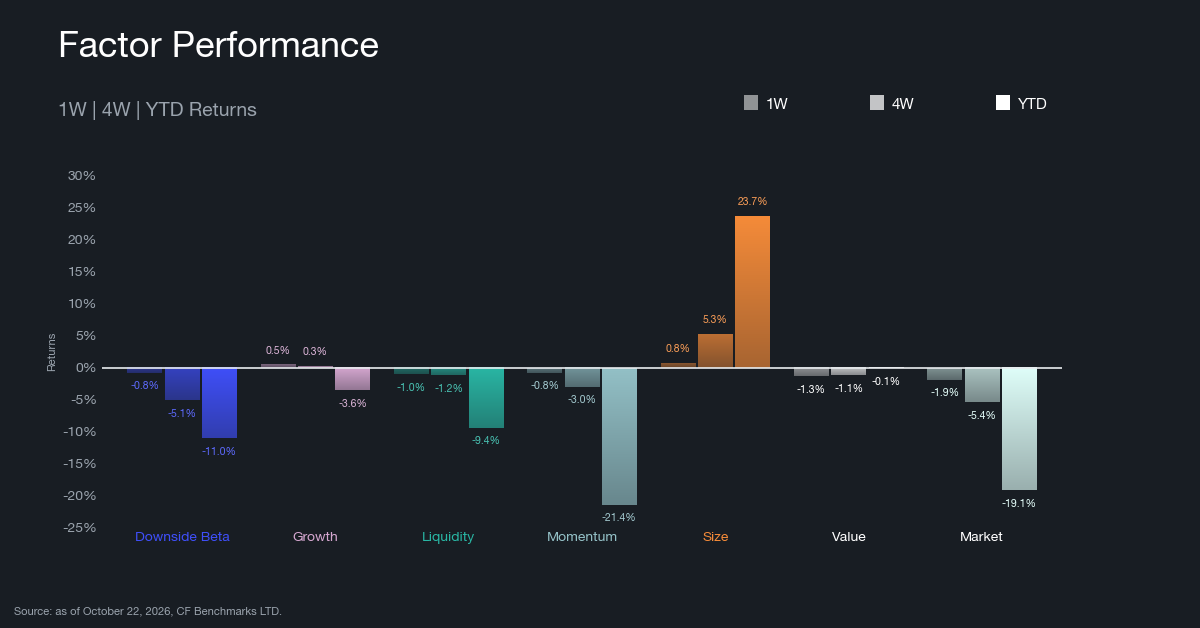
Size led the factor table for a fourth straight week at 0.75% as the Market fell 1.88% to rank last, after rising 0.40% last week. Growth (0.49%) was the only other factor to gain, while Momentum (-0.77%), Downside Beta (-0.79%), Liquidity (-1.03%) and Value (-1.26%) all lost ground. Over four weeks Size leads at 5.26%, with Growth (0.27%) the only other positive, ahead of Value (-1.12%), Liquidity (-1.20%) and Momentum (-2.97%), while Downside Beta (-5.07%) and the Market (-5.42%) trail. Year to date, Size extended its lead to 23.74% from 22.81% a week earlier and Value is near flat at -0.10%, while Growth (-3.55%), Liquidity (-9.38%) and Downside Beta (-11.01%) trail, and the Market (-19.13%) and Momentum (-21.43%) remain the two weakest. Breadth weakened sharply, with 4 of 35 CF Broad Cap constituents closing higher against 15 a week ago, and the median constituent lost 5.27% after losing 0.15% the week before. Bitcoin (BTC) fell 1.29%, 4.0 percentage points (pp) ahead of the median. Because Size is a long-short factor, a positive print means smaller assets outperformed larger ones, but at 0.75% the margin was narrow, and the ten highest size-beta tokens lagged the ten lowest by 3.0 pp, so the beta cohorts did not confirm the print. Liquidity is the exposure to watch. It turned from a 0.22% gain to a 1.03% loss in a week when the Market ranked last, the pattern of a tilt toward more liquid assets, and a rebound that reaches the less liquid tokens would be the first sign of a change.
Rolling Factor Rankings and Rotation
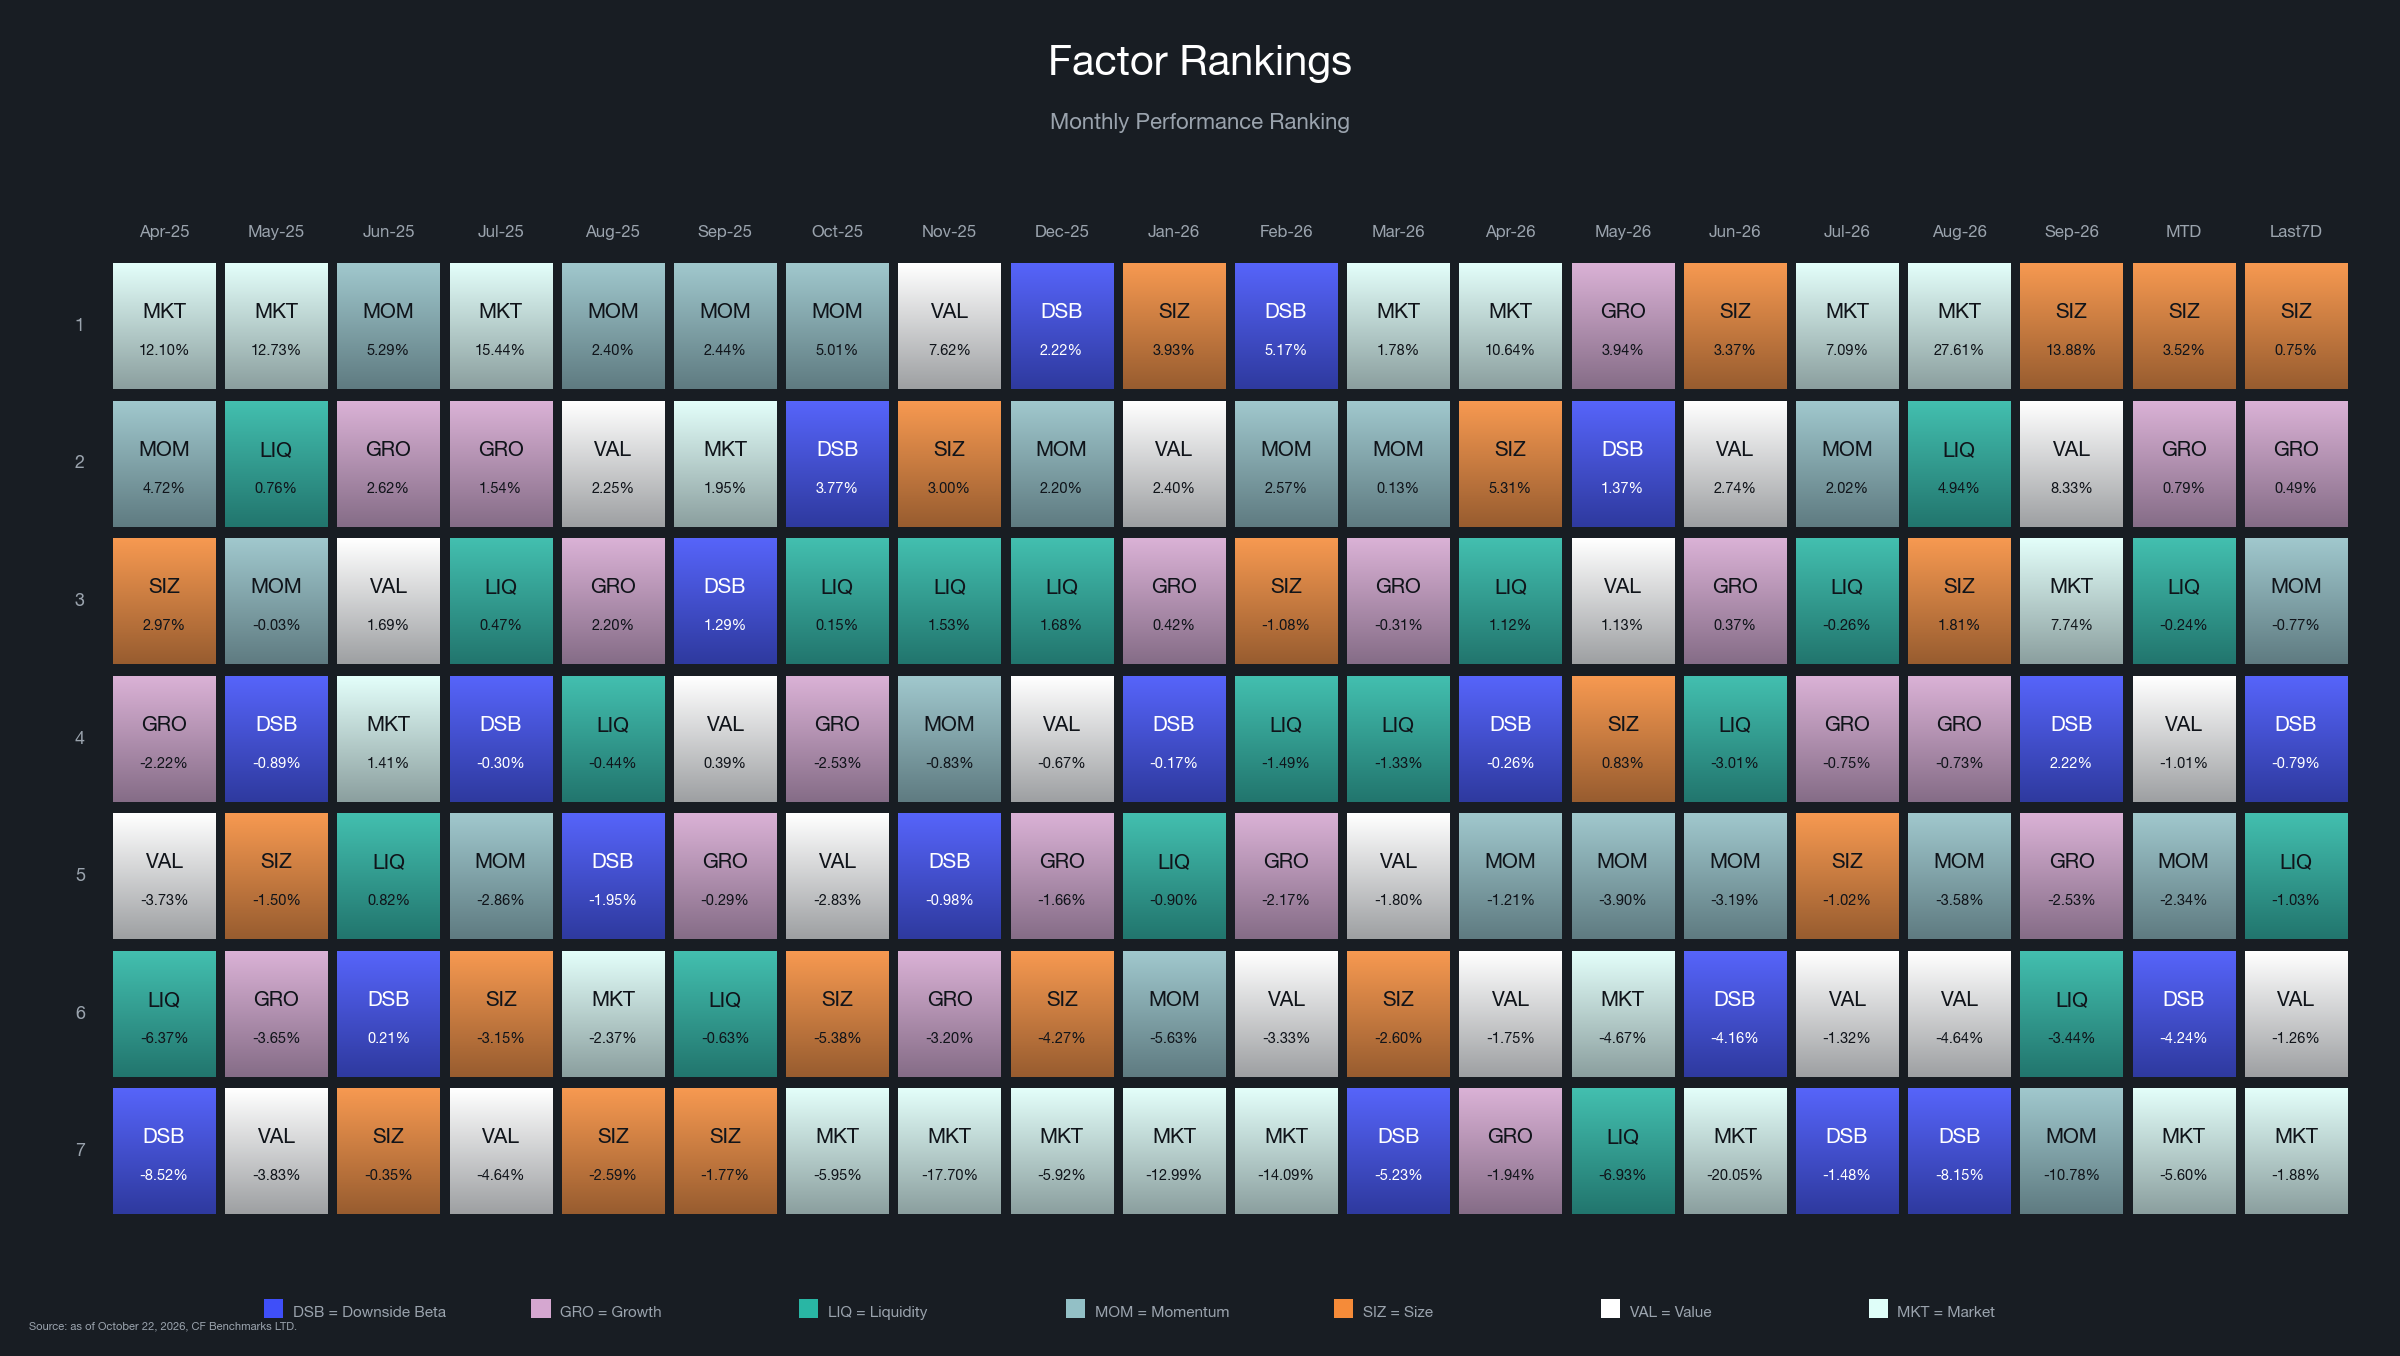
Size kept first place on the weekly table and Growth moved up from fourth to second at 0.49%, the only other factor to gain. Momentum rose from sixth to third at -0.77%, Downside Beta from seventh to fourth at -0.79%, Liquidity slipped from third to fifth at -1.03%, Value from fifth to sixth at -1.26%, and the Market fell from second to last at -1.88%. Month to date Size leads at 3.52%, followed by Growth (0.79%), Liquidity (-0.24%) and Value (-1.01%), while Momentum (-2.34%), Downside Beta (-4.24%) and the Market (-5.60%) are negative, with the Market last on the weekly, four-week and month-to-date tables. Much of the change in the four-week table is the window. Size's four-week return fell to 5.26% from 12.23% because the 8.86% week ending October 1 has largely left the window, Liquidity's fell to -1.20% from 5.25% as the 4.61% week left, and Downside Beta's moved to -5.07% from -0.05% as its 5.59% week left. Size is first on the weekly, four-week, month-to-date and year-to-date tables, and it and Growth are the only factors positive over four weeks. Size has now ranked first for four consecutive weeks, yet its weekly print has run 8.86%, 2.58%, 0.59% and 0.75%, so the lead rests on the longer horizons. Size gives back gains when larger assets outperform, so a rebound that reaches the biggest tokens is the condition that would end the run.
Market and Key Factor Betas
Market Beta
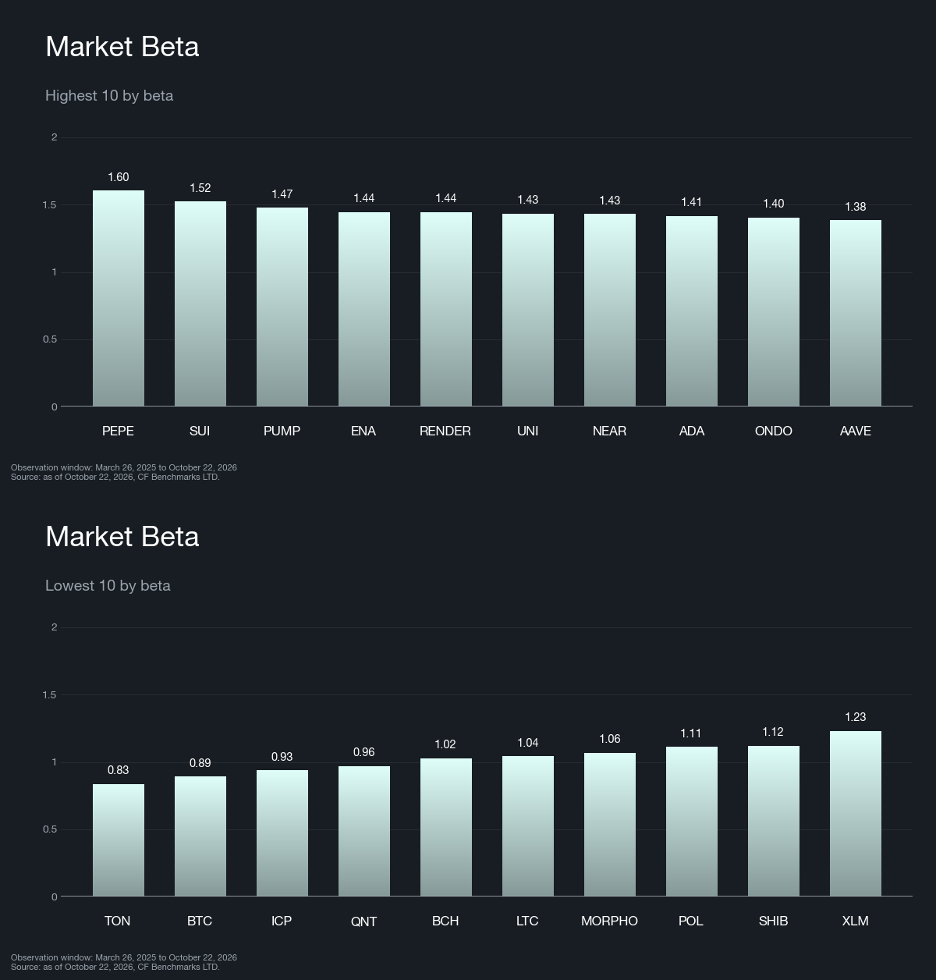
The Market fell 1.88% and breadth weakened, with 4 of 35 CF Broad Cap constituents finishing higher against 15 a week ago. The median constituent lost 5.27% compared with 0.15% last week, and BTC, at a market beta of 0.89, fell 1.29% to finish 0.6 pp ahead of the Market. The high market-beta roster is unchanged, a mix of meme-linked and launchpad tokens, DeFi protocols, AI compute and real-world-asset names and alternative layer-1 platforms. The low-beta ten changed by one name, with Stellar (XLM) entering at 1.23 as Venice (VVV) left, while Toncoin (TON) slipped from 0.86 to 0.83. The ten highest market-beta names returned an average -4.90% against -5.34% for the ten lowest, a gap of 0.4 pp that runs against a falling Market, compared with a 1.1 pp gap that ran with a rising Market a week ago. The medians are -6.14% and -4.79%, a gap of -1.4 pp that runs with the print. The average leans on two names. Pepe (PEPE, +5.53%) and Pump.fun (PUMP, +0.85%) rose while Render (RENDER, -10.86%) fell, a 16.4 pp range inside the cohort, and excluding the two risers the ten highest average -6.92%, 1.6 pp below the lowest ten. Exposure also differs less than the labels suggest, with the low ten between 0.83 and 1.23 and the high ten between 1.38 and 1.60. The cohort average says high beta held up marginally and the median says it lagged, and the difference is two tokens, so broad beta was a thin guide to which holdings held up.
Liquidity
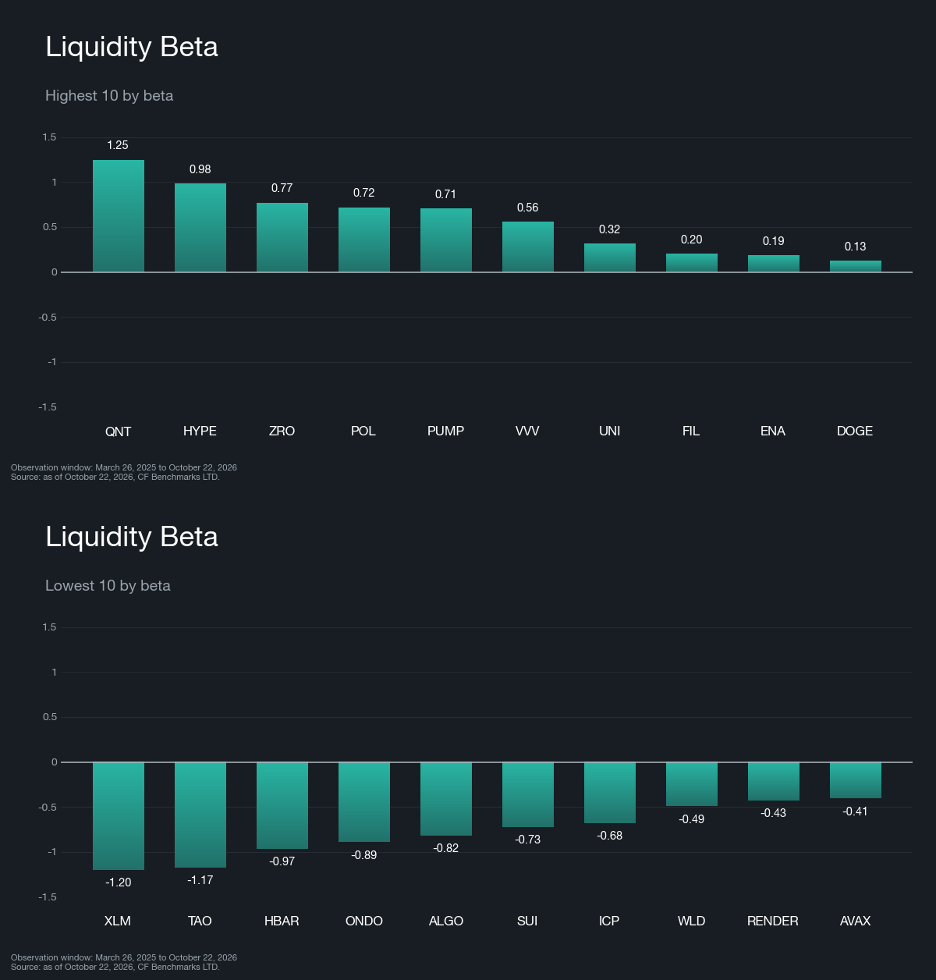
Liquidity fell 1.03% to rank fifth, down from third last week. The factor is sign-inverted, so a negative print means more liquid assets outperformed less liquid ones, the reverse of last week's 0.22% gain. Month to date Liquidity is -0.24%, down from 0.80%, and its four-week return fell to -1.20% from 5.25% as the 4.61% week ending October 1 rolled out of the window. The beta cohorts do not separate cleanly. The ten highest liquidity-beta names returned an average -5.79% against -6.17% for the ten lowest, a 0.4 pp gap that runs against a negative print, and the medians (-5.35% and -7.43%) are 2.1 pp apart in the same direction. Last week's cohorts also ran against that week's print, by 1.3 pp. The result depends on a few tokens. Quant (QNT) sits clear at the top of the high-beta list and fell 10.55%, and PUMP (+0.85%) and VVV (+2.83%) rose inside the highest ten. Excluding those two, the cohort averages -7.70%, 1.5 pp below the lowest ten and in the factor's direction. The lowest ten has an outlier of its own, with Worldcoin (WLD, +10.69%) rising against a group of payment and enterprise chains, layer-1 platforms, and AI and real-world-asset tokens, and excluding it the lowest ten average -8.05%, which puts the highest ten 2.3 pp ahead. The gap therefore ranges from -1.5 pp to 2.3 pp depending on which tokens are removed, so the cohorts are a weak guide to this week's print. The highest ten is unchanged and mixes interoperability, perpetuals-exchange, scaling, meme-launchpad, storage and DeFi tokens with Dogecoin (DOGE) at the low end. Avalanche (AVAX) entered the lowest ten as Morpho (MORPHO) left, and VVV's beta rose from 0.38 to 0.56 while PUMP's fell from 0.80 to 0.71. Portfolio turnover was light, with only Algorand (ALGO) moving from the short to the long side at a score of 0.31, right at the median split between the two sides, and Hedera (HBAR) moving the other way. PUMP's score moved by 3.10, the largest swing, without changing sides. Liquidity flipped sign in a week when the Market ranked last and breadth narrowed, and a rebound that reaches the less liquid tokens would be the condition that returns it to positive.
Size
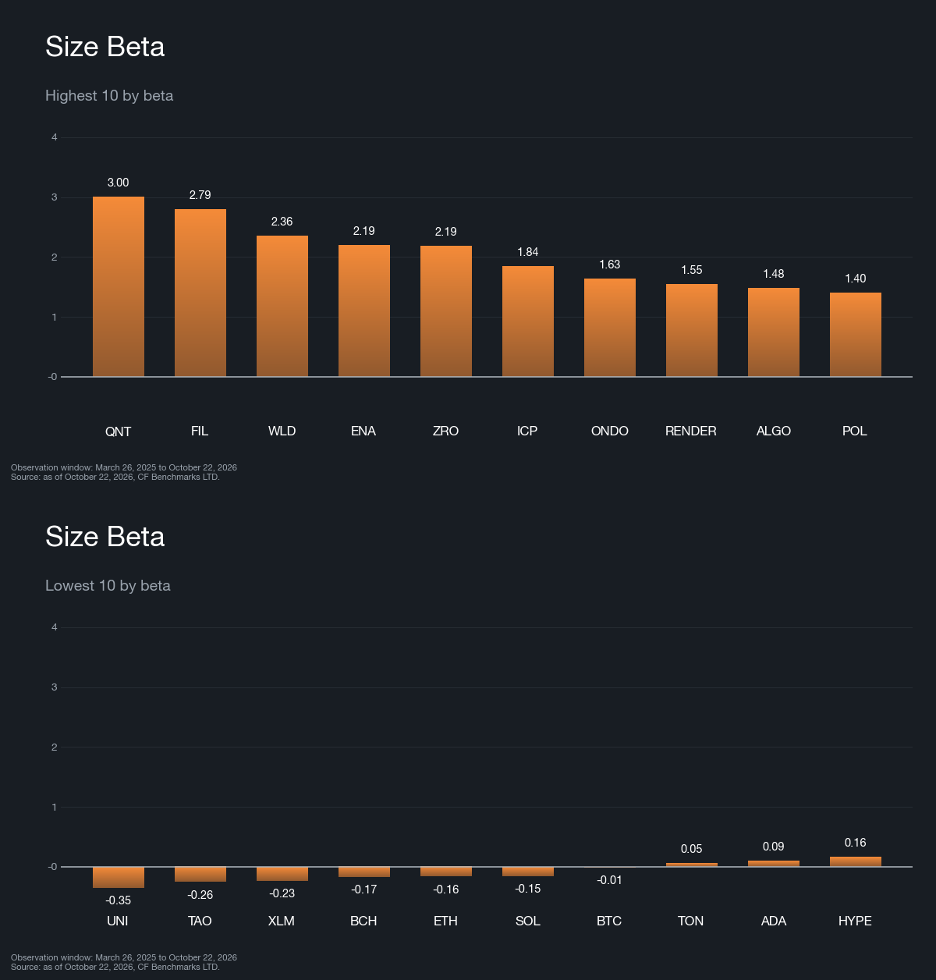
Size gained 0.75% and tops the table for a fourth week, with the weekly print edging up from 0.59% after narrowing from 8.86% to 2.58% to 0.59% over the previous three weeks. The factor is sign-inverted, so a positive print means smaller assets outperformed larger ones. The beta cohorts ran the other way. The ten highest size-beta names returned an average -7.45% against -4.44% for the ten lowest, a gap of -3.0 pp against a positive print, compared with a 1.3 pp gap in the factor's direction last week, and the medians (-9.45% and -4.79%) are 4.7 pp apart in the same direction. Nine of the ten highest fell, with WLD (+10.69%) the lone riser, and excluding it the gap widens to 5.0 pp. Excluding QNT, which sits clear at the top of the list and fell 10.55%, the gap is 2.7 pp, so it runs against the print under every cut. Beta measures sensitivity to the factor and the return comes from the portfolio, so the cohorts are a weak guide to this week's print. The composition barely changed. Neither list had an entry or an exit, the high end is still drawn from interoperability, storage, AI compute, real-world-asset and DeFi tokens, the low end is the largest networks and payment chains, and no beta moved by as much as 0.1. Size scores barely moved because they track market capitalization, with the largest change just 0.03. Only two of 35 names switched sides, QNT from short to long and Shiba Inu (SHIB) from long to short, both at about 0.22, the median split between the two sides, so a short-side name can carry a positive score. This week's return therefore reflects price action. The weekly print has stopped narrowing but sits well below the 8.86% of early October, so the lead rests on the four-week (5.26%) and year-to-date (23.74%) returns, and a rebound led by larger assets would be the test.
What Factors are Driving Markets
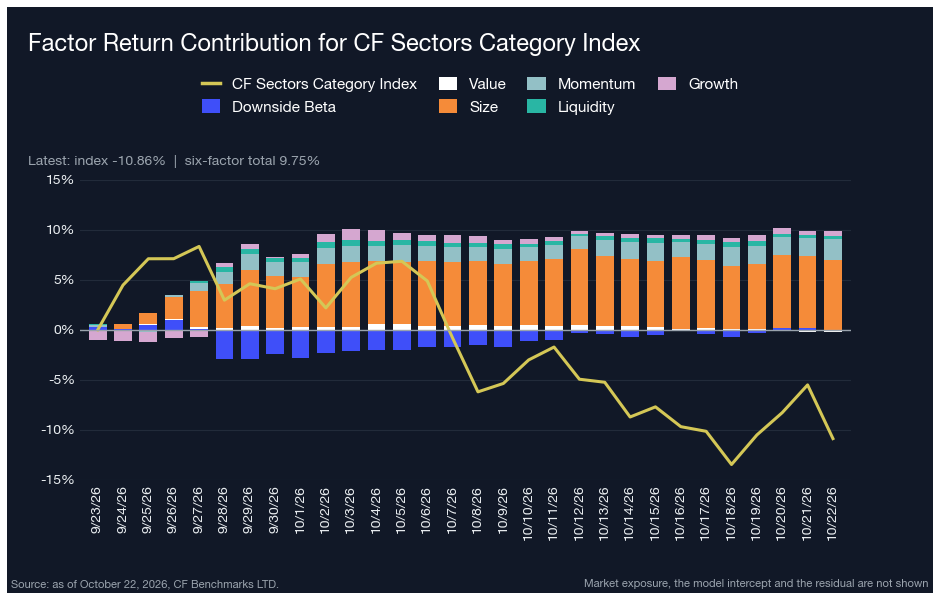
Across the CF DACS Sectors universe, factor contributions total 9.75% over the trailing 30 days against an index return of -10.86%, so the factors sit 20.6 pp above the index, compared with 1.1 pp above it last week as published. Both readings sit on a rolling window. The roll took 19.6 pp off the index and 4.1 pp off the six-factor sleeve as the oldest days left, which accounts for 15.5 pp of the 19.5 pp change in the gap, and this week's moves of -3.2 pp for the index and 0.8 pp for the sleeve account for the other 4.0 pp. Size (7.05%) remains the dominant contributor, followed by Momentum (2.01%), with Growth (0.51%) and Liquidity (0.34%) small and Value (-0.07%) and Downside Beta (-0.09%) slight drags. Downside Beta was second last week at 2.81%. The index lost 3.67% on the week, with DOGE, at 44.63% of the weight, down 3.52% for about 1.6 pp of the decline and Uniswap (UNI), at 13.59%, down 5.45% for about 0.7 pp. PEPE (+5.53%) led, 9.2 pp ahead of the index, and PUMP (+0.85%) was the only other riser, while Ondo (ONDO, -8.36%) trailed by 4.7 pp and MORPHO (-6.56%) by 2.9 pp. The six factors shown leave out Market exposure, which the model also includes along with an intercept and a token-specific residual. The Sectors model carries a Market beta of 1.35 with an R2 of 0.81, so the index holds more Market exposure than the Market itself, which weighed on it in a week when the Market ranked last.
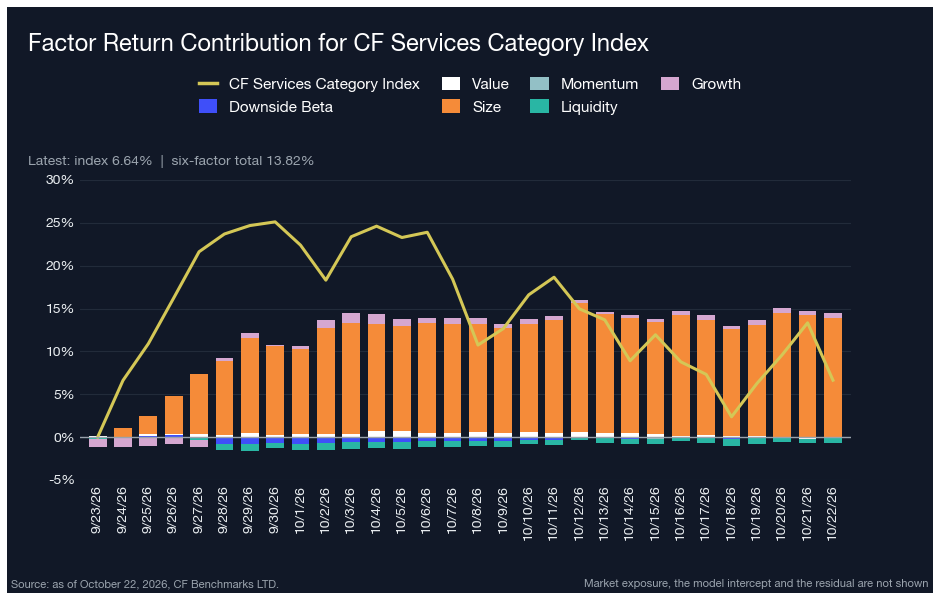
In the CF DACS Services universe, factor contributions total 13.82% against an index return of 6.64%, so the factors exceed the index by 7.2 pp, where last week the index led by 16.9 pp as published. The swing is mostly the window. The roll took 21.7 pp off the index and 3.8 pp off the sleeve, which accounts for 17.9 pp of the 24.1 pp change in the gap, and this week's moves of -5.3 pp and 0.9 pp account for the other 6.2 pp. Size supplies more than the whole six-factor total at 13.94% against 13.82%, with Growth (0.53%) the only other positive contribution and Liquidity (-0.50%) the largest drag, while Value (-0.08%), Momentum (-0.03%) and Downside Beta (-0.03%) are negligible. The index lost 5.00% on the week, with Chainlink (LINK), at 41.64% of the weight, down 4.80% for about 2.0 pp of the decline and Bittensor (TAO), at 13.10%, down 7.93% for about 1.0 pp. QNT fell 10.55%, 5.6 pp behind the index, while the Size contribution rose 0.8 pp, so for a second week a QNT reversal reached the index before it reached the Size contribution. WLD (+10.69%) led, 15.7 pp ahead of the index, with VVV 7.8 pp ahead, while LayerZero (ZRO, -15.46%) trailed by 10.5 pp and Filecoin (FIL, -14.51%) by 9.5 pp. The sleeve exceeds the index because Market exposure, which the model carries at a beta of 1.34, and the intercept net to a negative over the window, and neither is in the six-factor chart. Size remains the exposure underneath the index.
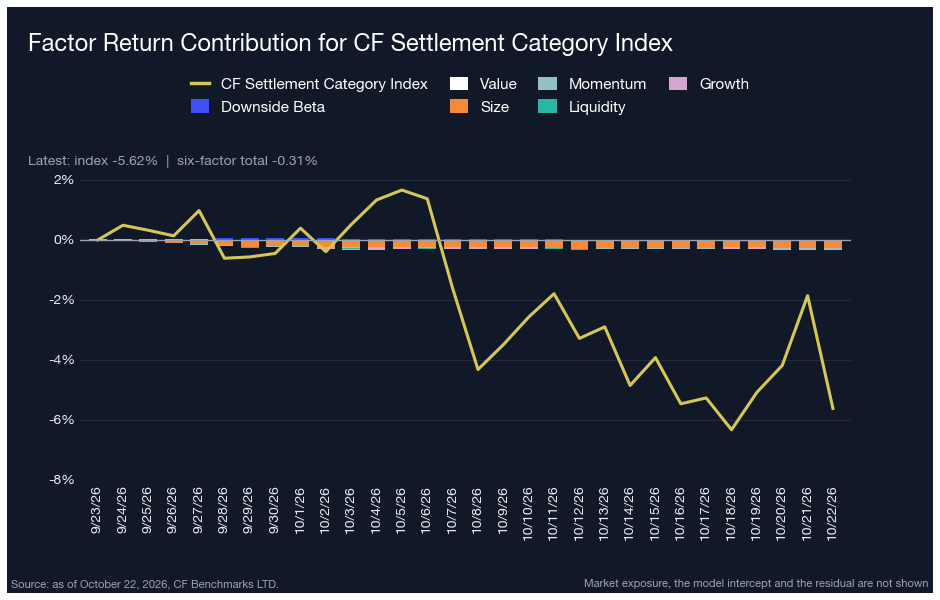
The Settlement universe, dominated by Bitcoin at about 75% of the index, again shows the weakest link to the style factors, which is expected because Market exposure sits outside the set. Factor contributions total -0.31% against an index return of -5.62%, so the factors exceed the index by 5.3 pp, where last week the index led by 8.3 pp as published, and Size (-0.26%) is the only factor larger than 0.04 pp in either direction. The swing is mostly the window, with the roll taking 11.9 pp off the index and this week's move 1.7 pp. The model's Market beta for Settlement is 0.99 with an R2 of 1.00, so the index tracks Market exposure almost one for one. The index lost 1.82% on the week and all 17 constituents fell, with BTC (-1.29%) the smallest decline, 0.5 pp ahead of the index and about 1.0 pp of the loss on its weight. Ether (ETH, -2.85%) trailed the index by 1.0 pp and Solana (SOL, -2.37%) by 0.6 pp. The largest laggards were too small to move the index, with Internet Computer (ICP, -11.66%), Avalanche (AVAX, -9.25%) and NEAR Protocol (NEAR, -8.91%) each on a weight of 0.34% or less. That makes Settlement a read on Bitcoin and Market exposure more than on the style factors.
Appendix: CF Factor Methodology
Market Factor
The market factor captures the broad, systematic risk that permeates the digital asset ecosystem. It reflects aggregate influences such as macroeconomic conditions, investor sentiment, and overall market volatility. As such, this factor is defined by the daily returns of the CF Broad Cap (Free Float Market Cap Weight) Index, offering a comprehensive and capitalization-weighted representation of the asset class.
Size Factor
The size factor captures the return differential associated with asset scale, reflecting the hypothesis that smaller-cap digital assets tend to outperform their larger-cap counterparts. This effect is understood to compensate for elevated operational and financial risks while exploiting potential market inefficiencies. In this framework, the size factor is defined by each asset’s fully diluted market capitalization. The value is sign-inverted so that higher z-scores are assigned to smaller assets and vice-versa.
Value Factor
The value factor reflects a protocol’s ability to generate economic output relative to its capital base and market valuation, combining measures of both efficiency and user engagement. It is constructed as the average z-score of two key ratios: transaction fees relative to total value locked (Fees/TVL) and daily active users relative to market capitalization (DAU/MCap). This composite metric captures how productively a protocol utilizes its resources while also serving as a proxy for user-driven demand. A higher combined score indicates efficient resource utilization and strong user engagement.
Momentum Factor
The momentum factor captures short-term price persistence by identifying assets that have recently exhibited strong performance. It is computed as the average z-score of two metrics: the 2 weeks cumulative performance and the 2 weeks risk-adjusted cumulative performance. This approach aligns with established findings in traditional financial literature and demonstrates empirical relevance in digital assets, where price trends tend to exhibit momentum over short horizons.
Growth Factor
The growth factor captures the expansion of a protocol’s network activity and user adoption. In the context of digital assets, it reflects metrics such as fee generation and user engagement, which serve as indicators of increased platform utilization and operational scale. The factor is defined as the average z-score of 30-day fee growth and 30-day weekly active user growth, thereby identifying assets exhibiting consistent and measurable increases in underlying network usage.
Downside Beta
The downside beta factor captures an asset’s sensitivity to adverse market conditions by isolating its behavior during periods of negative market returns. Empirical evidence shows that assets with lower downside beta tend to outperform their higher-beta counterparts over the long-term, due to their reduced participation in market drawdowns and more stable return profiles during periods of elevated volatility. As such, it is estimated through a regression of the asset’s daily returns over the most recent four-week period against market returns observed exclusively during negative sessions. The resulting value is sign-inverted to ensure that assets with lower downside exposure are assigned higher z-scores.
Liquidity Factor
The liquidity factor captures the ease with which a digital asset can be traded without significantly impacting its price. Empirical evidence shows that illiquid assets tend to command a higher risk premium than their more liquid counterparts, serving as compensation for trading friction and price volatility. To quantify this, the factor is measured using token turnover, defined as trading volume as a percentage of circulating supply. The value is sign-inverted such that higher z-scores are assigned to less liquid assets.
For further detail, view the CF Factors Methodology Document, the CF Factor Data Suite, and Our paper “A Factor Model for Digital Assets” in Springer Nature’s Mathematical Research for Blockchain Economy.
The information contained within is for educational and informational purposes ONLY. It is not intended nor should it be considered an invitation or inducement to buy or sell any of the underlying instruments cited including but not limited to cryptoassets, financial instruments or any instruments that reference any index provided by CF Benchmarks Ltd. This communication is not intended to persuade or incite you to buy or sell security or securities noted within. Any commentary provided is the opinion of the author and should not be considered a personalised recommendation. Please contact your financial adviser or professional before making an investment decision.
Note: Some of the underlying instruments cited within this material may be restricted to certain customer categories in certain jurisdictions.
Factor Friday - Oct 23, 2026
Size led CF Benchmarks' factor table for a fourth week at 0.75% as the Market fell 1.88% and only 4 of 35 Broad Cap tokens closed higher. Liquidity turned negative at -1.03% as more liquid assets held up better, and Size's year-to-date lead extended to 23.74%.
Mark Pilipczuk
Changes to the Token Market Price Benchmarks Series - Market Prices – 20 October 2026
The Administrator has confirmed changes to the Token Market Price Family for the period 13 October 2026 to 20 October 2026
CF Benchmarks
Altcoins Lag as Bitcoin Tests The 50-Day Moving Average
Digital assets fell broadly over the past week as Bitcoin slipped to a moving average, with inflation prints and an equity sell-off in the background. Losses grew with distance from Bitcoin, hitting diversified and smaller-cap exposure hardest, while implied volatility rose.
Mark Pilipczuk
By clicking Accept, you consent to CF Benchmarks's use of cookies.
Visit Cookie Settings to learn how CF Benchmarks uses cookies and to adjust your preferences.