
Nov 16, 2026
Crypto Falls Following Hot CPI
Weekly Index Highlights, November 16, 2026
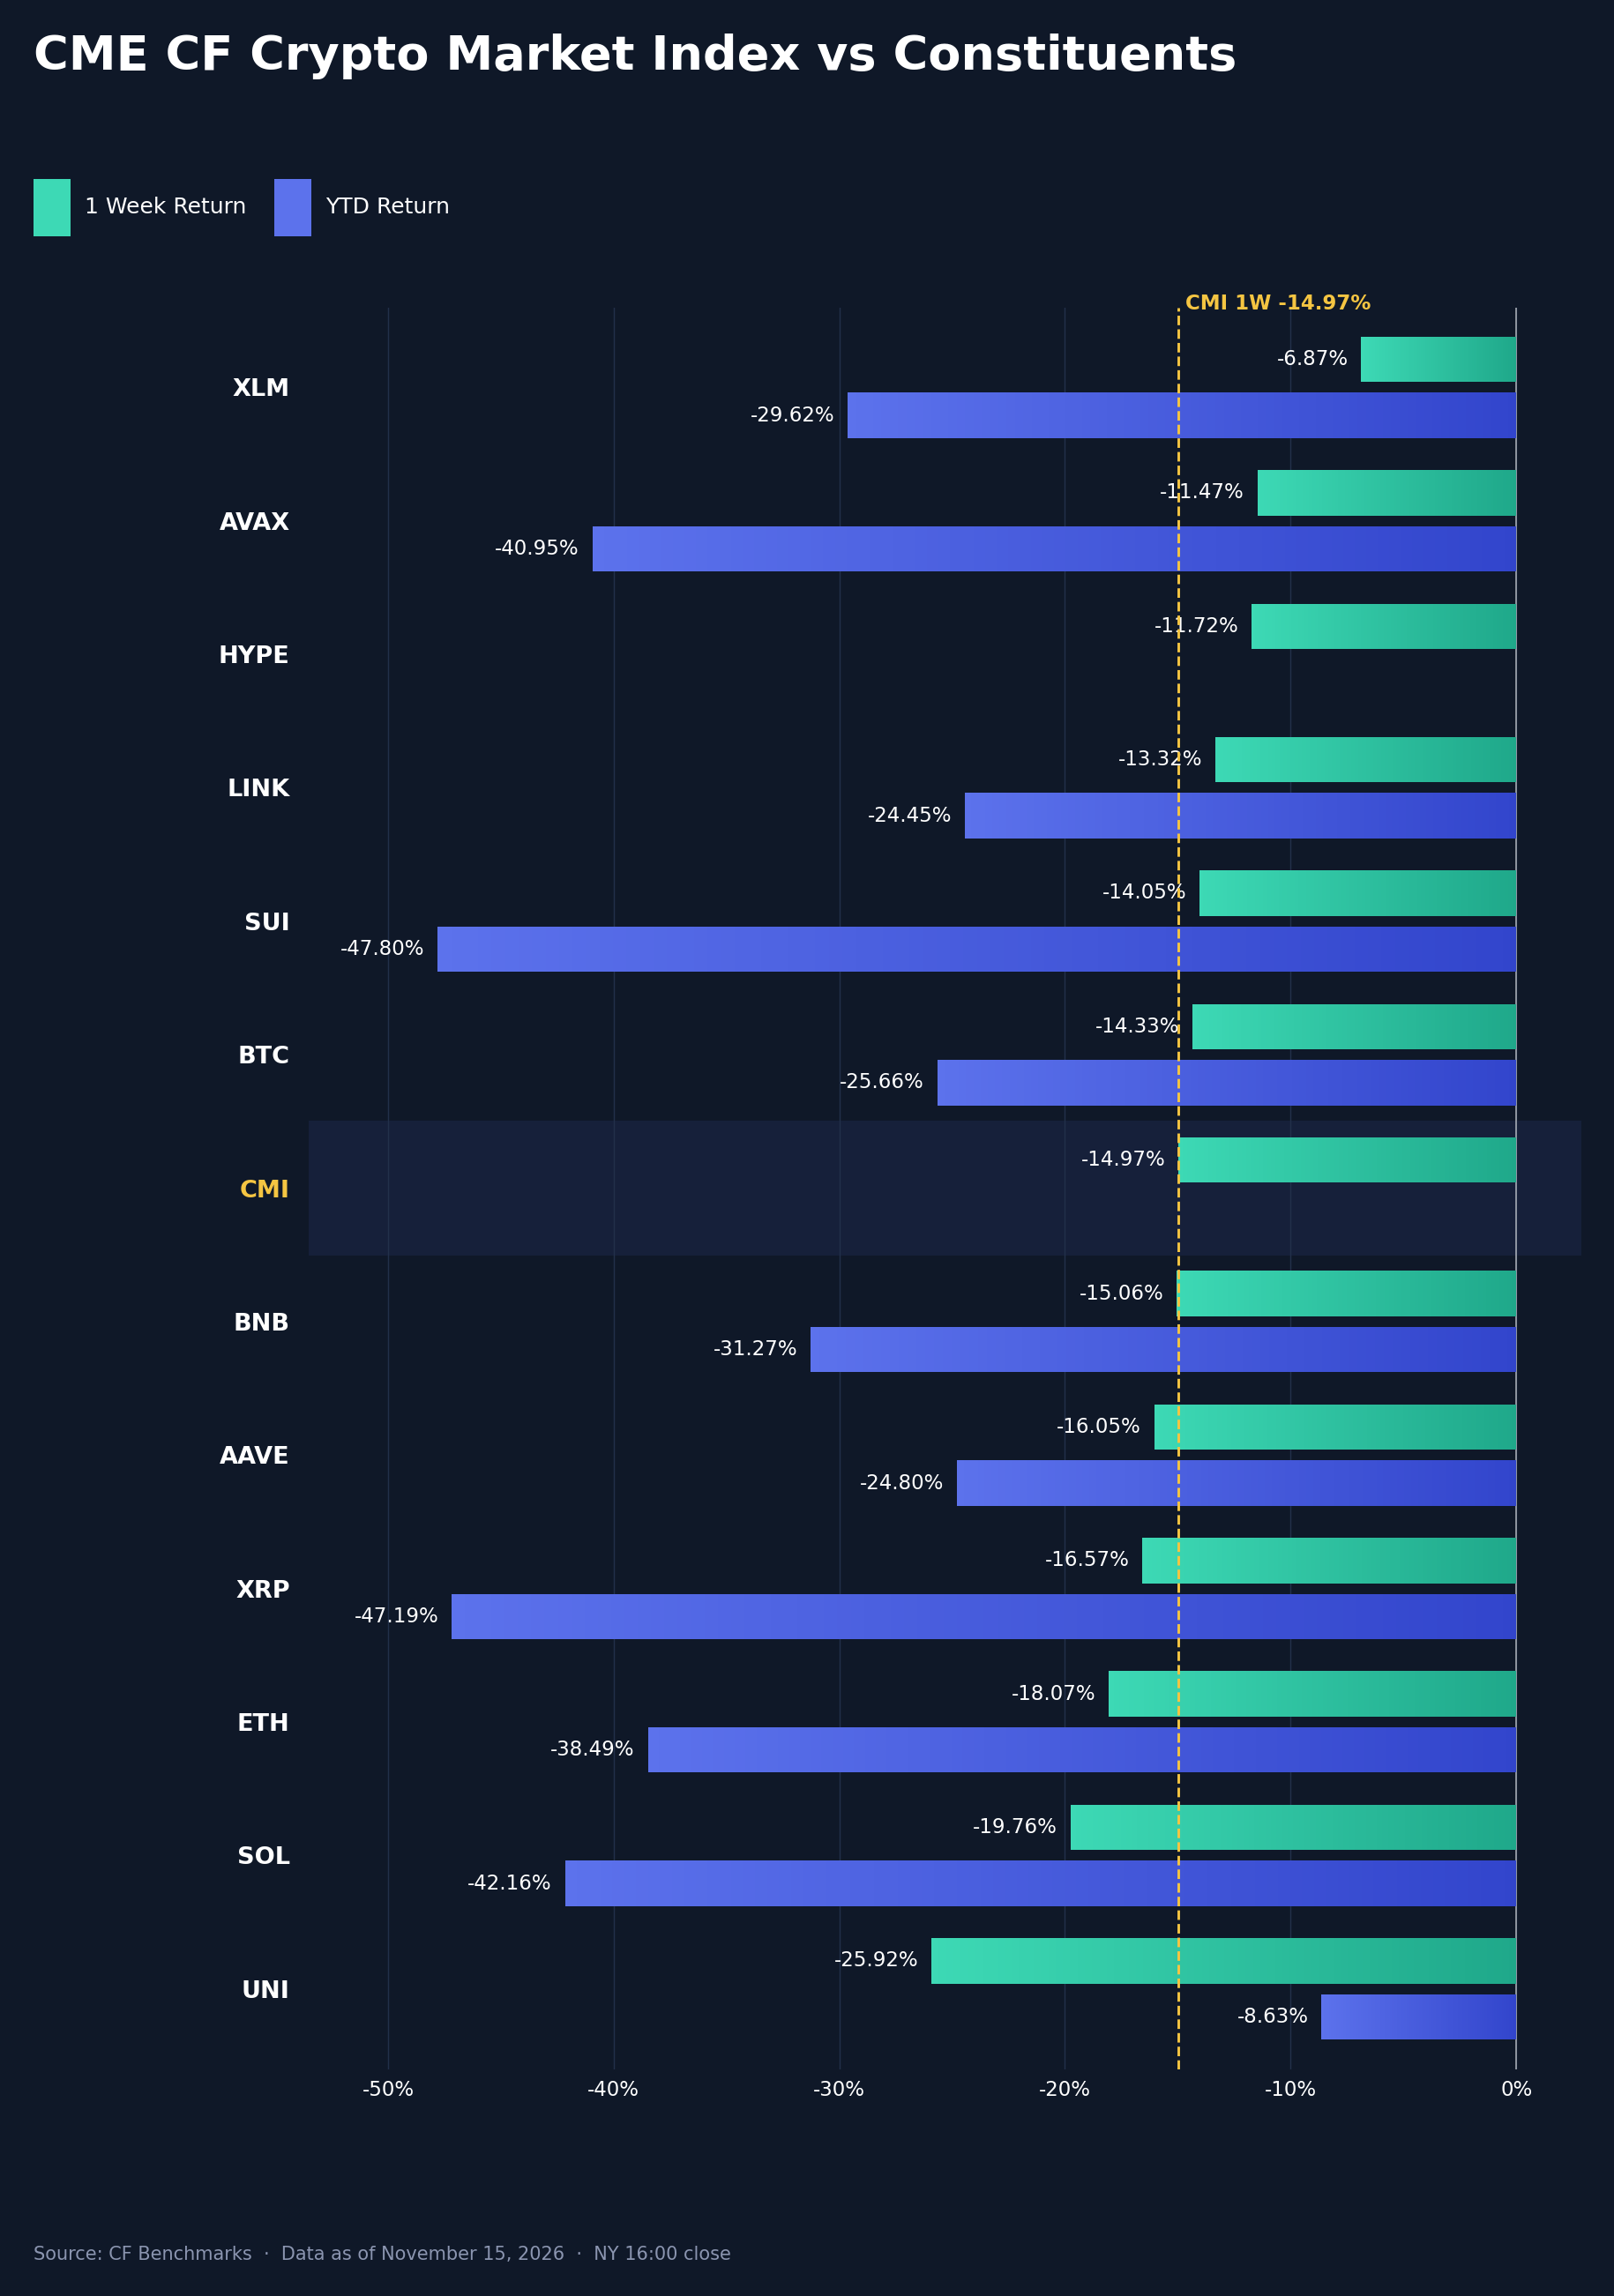
Digital assets fell in a late-week deleveraging. The CME CF Crypto Market Index (CMI) lost 14.97% week-on-week (w/w), most of it in a 12.44% decline from Wednesday's close to Saturday's. Bitcoin (BTC) closed below its 200-day moving average on Thursday, November 12th, for the first time since August 19th, and ended the week 13.4% below its 50-week average after eight straight Sunday closes above it. A hotter than expected October Consumer Price Index (CPI) and a 37 basis point (bps) rise in the 2-year Treasury yield set the backdrop, but the S&P 500 rose 2.51% despite these developments.
Market Performance Update
CMI fell 14.97% w/w from November 8th to November 15th, after a 2.97% decline a week earlier. It fell 1.86% on Monday and 2.09% on Tuesday, when October core CPI rose 0.3% month on month against a 0.2% consensus and the 2-year yield added 17 bps, then gained 1.29% on Wednesday. CMI fell 3.88% on Thursday, when BTC closed at $71,448, below its 200-day average of $73,073, and 3.11% on Friday, when about $1.3 billion of long positions were liquidated over 24 hours. Saturday brought the largest loss, 5.98% in a session with no macro release, as a weekend liquidation cascade of about $2.0 billion, 83% of it longs, got under way. BTC touched about $62,000 late on Saturday, after the fix, and closed Sunday at $64,907. Over the Friday-to-Friday window the S&P 500 rose 2.51% and the Nasdaq 100 3.53%. BTC fell 14.33%, 0.64 percentage points (pp) ahead of the market, and contributed 10.42pp of the decline, with the other eleven constituents subtracting 4.55pp, 2.00pp of it from Ether (ETH). Stellar (XLM) held up best at -6.87%, 8.10pp ahead, followed by Avalanche (AVAX) at +3.50pp, Hyperliquid (HYPE) at +3.25pp, Chainlink (LINK) at +1.65pp and Sui (SUI) at +0.92pp. BNB trailed by 0.09pp, Aave (AAVE) by 1.08pp, XRP by 1.60pp, ETH by 3.10pp at -18.07% and Solana (SOL) by 4.79pp at -19.76%. Uniswap (UNI) was weakest at -25.92%, 10.95pp behind, leaving a 19.05pp spread to XLM. On a year-to-date (YTD) basis BTC is down 25.66%, ETH 38.49% and XRP 47.19%, and UNI's 23.35% YTD gain of a week earlier has turned into an 8.63% loss. Spot Bitcoin ETFs redeemed $1.07 billion over the five sessions, extending outflows to seven straight sessions.
Volatility Analysis
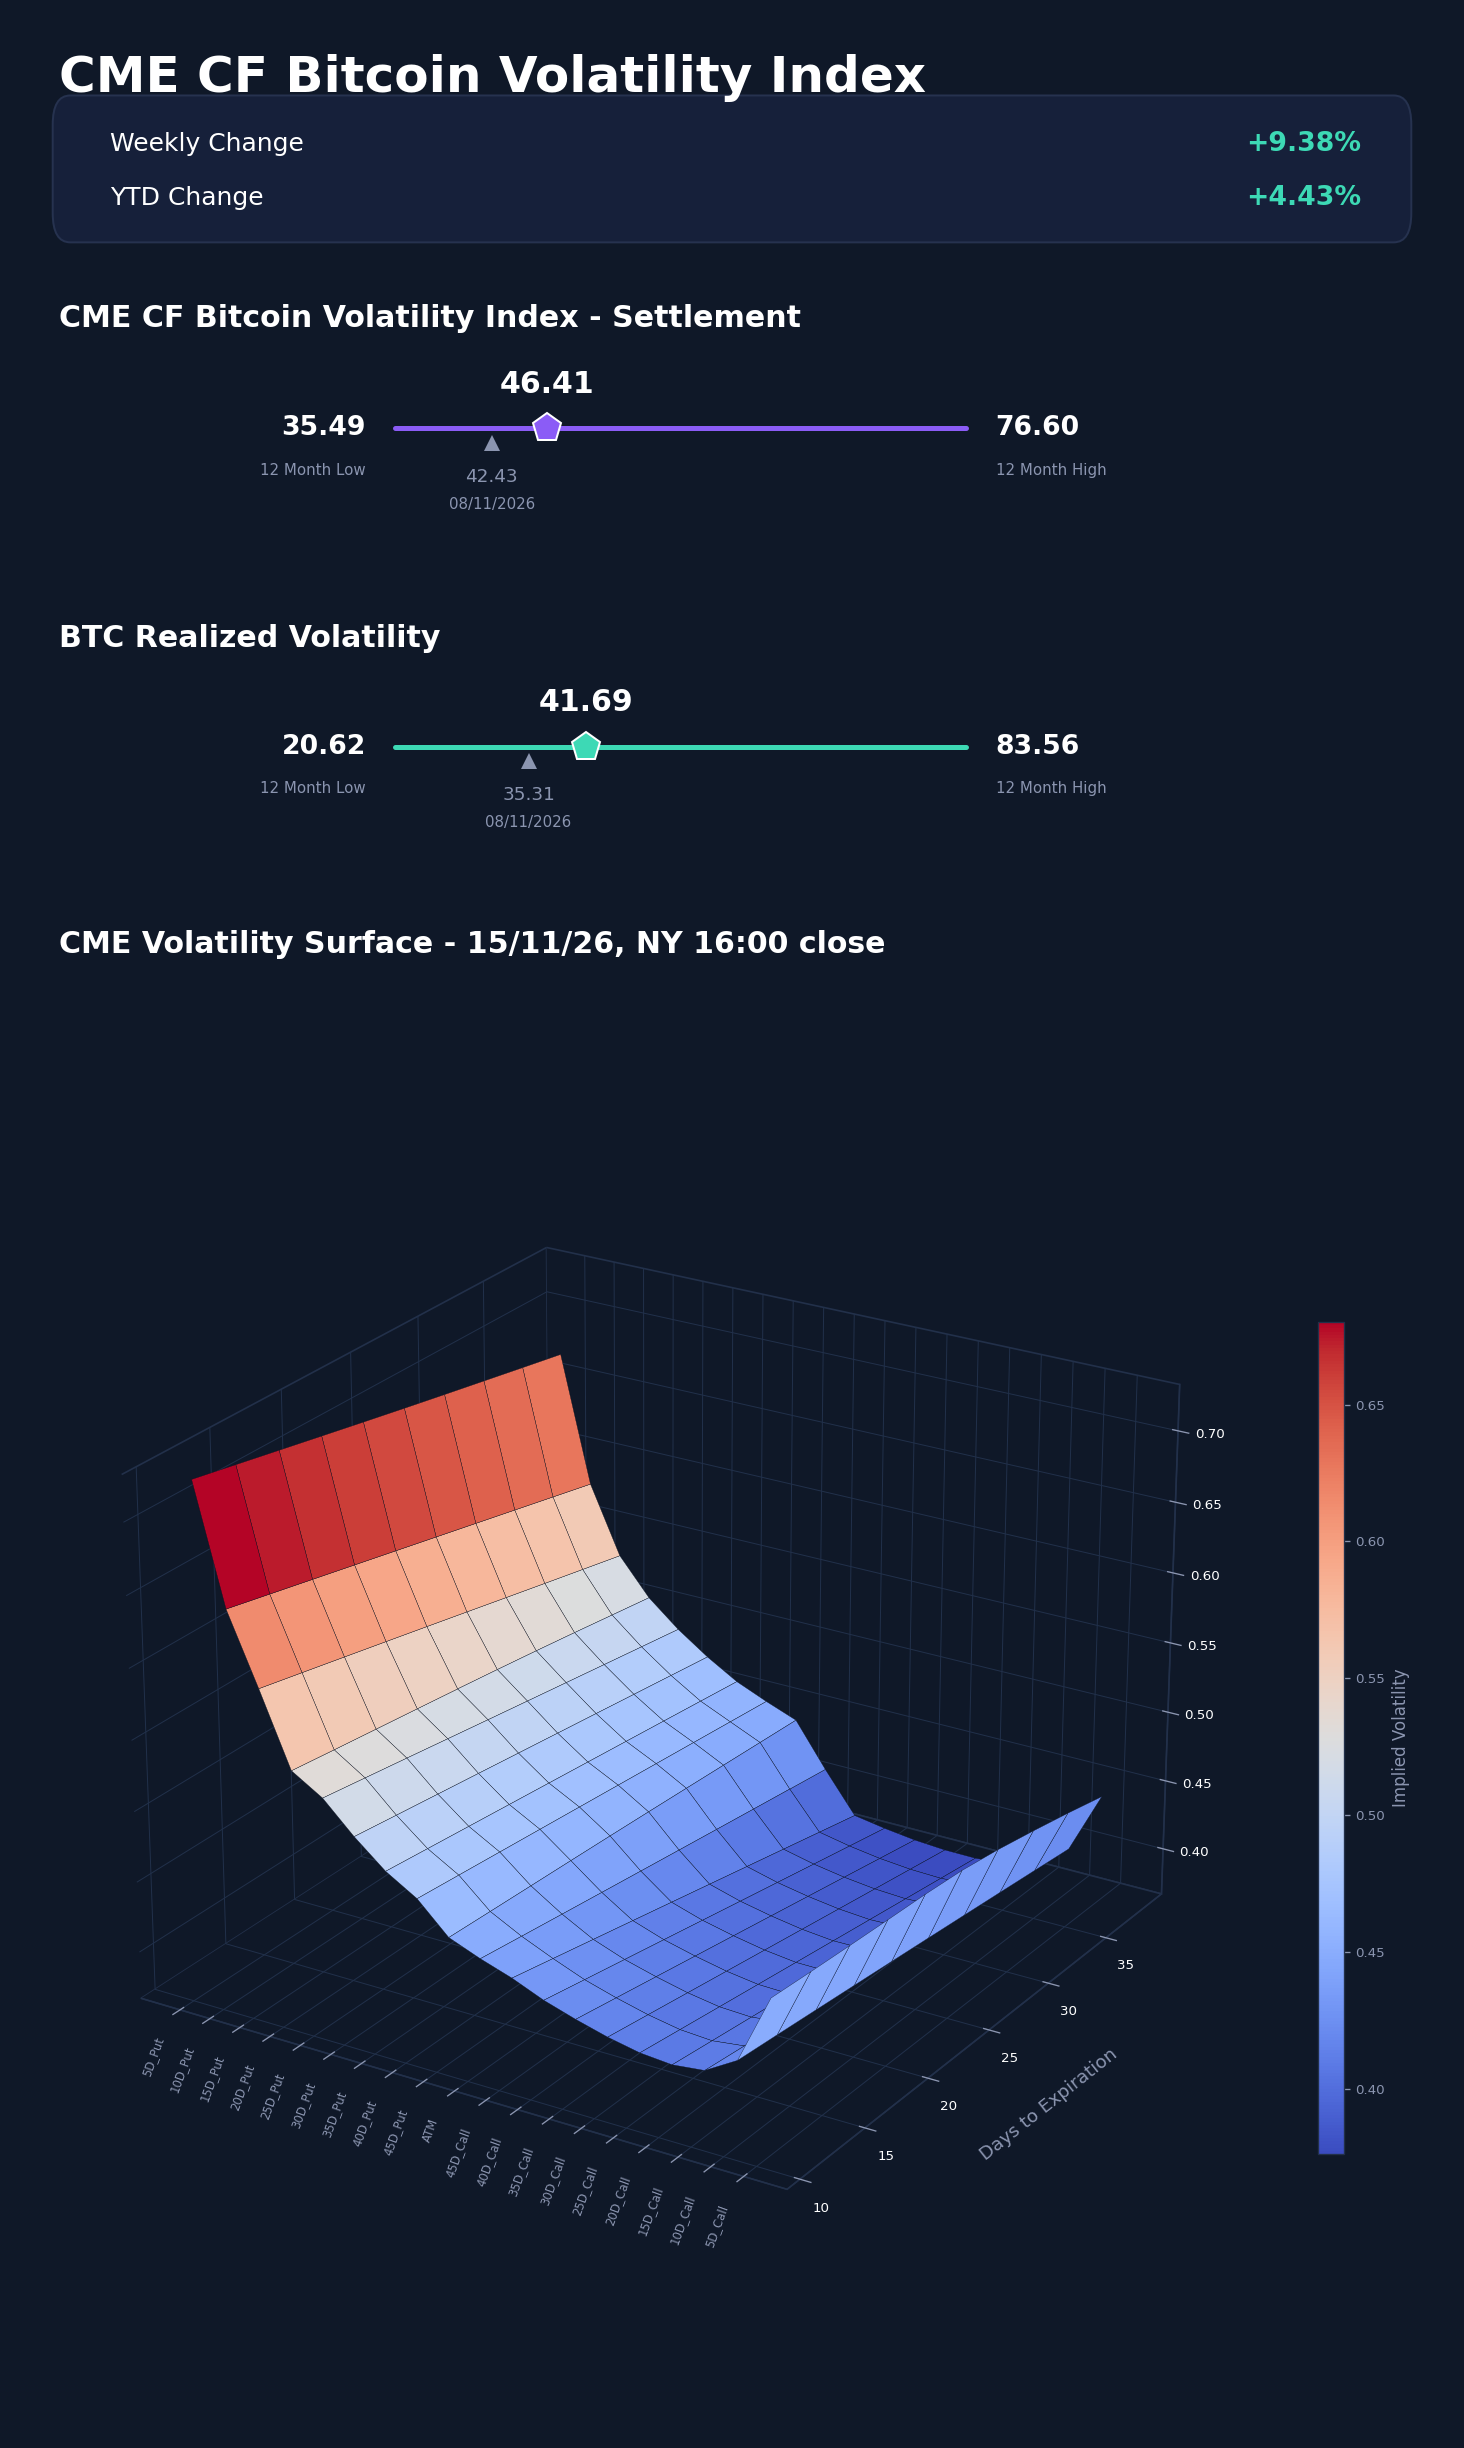
The CME CF Bitcoin Volatility Index Settlement (BVXS) rose 9.38% to 46.41 from 42.43, and most of the rise came late in the week. From Monday to Thursday it eased from 41.66 to 39.21, then rose to 43.11 on Friday and 47.98 on Saturday. Realized volatility rose faster. 30-day realized ended the week at 41.69 against 35.31, so the implied-realized spread narrowed to 4.72 vol points from 7.12 and options now price less of a premium over the moves BTC has made. BVXS sits 10.92 points above its 12-month low of 35.49, well below the 76.60 high, and is up 4.43% YTD from its 44.44 start-of-year reference. The surface priced more crash protection. At one month (30 days), at-the-money (ATM) implied volatility rose 2.26 points to 42.13, while the 5-delta put widened to 26.48 points over ATM from 20.57 and the 25-delta put skew to 7.86 from 4.83. The shortest tenor, 11 days, shows the same shape, with ATM at 44.63 and the 25-delta put 8.20 points over it.
Market Cap Index Performance
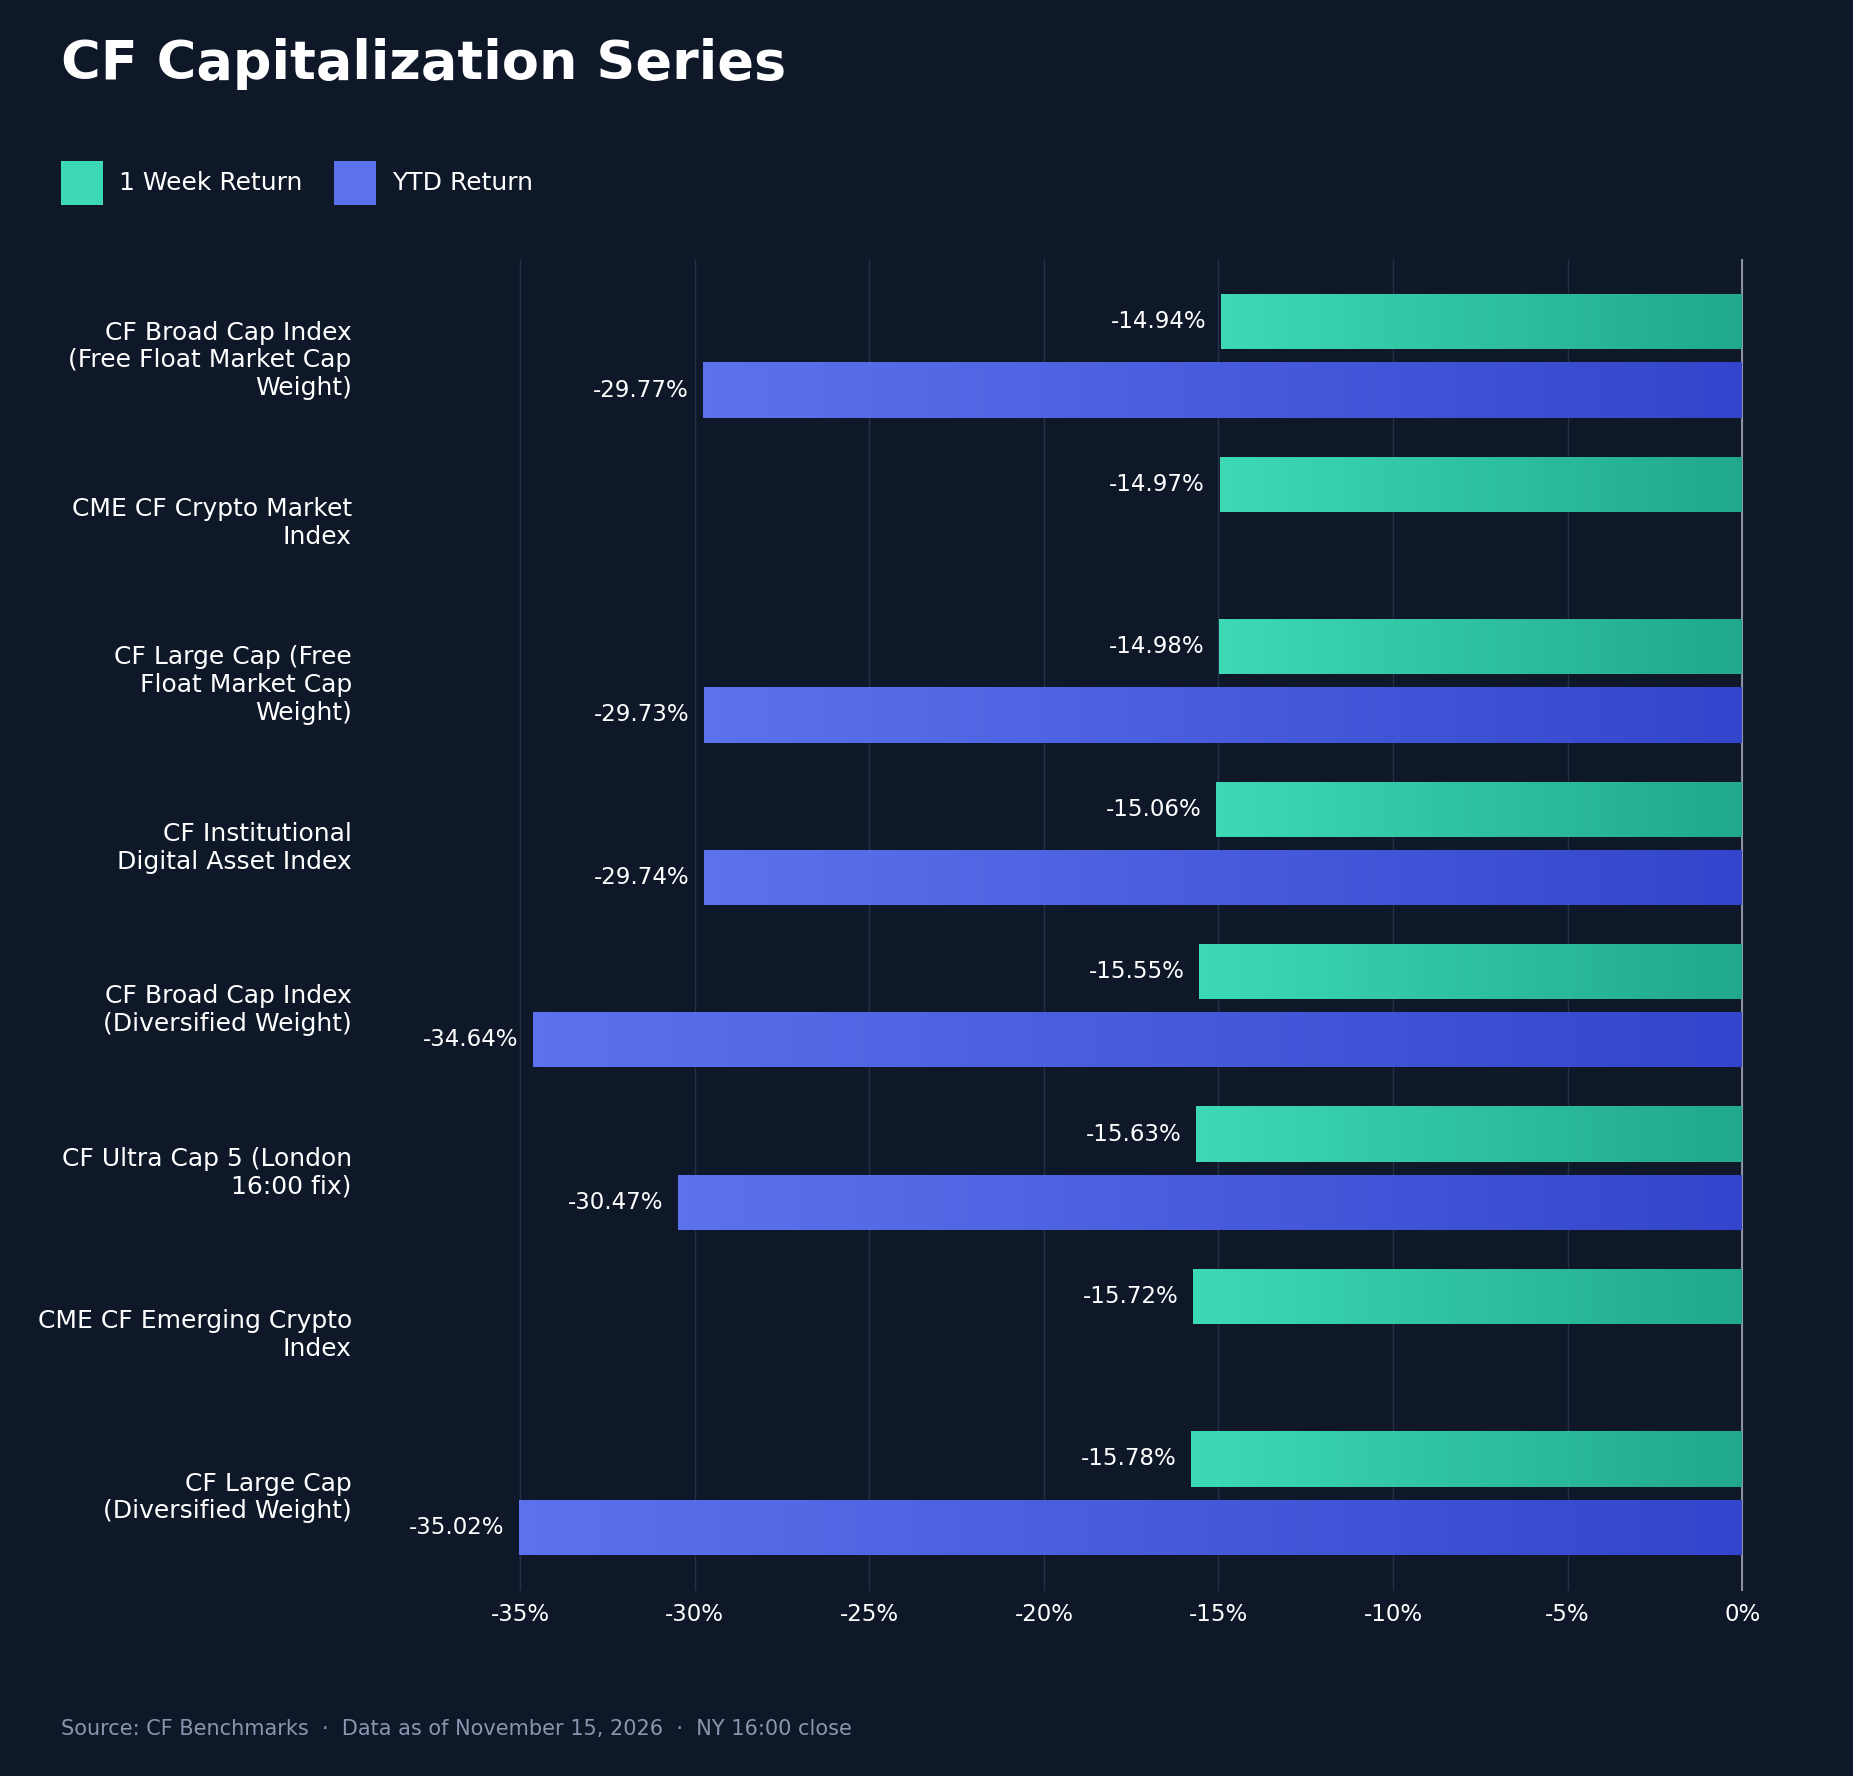
Every CF Capitalization Series index on the New York close fell between 14.94% and 15.78%, a 0.84pp range in a market down 15%, so size offered almost no shelter. CF Broad Cap (Free Float Market Cap Weight) held up best at -14.94%, followed by CMI at -14.97%, CF Large Cap (Free Float Market Cap Weight) at -14.98% and the CF Institutional Digital Asset Index at -15.06%. CF Broad Cap (Diversified Weight) fell 15.55%, the CME CF Emerging Crypto Index 15.72% and CF Large Cap (Diversified Weight) 15.78%. CF Ultra Cap 5 fell 15.63% on the London 16:00 fix and is not ranked against them. The diversified-versus-free-float gap (Broad Cap Diversified minus Large Cap Free Float) narrowed to -0.57pp from -1.53pp a week earlier. Comparing the two Broad Cap indices day by day, Broad Cap Diversified lagged Broad Cap Free Float on Monday and Tuesday and most of all on Saturday, when it fell 7.60% against 6.07%, and led on Thursday, Friday and Sunday. YTD, Large Cap Free Float is down 29.73% against 34.64% for Broad Cap Diversified. Saturday's liquidations hit smaller assets hardest, but over the full week leverage unwound across the whole market.
Factors Analysis
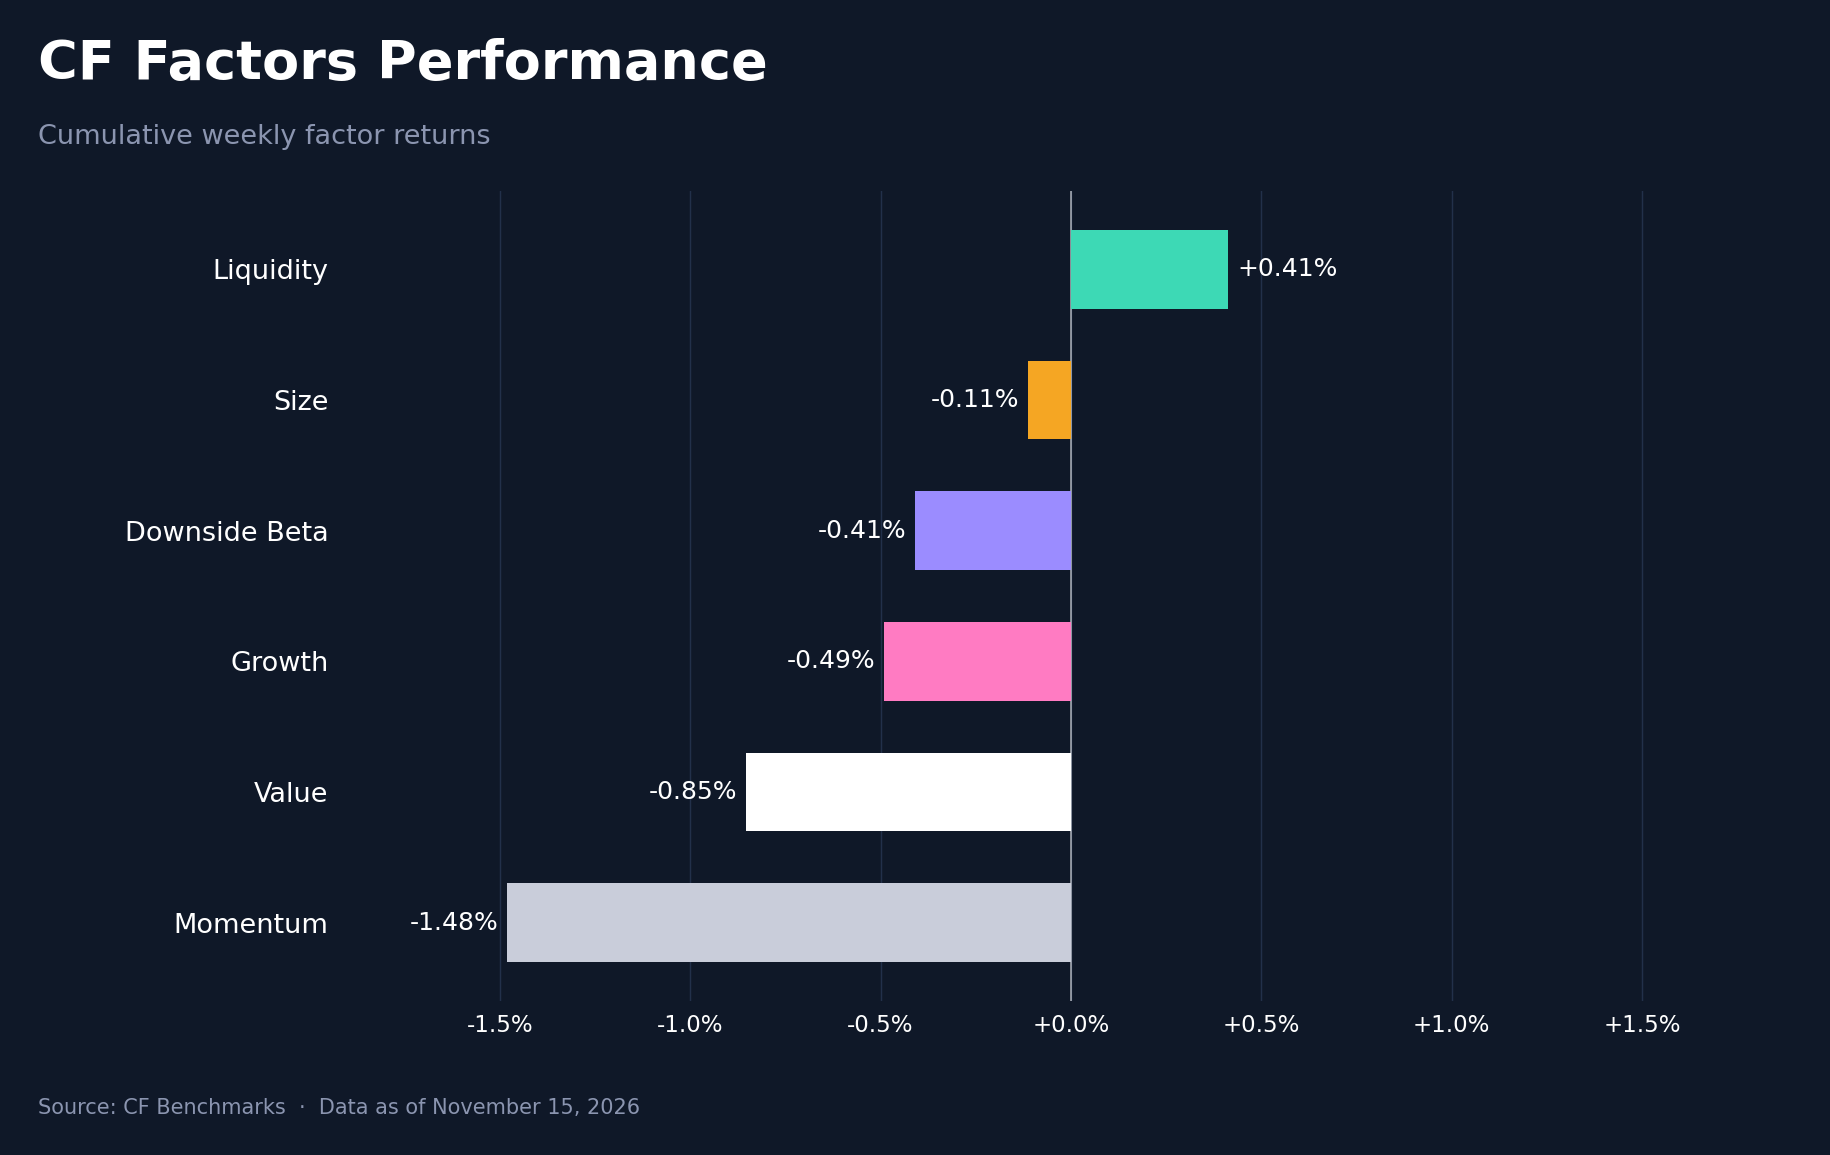
Dispersion across CF factor returns widened, with the weekly range rising to 1.89pp from 1.32pp. Liquidity led at +0.41%, the only gain, followed by Size at -0.11%, Downside Beta at -0.41% and Growth at -0.49%, while Value fell 0.85% and Momentum 1.48%. Momentum made the largest rotation, a 1.78pp swing from the prior week's +0.30%, Value reversed by 1.57pp from its +0.72% lead, and Liquidity improved by 0.95pp. On Thursday Liquidity gained 1.33% as less liquid assets held up better, while Size fell 0.75%, and Friday reversed both (Liquidity -0.90%, Size +0.83%). On Saturday Downside Beta gained 0.56% and Value fell 0.98%, so lower-downside-beta assets cushioned the liquidation session while value names did not. Momentum's losses came on four of the seven days, its largest a 0.91% decline on Wednesday, as recent winners gave back gains in a falling market.
Read our latest weekly crypto factors report: Factor Friday - November 13, 2026
Classification Series Analysis
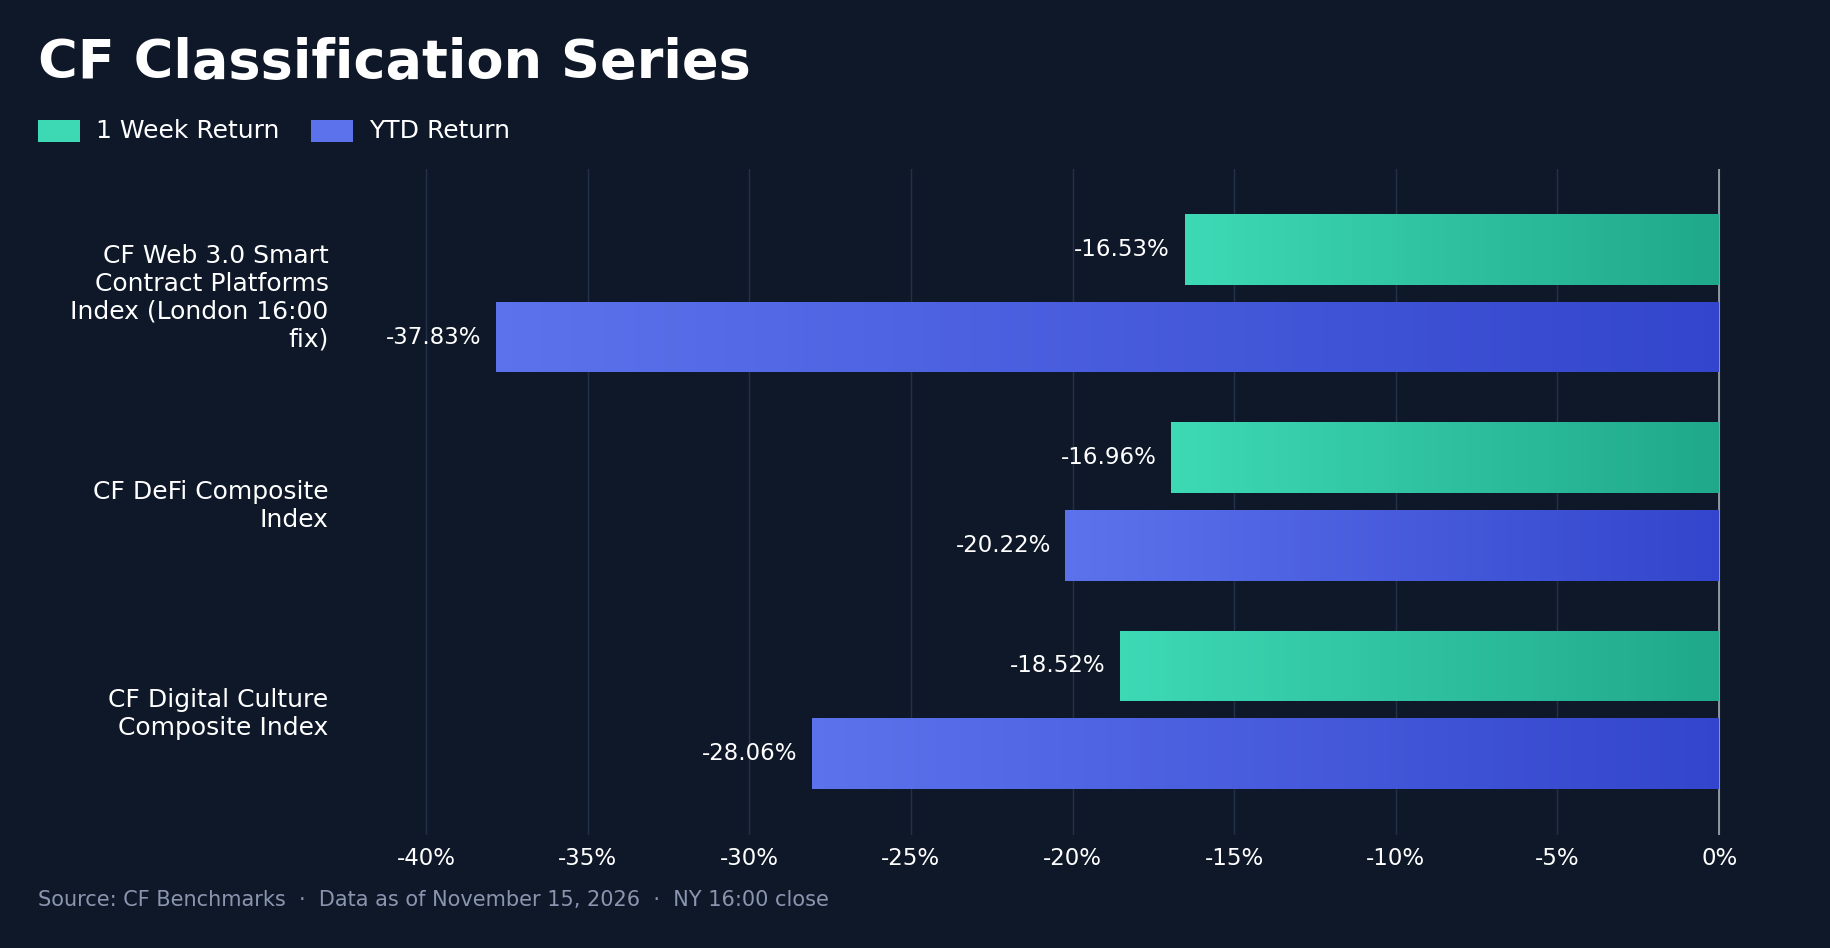
In the CF Classification Series, the CF DeFi Composite Index fell 16.96%, after a 5.57% decline a week earlier, and the CF Digital Culture Composite Index fell 18.52% after a 6.71% drop. DeFi's lead widened to 1.56pp from 1.14pp. The CF Web 3.0 Smart Contract Platforms Index fell 16.53% on the London 16:00 fix and is not compared with the two New York-close composites. YTD, DeFi is down 20.22%, Digital Culture 28.06% and the Smart Contract Platforms Index 37.83%. The largest constituents set the pace. UNI, 19.1% of the DeFi Composite at the November 8th fix, fell 25.92%, and Basic Attention Token (BAT), 24.9% of Digital Culture, fell 21.92%.
Sector Analysis
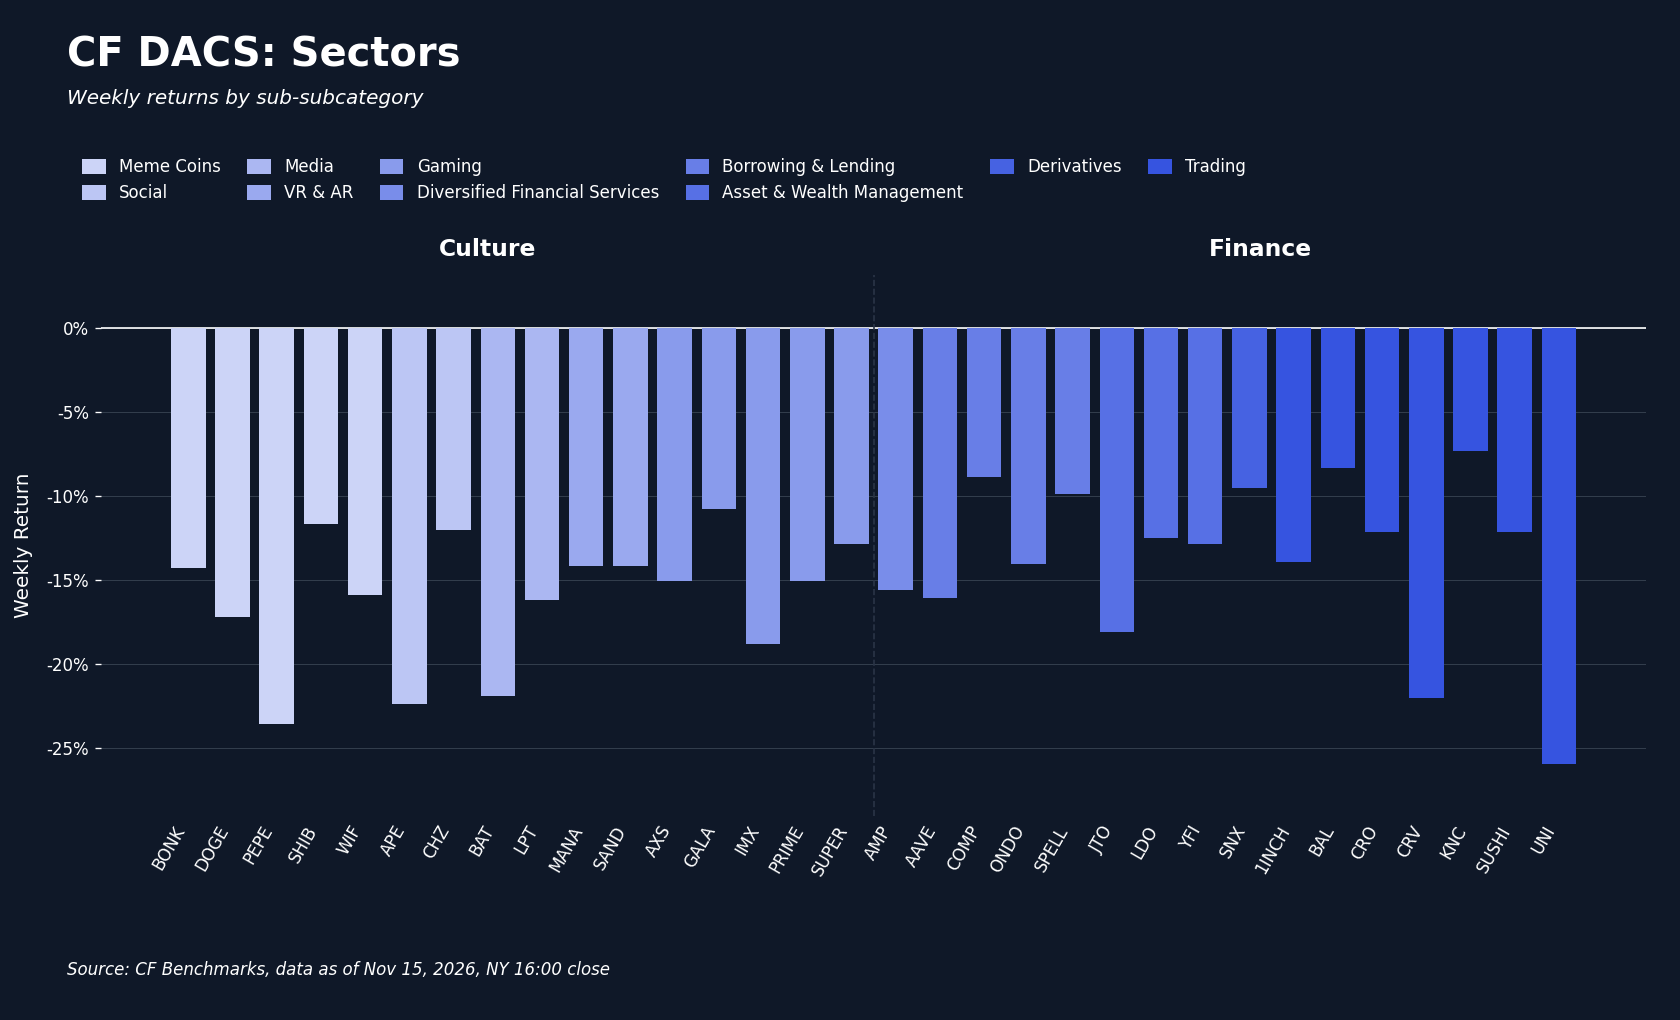
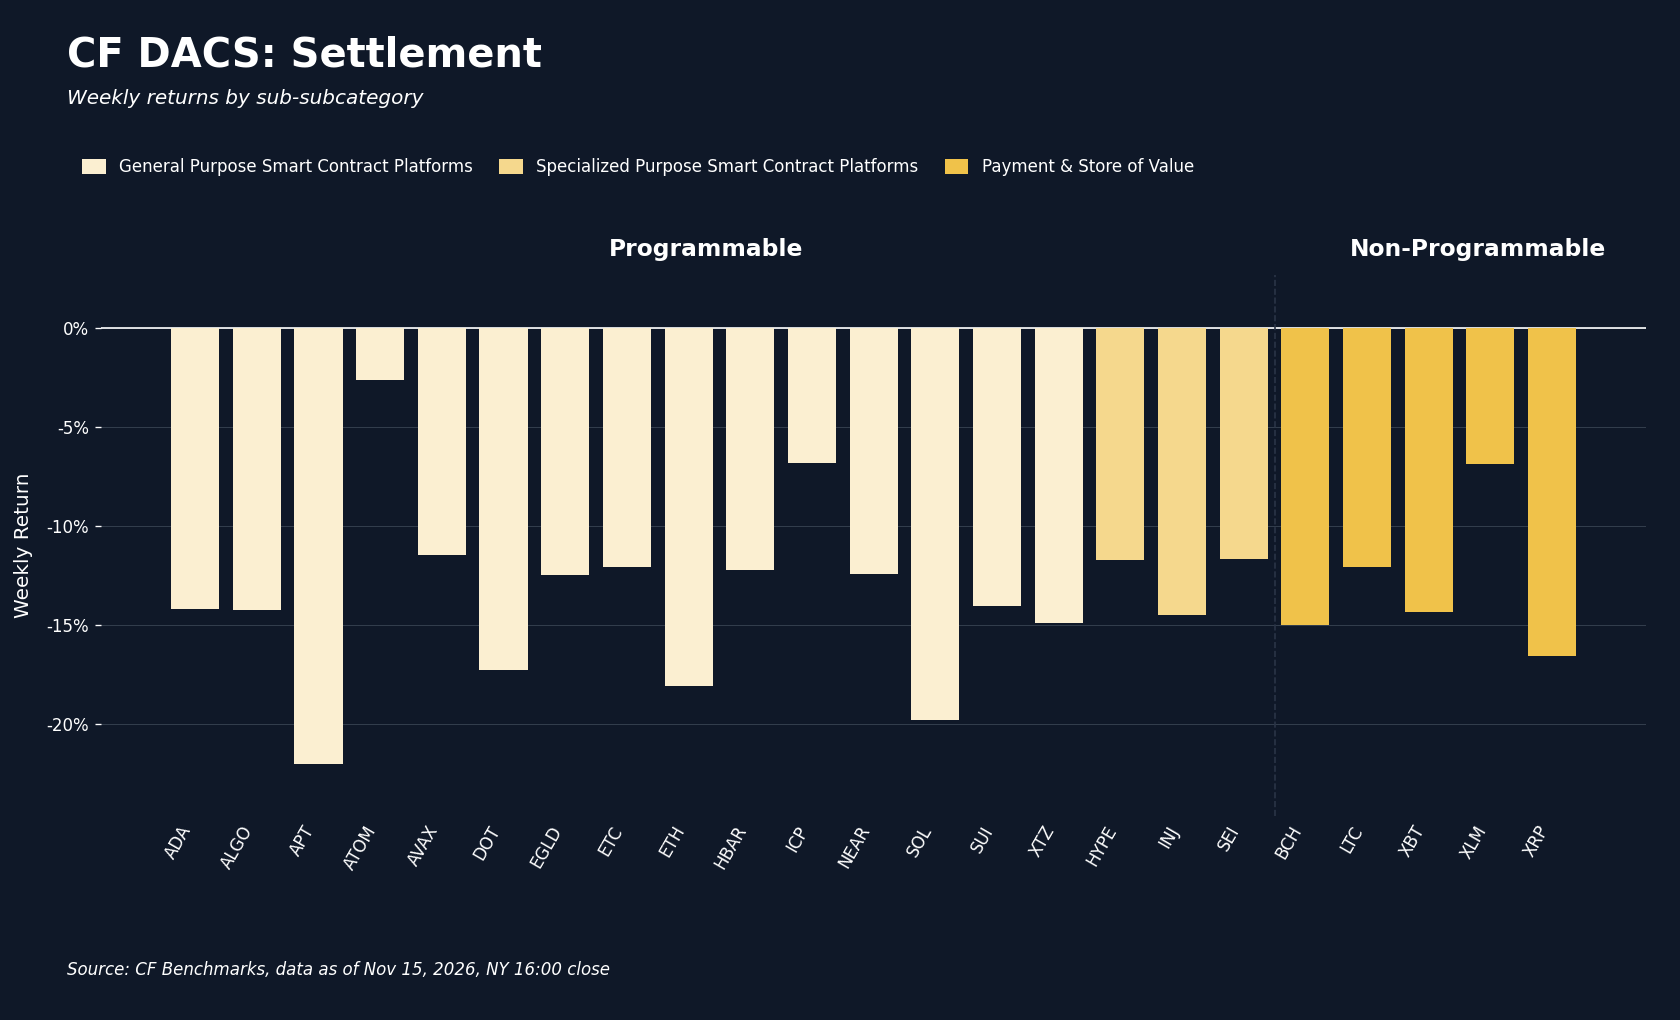
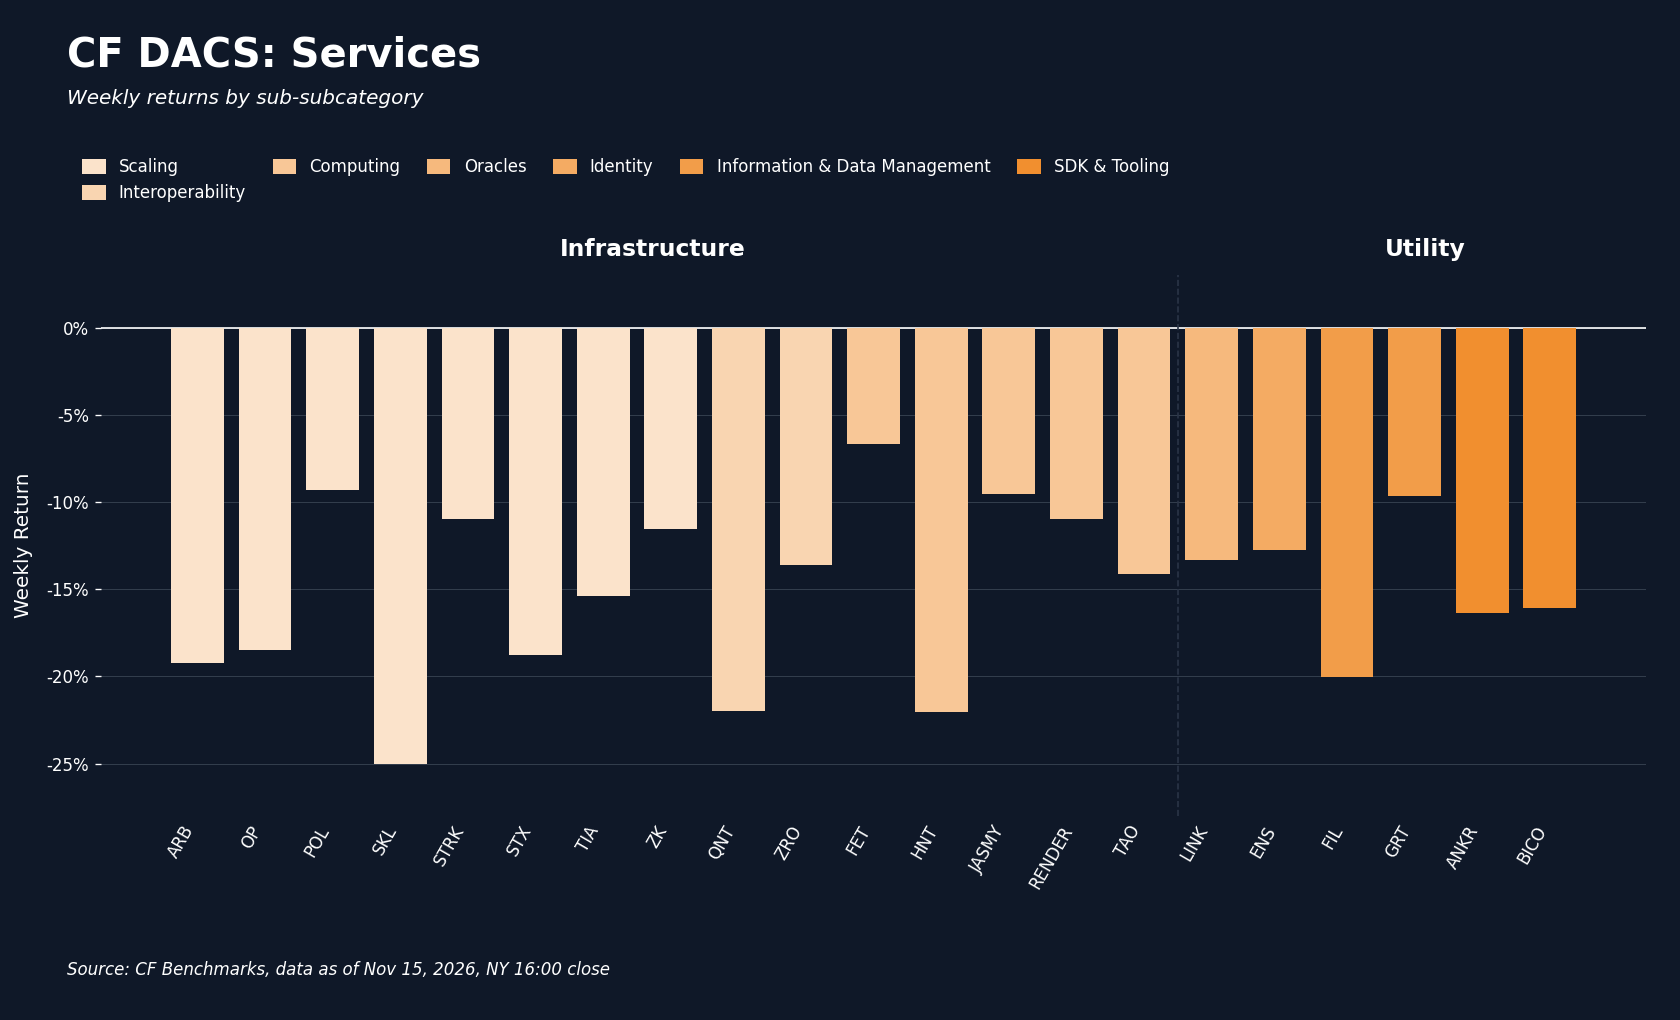
Every CF DACS sub-category average fell, and none of the 76 constituents with a weekly return finished higher. Non-Programmable fell least, at -12.97%, as XLM's -6.87% offset XRP's -16.57%, followed by Programmable at -13.46% and Finance at -13.70%. Utility fell 14.70%, Infrastructure 15.18% and Culture was weakest at -16.02%. The week's clearest industry catalyst sat in Programmable. On Monday, November 9th, Ava Labs announced that the New York Stock Exchange had selected Avalanche as the clearing and settlement ledger for its planned around-the-clock tokenized-stock platform, a launch still subject to regulatory approval. AVAX rose 5.44% that day and was up 4.99% through Wednesday's close, then fell 12.76% on Saturday with the rest of the market and finished at -11.47%, 1.99pp ahead of the Programmable average and third of 18 in the sub-category. Cosmos (ATOM) led all constituents at -2.65% and Internet Computer (ICP) fell 6.83%, while Aptos (APT, -21.98%), SOL and ETH trailed the sub-category. In Finance, Jito (JTO, -18.06%) and Curve (CRV, -22.01%) joined UNI at the bottom. In Infrastructure, Fetch.ai (FET) fell 6.68%, while SKALE (SKL, -25.00%), Helium (HNT, -22.05%), Quant (QNT, -22.00%) and Arbitrum (ARB, -19.22%) lagged. In Utility, The Graph (GRT, -9.68%) led and Filecoin (FIL, -20.04%) trailed. The widest token-level spread, ATOM against UNI, was 23.28pp.
CF Staking Series
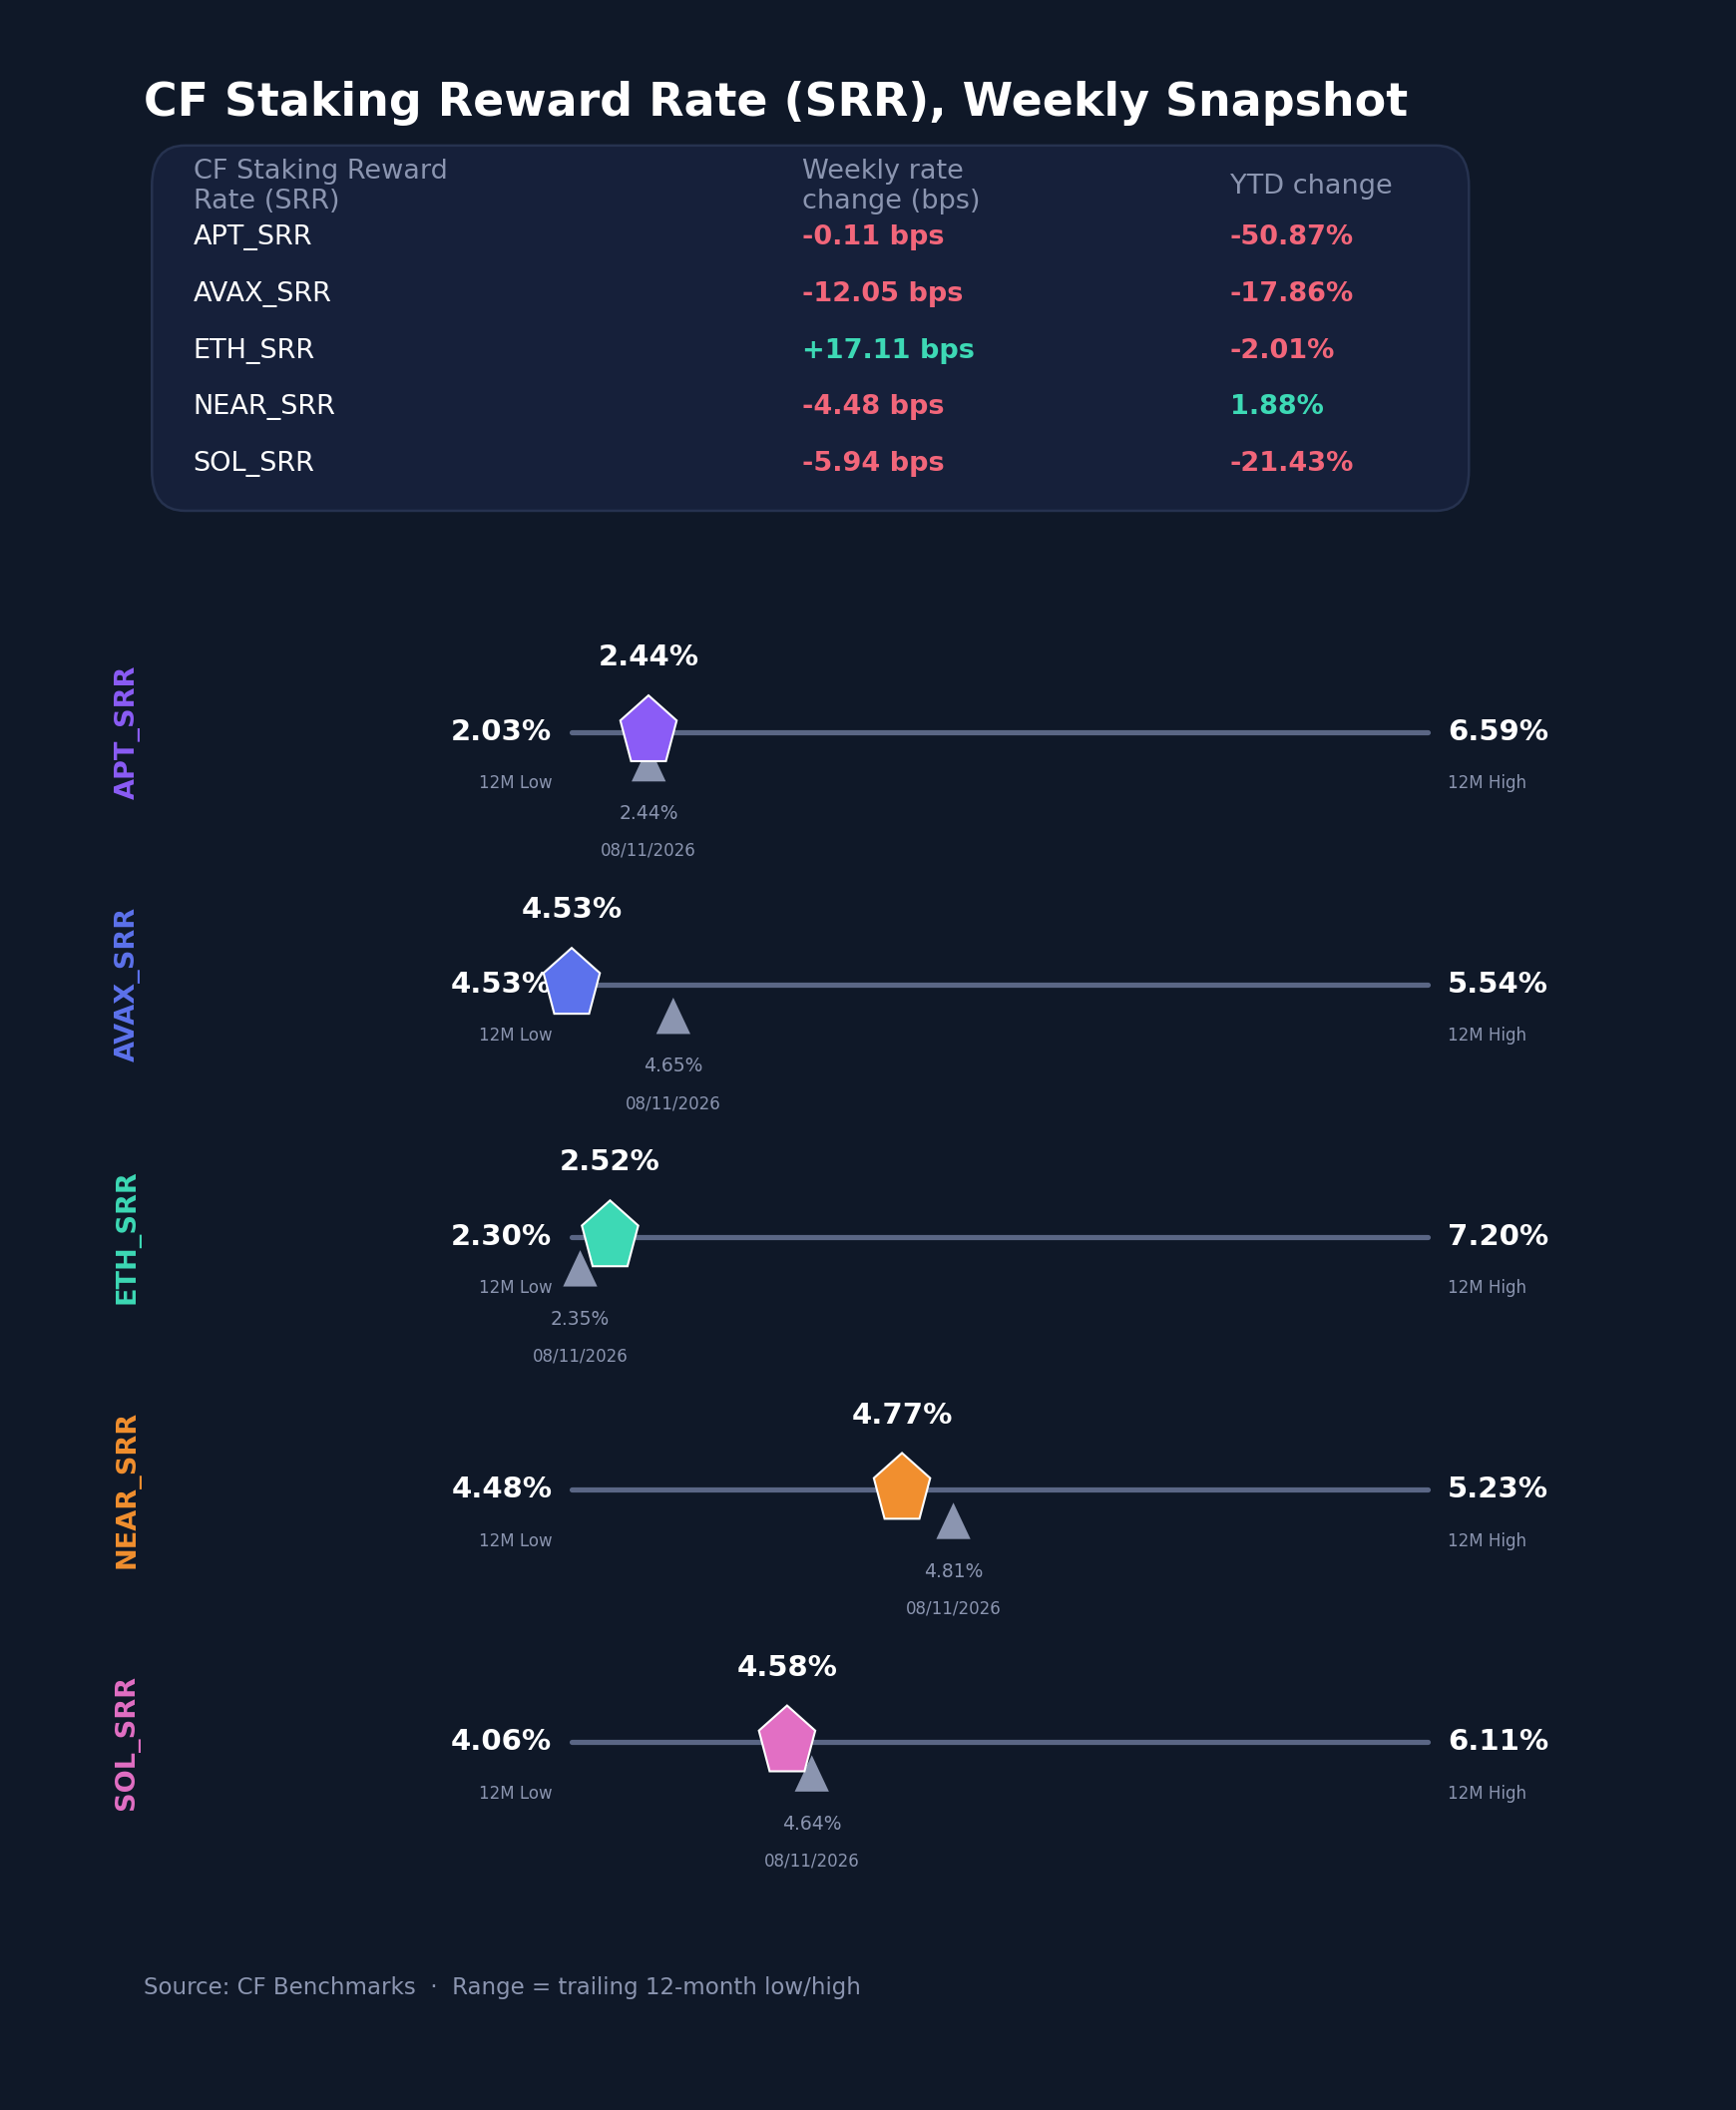
ETH's was the only reward rate in the CF Staking Series to rise. The ETH rate rose 17.1 bps to 2.5169% from 2.3458%, a 7.29% relative index gain, after peaking at 2.9190% on November 14th, a print that reflects the prior day's priority fees and coincided with Friday's liquidations. AVAX fell 12.1 bps to 4.5278% from 4.6483%, setting a new 12-month low on each of the week's seven daily prints. SOL slipped 5.9 bps to 4.5761%, NEAR Protocol (NEAR) 4.5 bps to 4.7700% and APT 0.1 bps to 2.4381%. That leaves a 2.33pp range between APT at the bottom of the set and NEAR at the top, against 2.47pp a week earlier. YTD, the NEAR rate index is up 1.88% and the ETH index down 2.01%, while APT's is down 50.87%. Outside ETH, no rate moved more than 12.1 bps in a week when the market fell 15%.
Bitcoin Basis Analysis
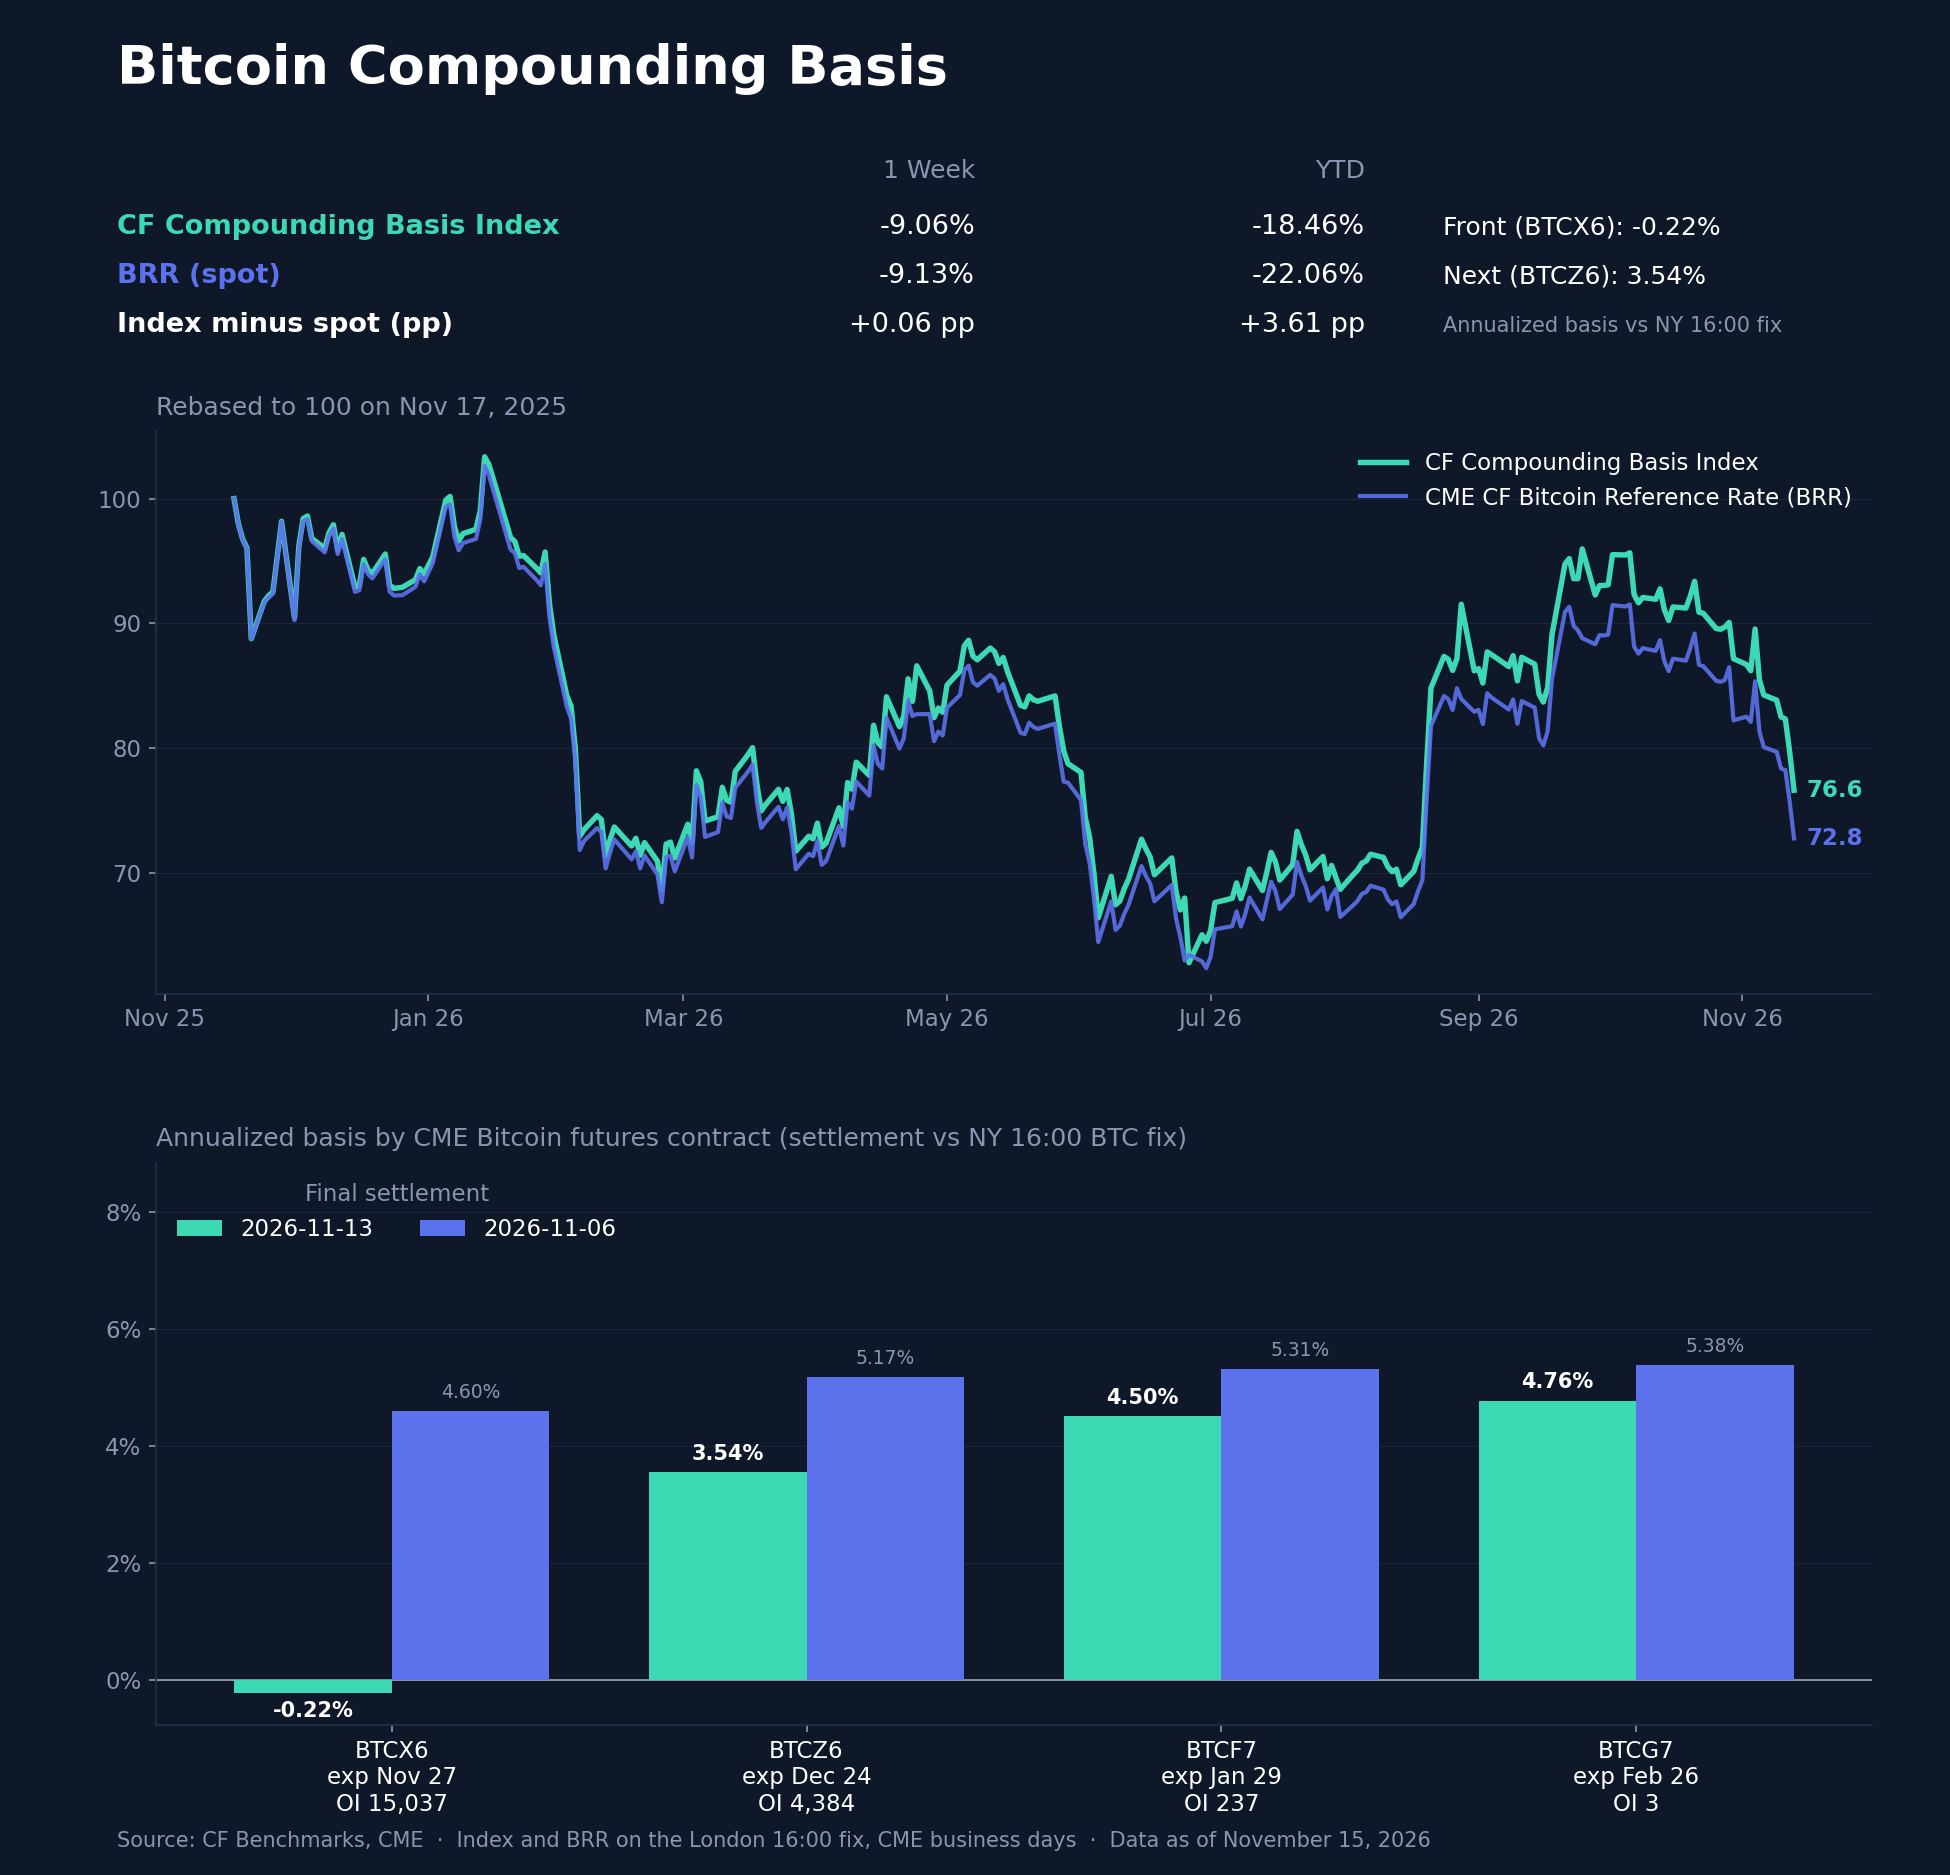
CME futures premiums eased across the curve. The CF Compounding Basis Index fell 9.06% from November 6th to November 13th against a 9.13% decline in the CME CF Bitcoin Reference Rate (BRR), so the basis added 0.06pp, and the index leads spot by 3.61pp YTD. Both print on the London 16:00 fix and are not compared with the New York close used elsewhere. At Friday's settlement, annualized basis against the New York fix moved to a 0.22% discount on the November contract (BTCX6) from a 4.60% premium, and fell to 3.54% from 5.17% on December (BTCZ6), 4.50% from 5.31% on January (BTCF7) and 4.76% from 5.38% on February (BTCG7). Each contract's premium to the New York fix fell by a similar 0.27pp to 0.28pp of spot, and the carry implied along the curve held near 5.5% annualized, so the larger annualized move at the front reflects BTCX6's 14 days to expiry rather than a flatter curve. BTCX6, where 15,037 contracts of open interest sit, settled $6 below the fix.
Closing Synthesis
Crypto sold off on its own this week. A hotter CPI print and higher yields set the backdrop, and equities rose through them while CMI lost 14.97%, most of it between Thursday and Saturday as BTC lost its 200-day and 50-week averages and weekend liquidations forced out long positions. The selling was broad, with a 0.84pp range across the capitalization indices and no DACS constituent higher, and the NYSE selection of Avalanche, the week's one industry catalyst, had faded by Saturday. The options surface priced more crash protection and CME premiums eased evenly across the curve. We read the week as a deleveraging driven from within crypto, with BTC ending it 11.0% below its 200-day average.
The information contained within is for educational and informational purposes ONLY. It is not intended nor should it be considered an invitation or inducement to buy or sell any of the underlying instruments cited including but not limited to cryptoassets, financial instruments or any instruments that reference any index provided by CF Benchmarks Ltd. This communication is not intended to persuade or incite you to buy or sell security or securities noted within. Any commentary provided is the opinion of the author and should not be considered a personalised recommendation. Please contact your financial adviser or professional before making an investment decision.
Note: Some of the underlying instruments cited within this material may be restricted to certain customer categories in certain jurisdictions.
Crypto Falls Following Hot CPI
Digital assets sold off on their own this week as equities rallied through hotter inflation and higher yields. The selling was broad and leverage-driven: weekend liquidations hit smaller assets hardest, demand for crash protection rose and futures premiums eased across the curve.
Mark Pilipczuk
Nasdaq Crypto Index Family - Reconstitution Announcement
The Calculation Agent announces that the reconstitution of the Nasdaq Crypto Index Family will take place on December 1st 2026.
CF Benchmarks
CME CF Crypto Market Index and CME CF Emerging Market Index Reconstitution Announcement
The Administrator announces that the Reconstitution of the CME CF Crypto Market Index and CME CF Emerging Market Index will take place on December 1st 2026.
CF Benchmarks
By clicking Accept, you consent to CF Benchmarks's use of cookies.
Visit Cookie Settings to learn how CF Benchmarks uses cookies and to adjust your preferences.