
Sep 28, 2026
Bitcoin ETFs See Inflows as Yields Climb
Weekly Index Highlights, September 28, 2026
A weekend short squeeze opened a broad digital asset rally that held through a hawkish repricing in rates. Bitcoin (BTC) rose 6.30% between September 20th and September 21st, a move that coincided with $647.9 million of short liquidations over the 24 hours to Monday morning and lower oil prices after President Trump said on Sunday that he was willing to meet Iran's president at the United Nations. The backdrop then tightened: flash purchasing managers' indices (PMIs) beat consensus on September 23rd, Governor Barr said further rate increases were likely in his base case, and the 10-year Treasury yield reached its highest level since 2007 midweek. BTC gave back part of its gain but finished the week up 5.22% week-on-week (w/w). US spot Bitcoin exchange-traded funds (ETFs) took in $2.39 billion over five sessions, including $999.0 million on Monday, the largest daily inflow of 2026, turning their year-to-date (YTD) flows positive. Quant (QNT) rose 161.95% after The Clearing House selected Quant on September 24th to provide the interoperability layer for its tokenized-deposit network. All eight CF Capitalization Series indices advanced, diversified indices beat their free-float counterparts, and Infrastructure led the CF Digital Asset Classification Structure (DACS) sub-category averages.
Market Performance Update
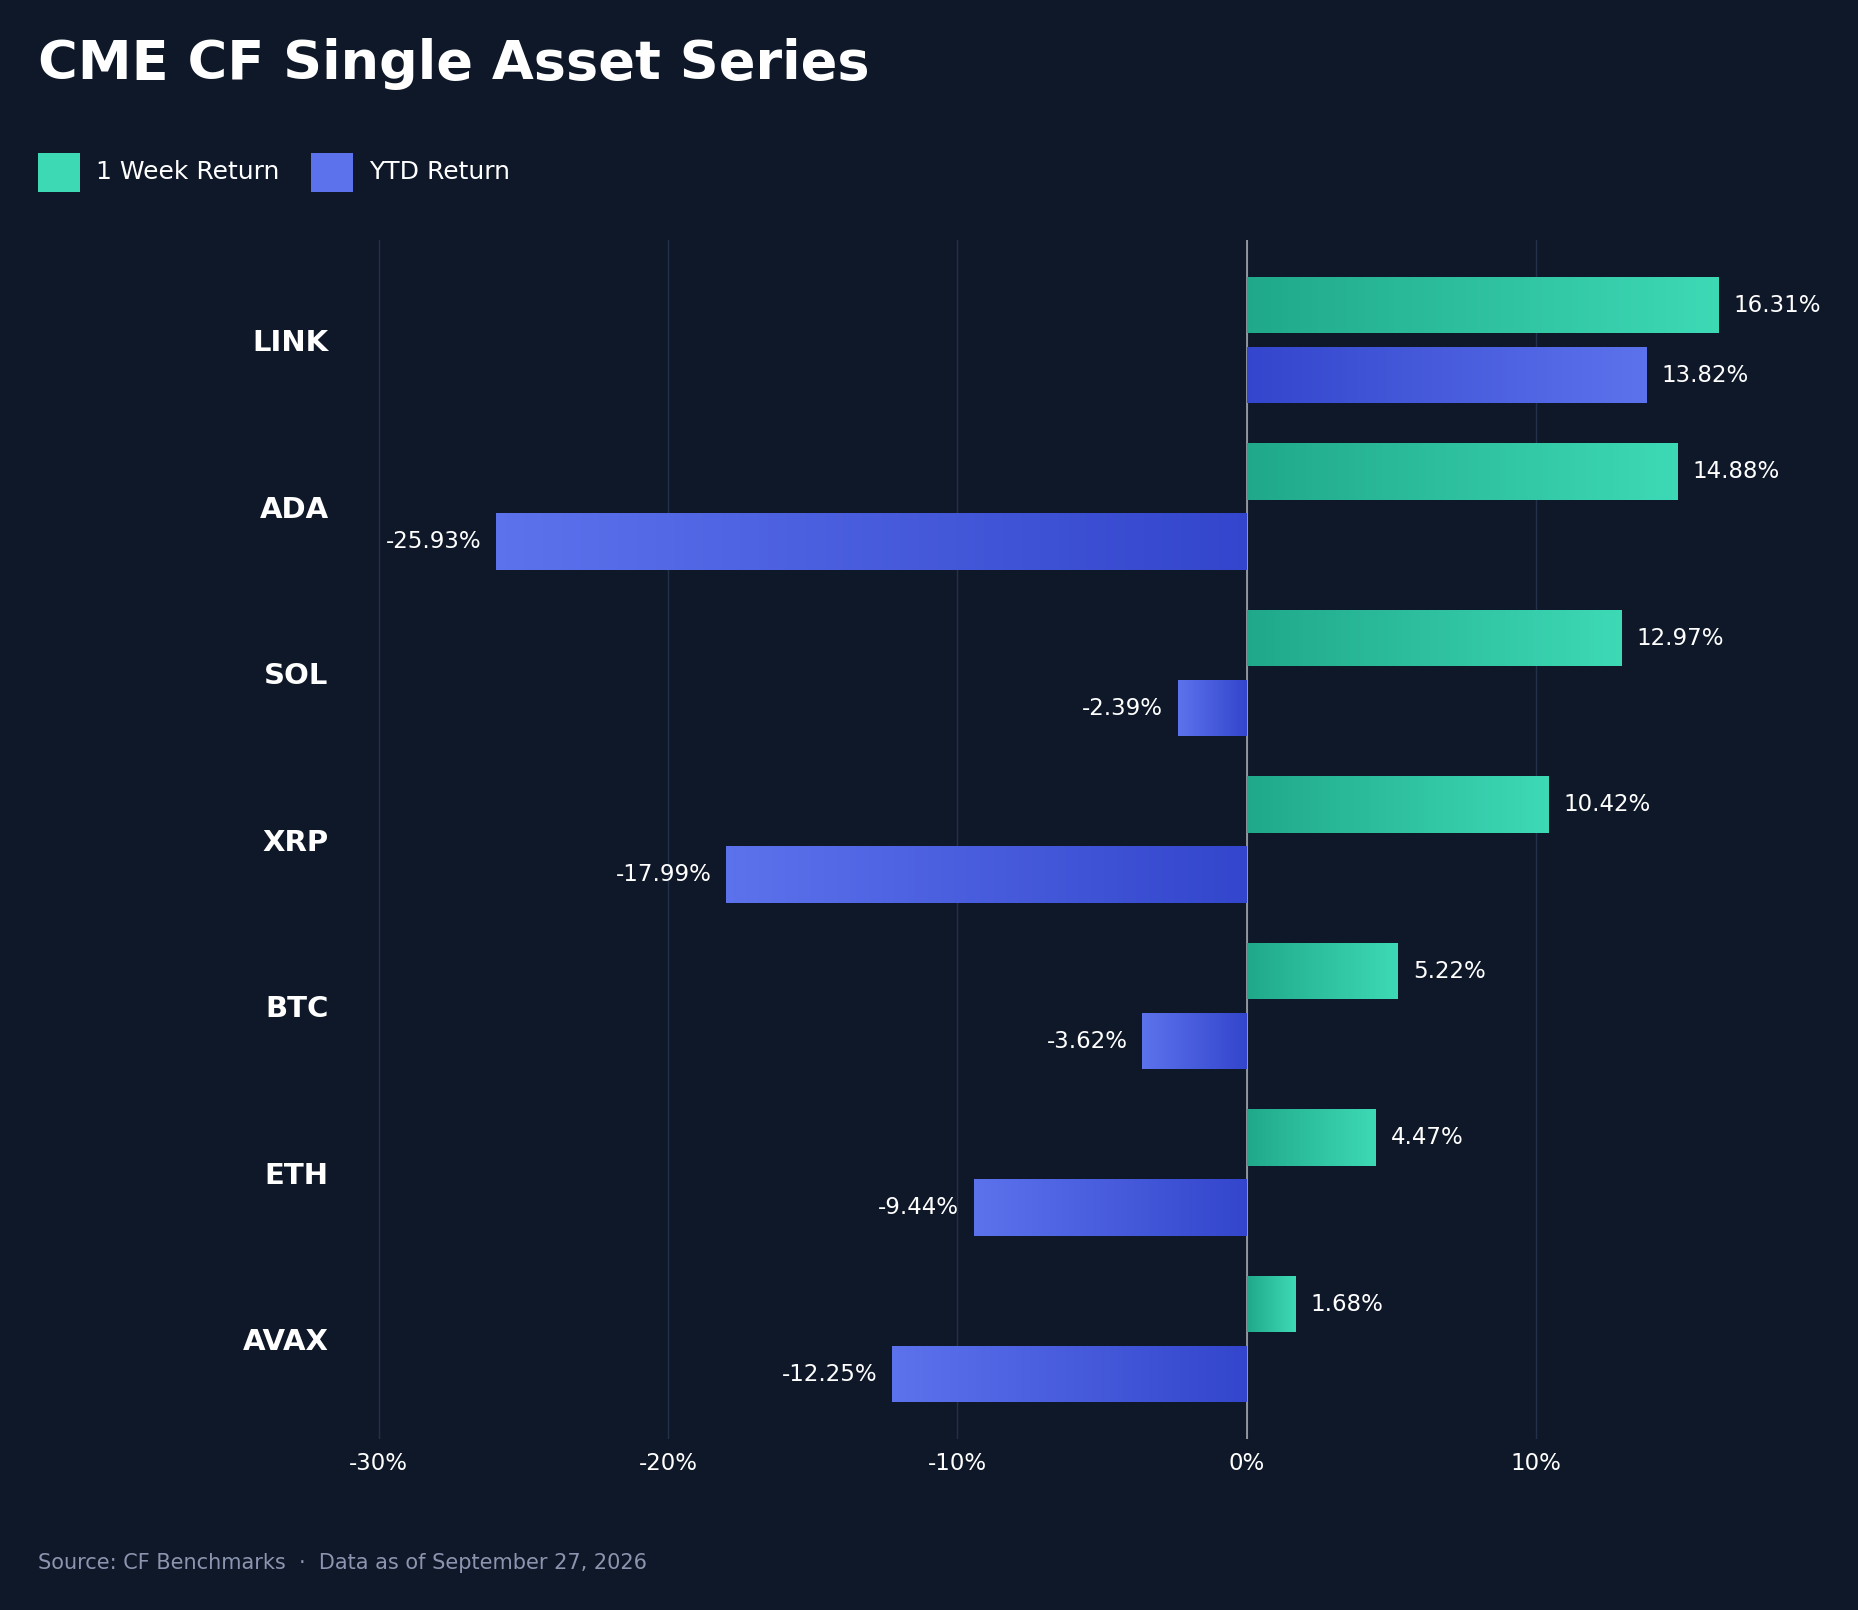
All seven CF Single Asset Series constituents advanced between the September 20th and September 27th fixes, with BTC's gain concentrated in the Sunday-to-Monday session. Chainlink (LINK) led at +16.31% w/w and moved into positive YTD territory at +13.82% from -2.14%. Cardano (ADA) rose 14.88% (YTD -25.93%), Solana (SOL) 12.97% (YTD -2.39%) and XRP 10.42% (YTD -17.99%). BTC gained 5.22% (YTD -3.62%), Ether (ETH) 4.47% (YTD -9.44%) and Avalanche (AVAX) 1.68% (YTD -12.25%), a week after AVAX led the set at +45.41%. The 14.63 percentage point (pp) range between LINK and AVAX compared with 43.07 pp a week earlier. BTC fell back from above $87,000 on Wednesday, coinciding with the flash PMI beat and Governor Barr's comments, although spot BTC ETFs absorbed inflows on every session. The two largest assets trailed LINK, ADA, SOL and XRP by between 5.20 pp and 11.84 pp, a crypto-specific rotation toward higher-beta networks rather than a uniform response to rates.
Volatility Analysis
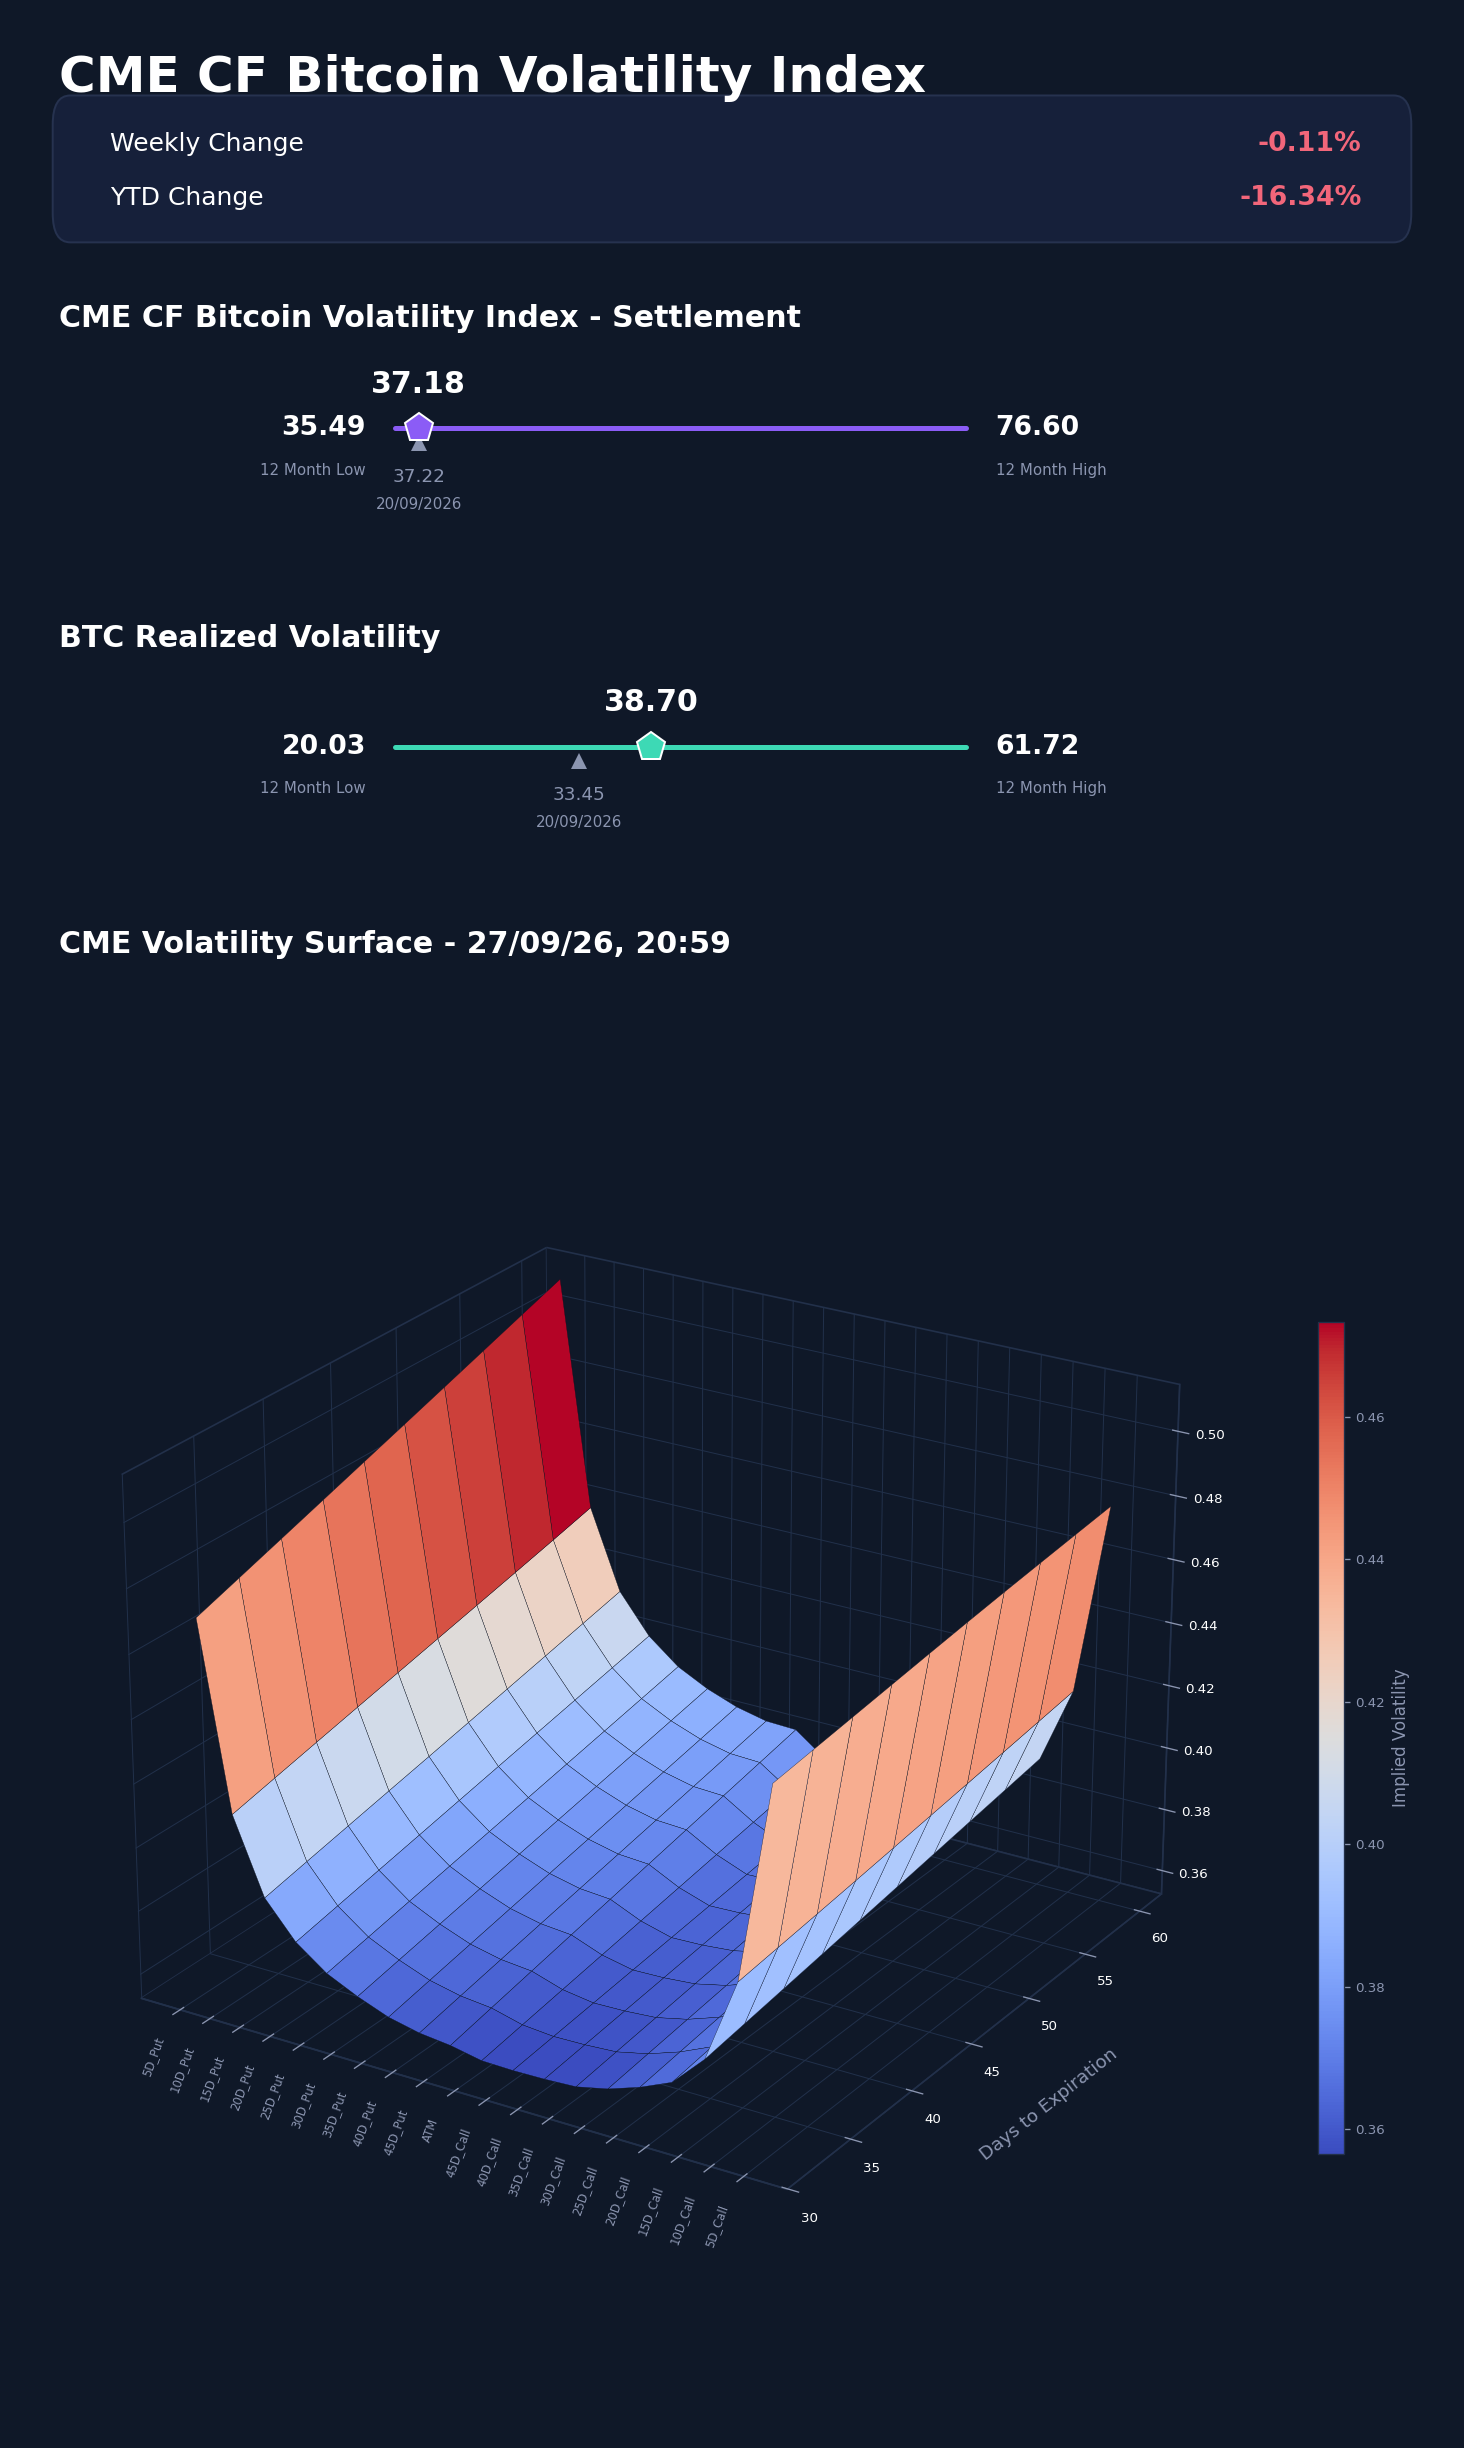
The CME CF Bitcoin Volatility Index Settlement (BVXS) finished September 27th at 37.18, little changed from 37.22 a week earlier, a 0.11% w/w decline. The flat endpoint masked an intraweek round trip: BVXS rose to 40.35 on Monday alongside the weekend spot advance, then eased on each of the next three sessions to 36.70 on Thursday before finishing Friday at 36.89. Thirty-day realized volatility rose to 38.70 from 33.45 as the Monday move entered the trailing window, turning the implied-minus-realized spread to -1.52 vol. points from +3.77. BVXS remained 1.69 vol. points above its trailing 12-month low of 35.49, within a 35.49-to-76.60 range, and 16.34% below the 44.44 start-of-year reference. Realized volatility sat in the lower half of its 20.03-to-61.72 range. On the surface, the shortest available tenor is now 32 days after the September 25th quarterly expiry rolled off, which allows a close maturity match with the prior snapshot's 31-day row. At-the-money implied volatility was 35.58 against 35.10, the 5-delta put 46.94 against 48.06, and the 25-delta put premium over at-the-money 1.34 vol. points against 1.31. The exhibit uses the 20:59 Sunday capture, the only weekend snapshot to pass the standing skew checks; its front row agrees with the standard 15:59 capture to within 0.02 vol. points at-the-money. Implied volatility compressed through the week while realized volatility caught up to the week's opening spot move, leaving options priced slightly below recent realized movement.
Market Cap Index Performance
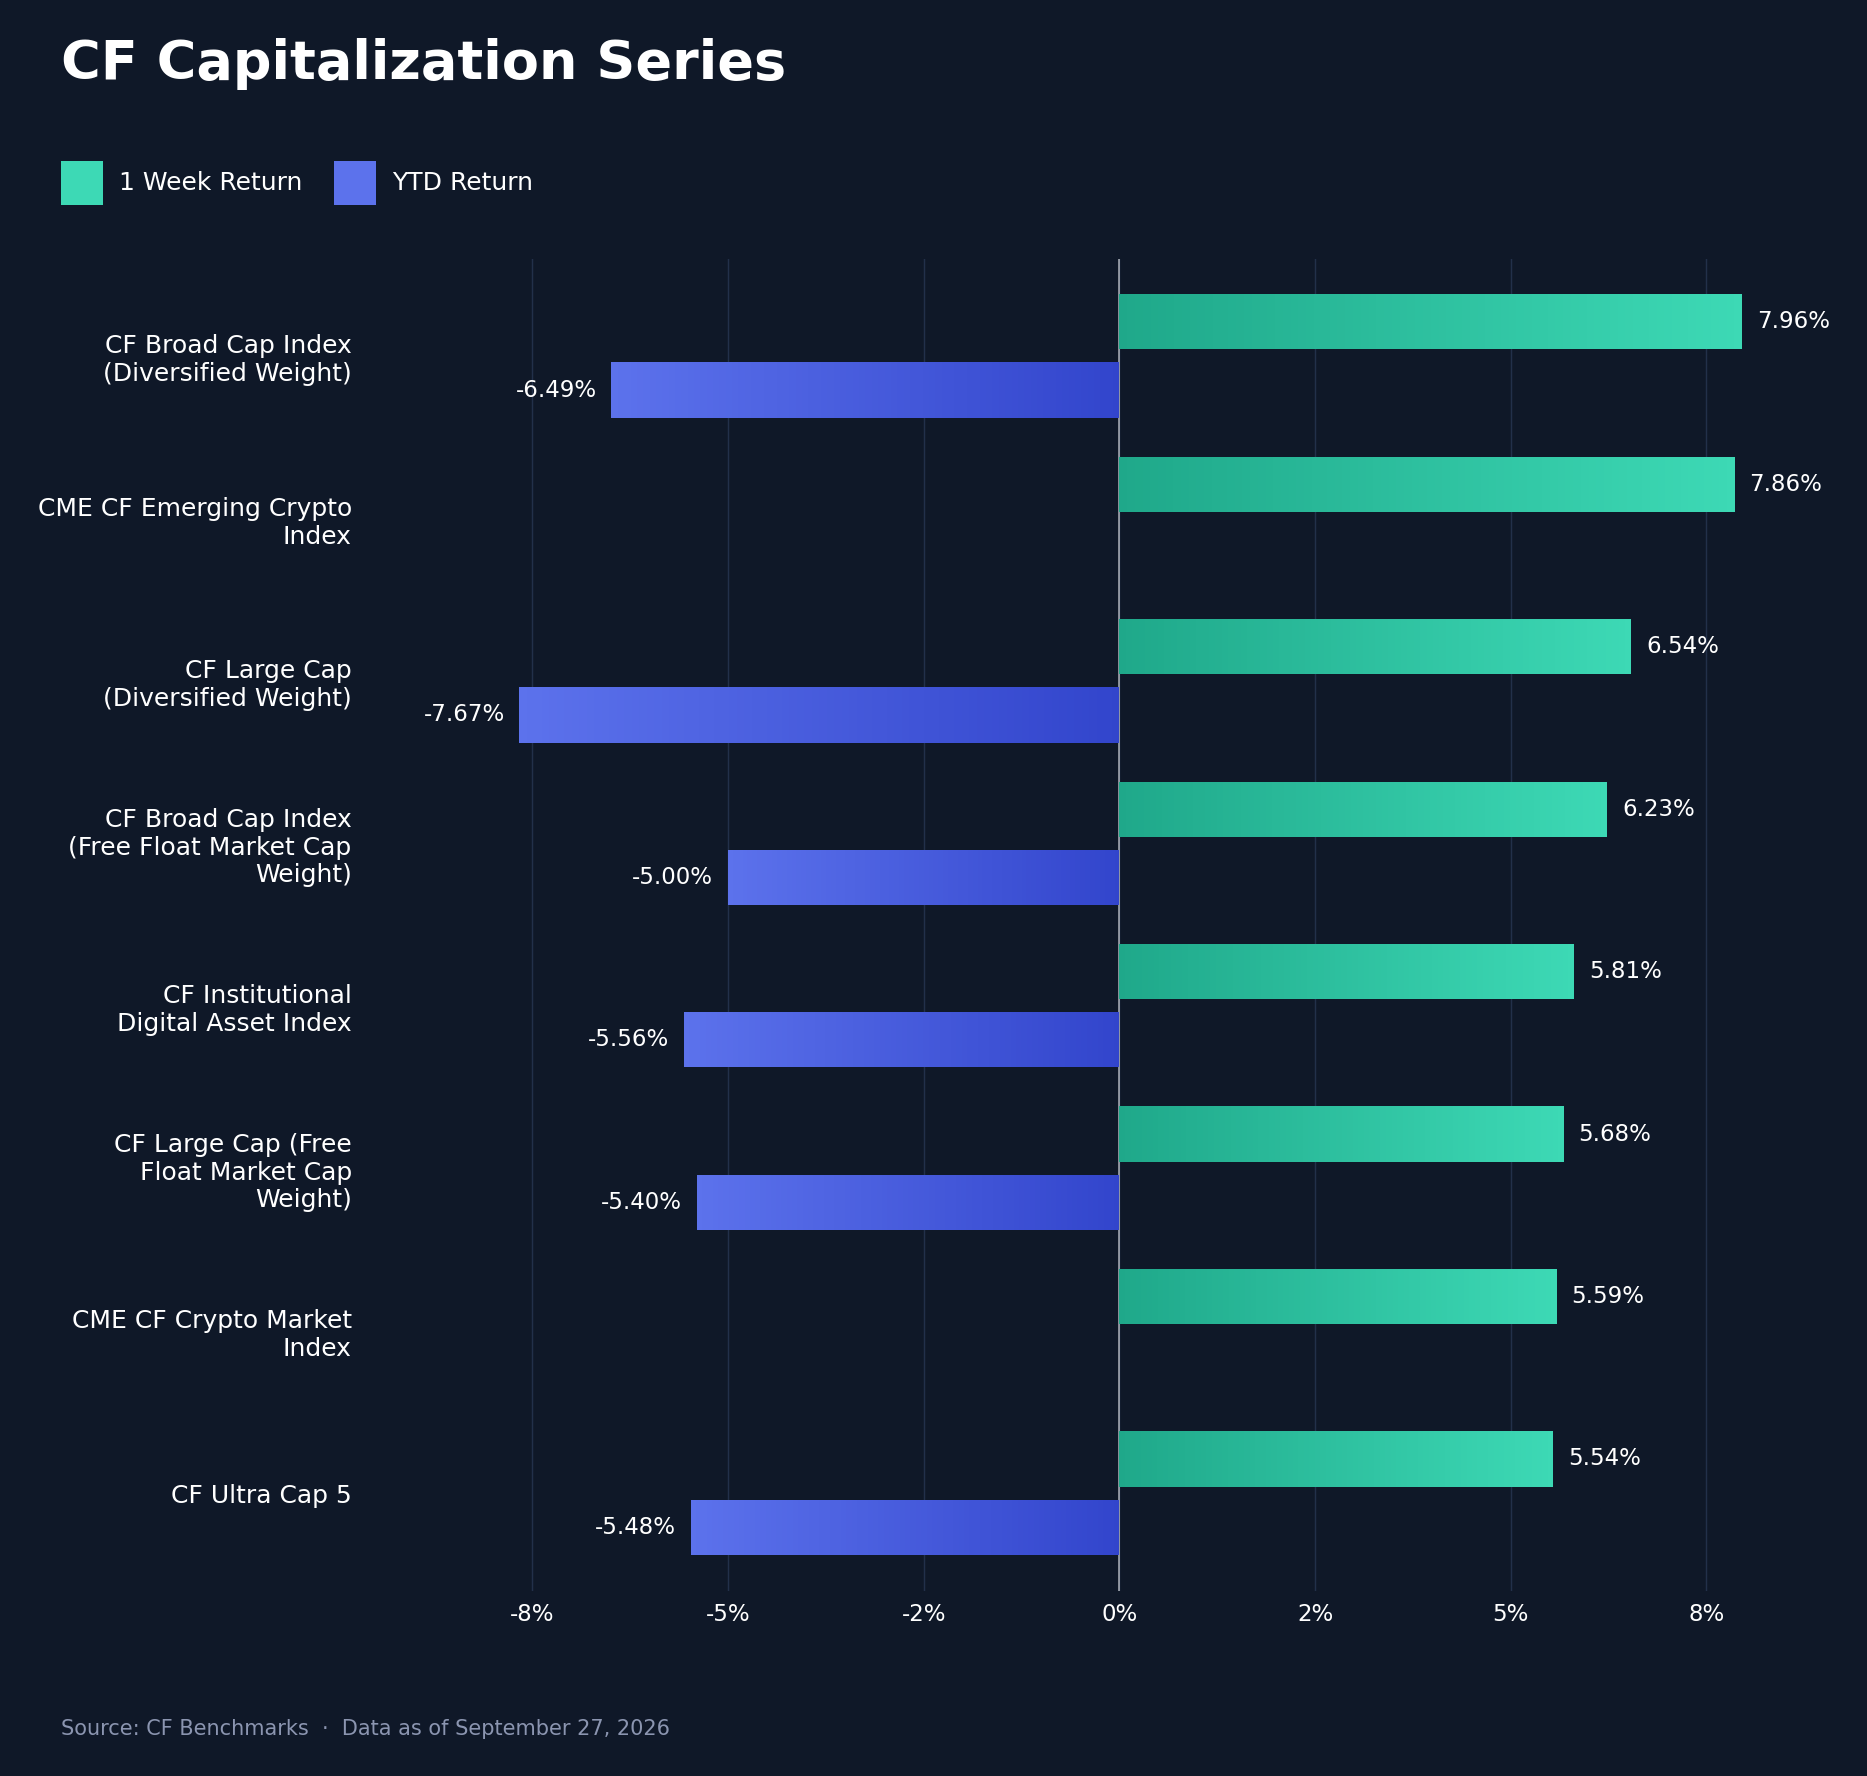
All eight CF Capitalization Series indices advanced for a second week, and diversified weighting again outperformed. CF Broad Cap Index (Diversified Weight) led at +7.96% w/w (YTD -6.49%), followed by the CME CF Emerging Crypto Index at +7.86% and CF Large Cap (Diversified Weight) at +6.54% (YTD -7.67%). CF Broad Cap Index (Free Float Market Cap Weight) gained 6.23% (YTD -5.00%), CF Institutional Digital Asset Index 5.81% (YTD -5.56%), CF Large Cap (Free Float Market Cap Weight) 5.68% (YTD -5.40%), the CME CF Crypto Market Index 5.59% and CF Ultra Cap 5 5.54% (YTD -5.48%). The 2.41 pp range narrowed from 2.71 pp a week earlier. Broad Cap Diversified beat its free-float counterpart by 1.72 pp and Large Cap Diversified by 0.87 pp, widening from 1.07 pp and 0.66 pp the prior week. ETF demand concentrated in BTC and ETH vehicles did not lift the most concentrated indices to the top of the range, and the diversified lead came from breadth outside the largest assets. YTD values for the Crypto Market and Emerging Crypto indices remain unavailable because their start-of-year fixes are missing.
Factors Analysis
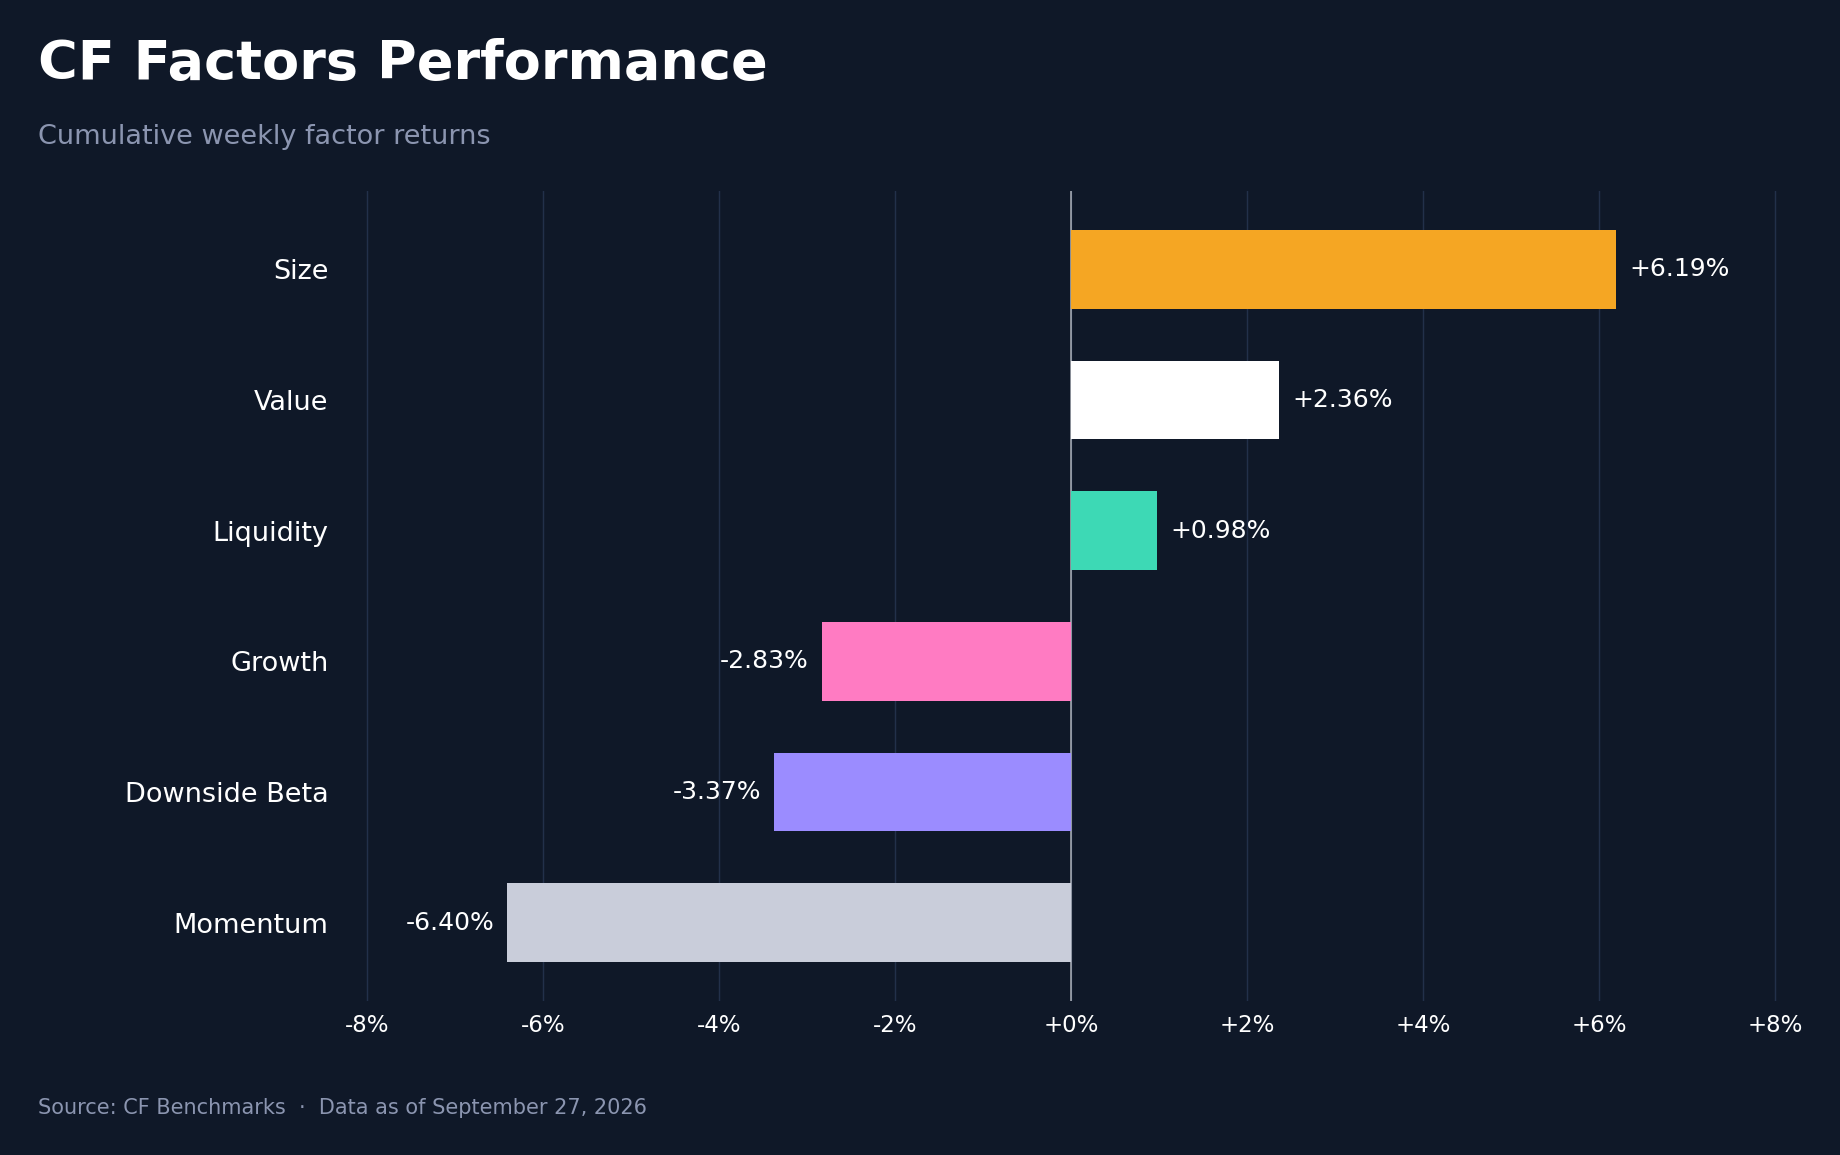
Size led the six CF factors at +6.19% cumulative for the week, followed by Value at +2.36% and Liquidity at +0.98%. Growth returned -2.83%, Downside Beta -3.37% and Momentum -6.40%, leaving a 12.59 pp range, nearly double the prior week's 6.42 pp. Momentum recorded the largest reversal, falling 7.77 pp from +1.37% and moving from first place to last, with 2.50 pp of its weekly loss arriving on Sunday alone. Liquidity posted the largest improvement, rising 6.02 pp from -5.05%, while Size gained 4.96 pp from +1.23%. Size stood at -0.81% on Wednesday before adding 7.00 pp by Sunday, as smaller constituents led the late-week advance. Value's cumulative return stayed positive throughout the week. Downside Beta and Growth remained negative for a second week, deteriorating 0.92 pp and 0.72 pp respectively. The pattern points to a late-week rotation toward smaller constituents and away from recent winners.
Read our latest weekly crypto factors report: Factor Friday - September 25, 2026
Classification Series Analysis
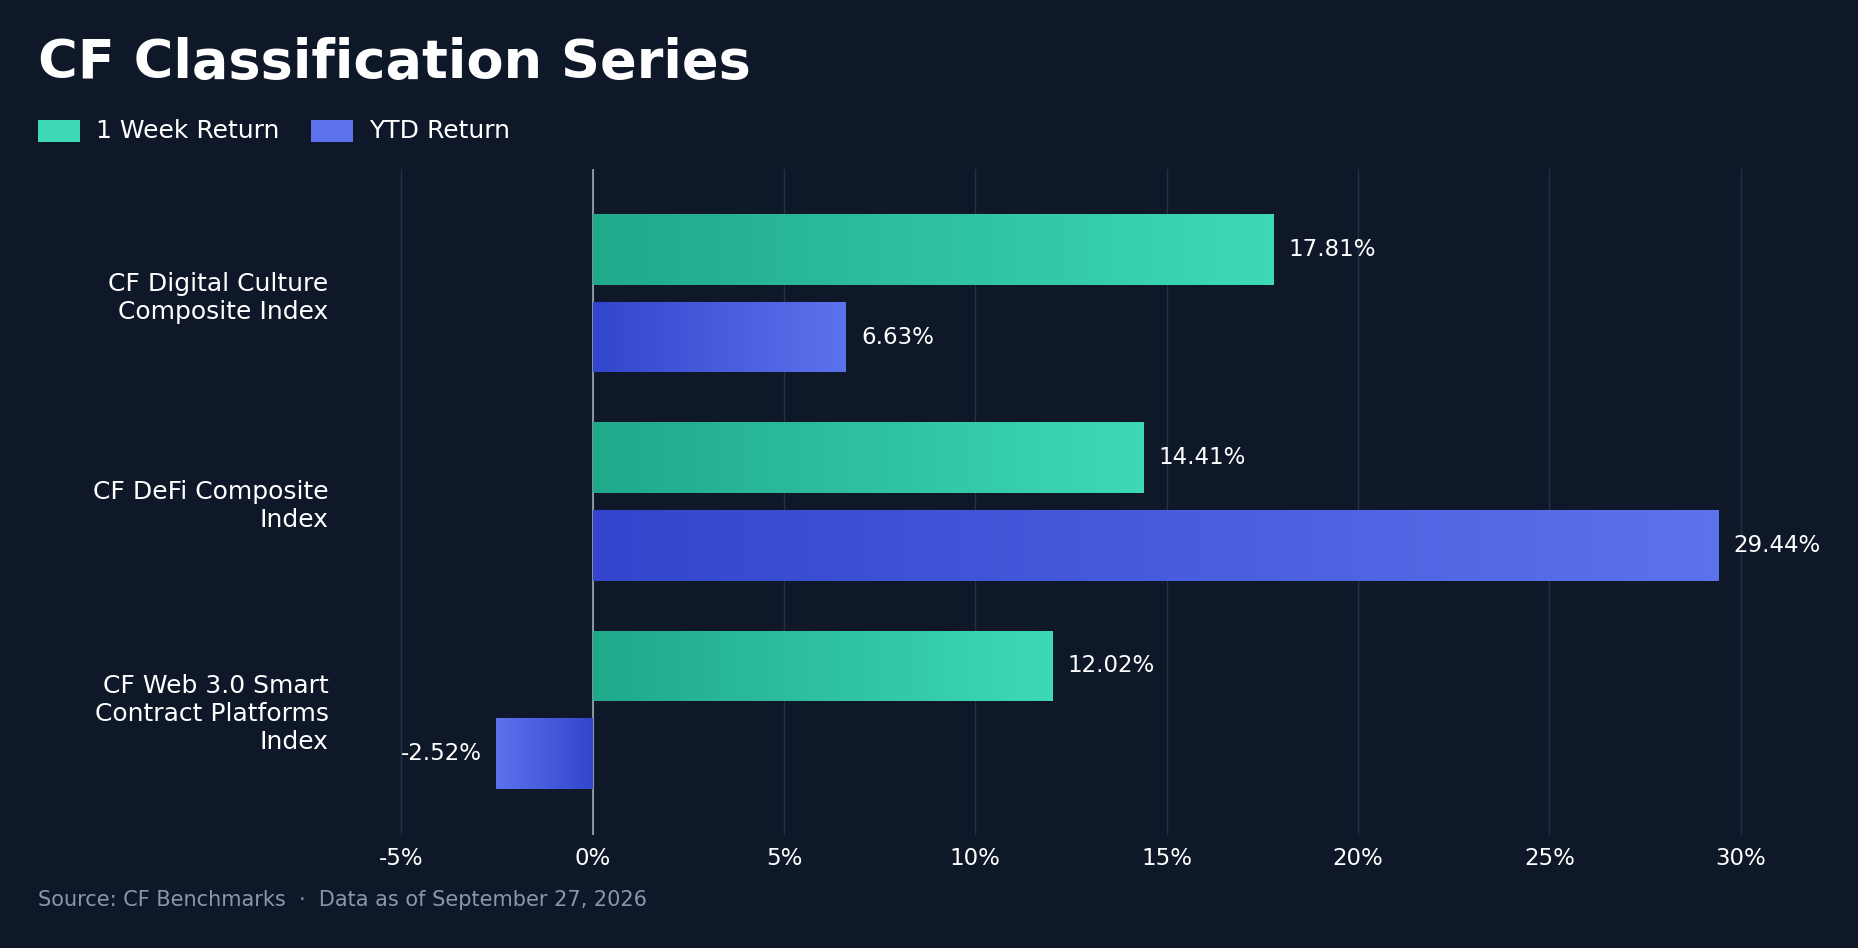
All three CF Classification Series composites advanced for a second consecutive week. The CF Digital Culture Composite Index led at +17.81% w/w, up from +4.42% a week earlier, and moved into positive YTD territory at +6.63% from -9.49%. The CF DeFi Composite Index gained 14.41% and extended its YTD lead to +29.44%, while the CF Web 3.0 Smart Contract Platforms Index rose 12.02% (YTD -2.52%). The weekly range narrowed to 5.79 pp from 11.33 pp, as Digital Culture moved from last to first and DeFi slipped to second. All three composites outpaced every capitalization index by at least 4.07 pp, with leadership rotating toward culture and application tokens.
Sector Analysis
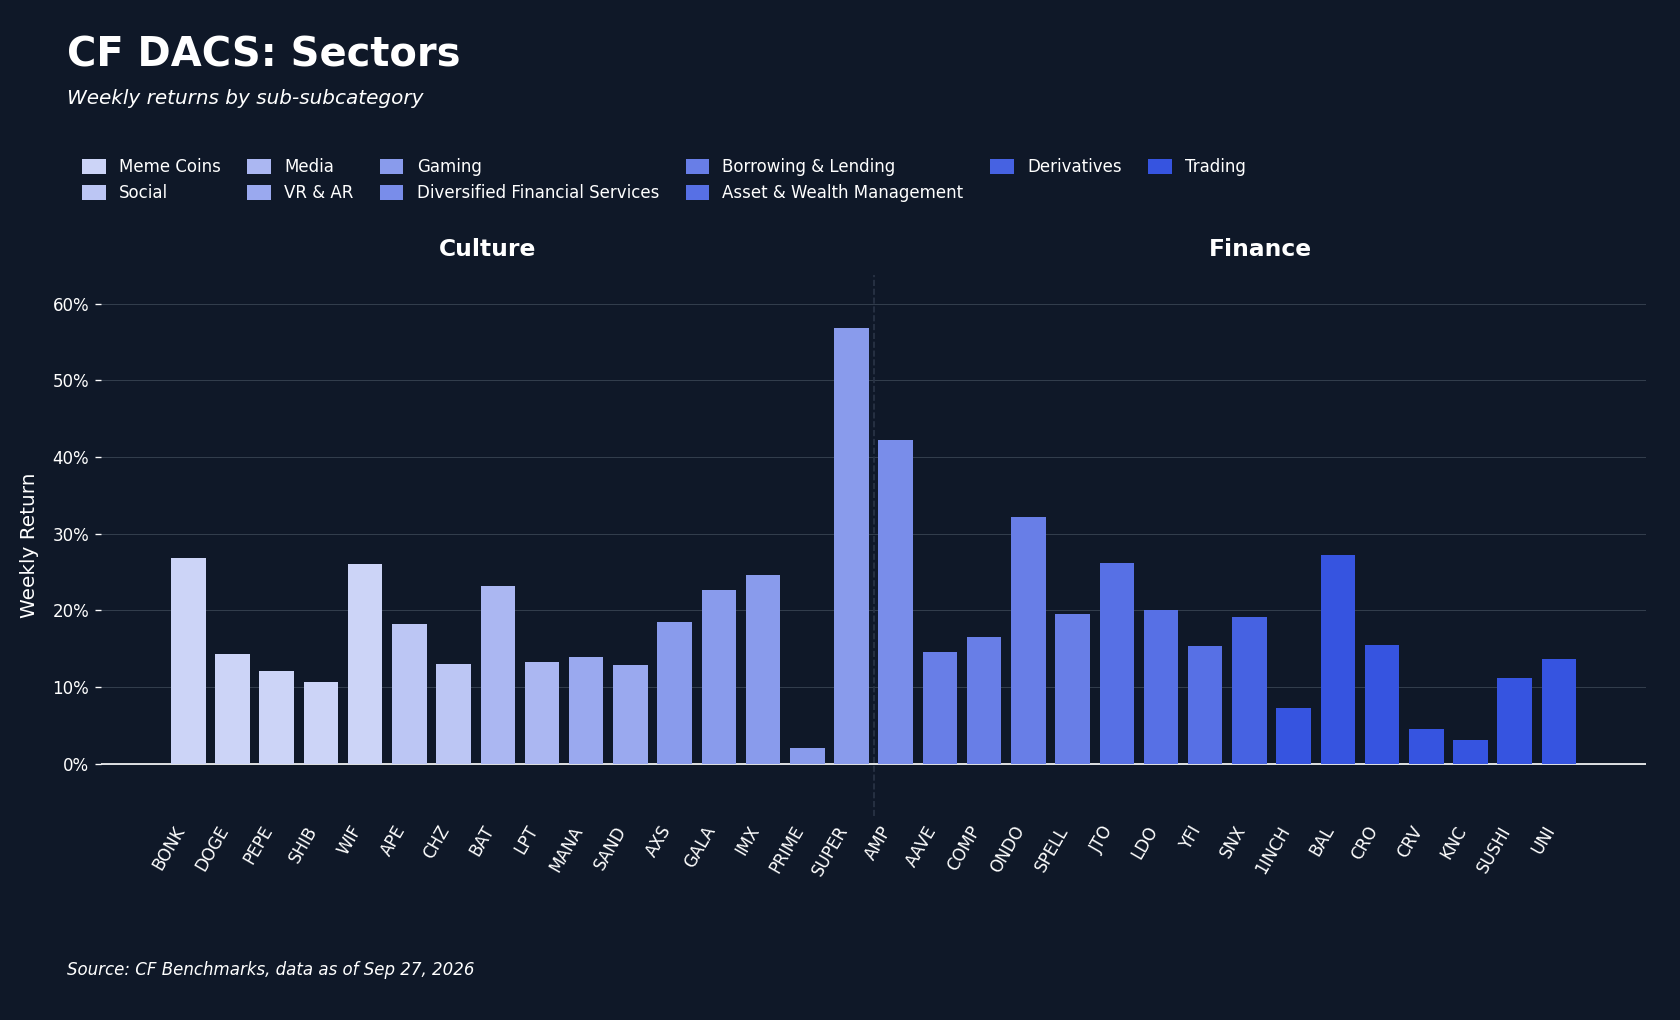
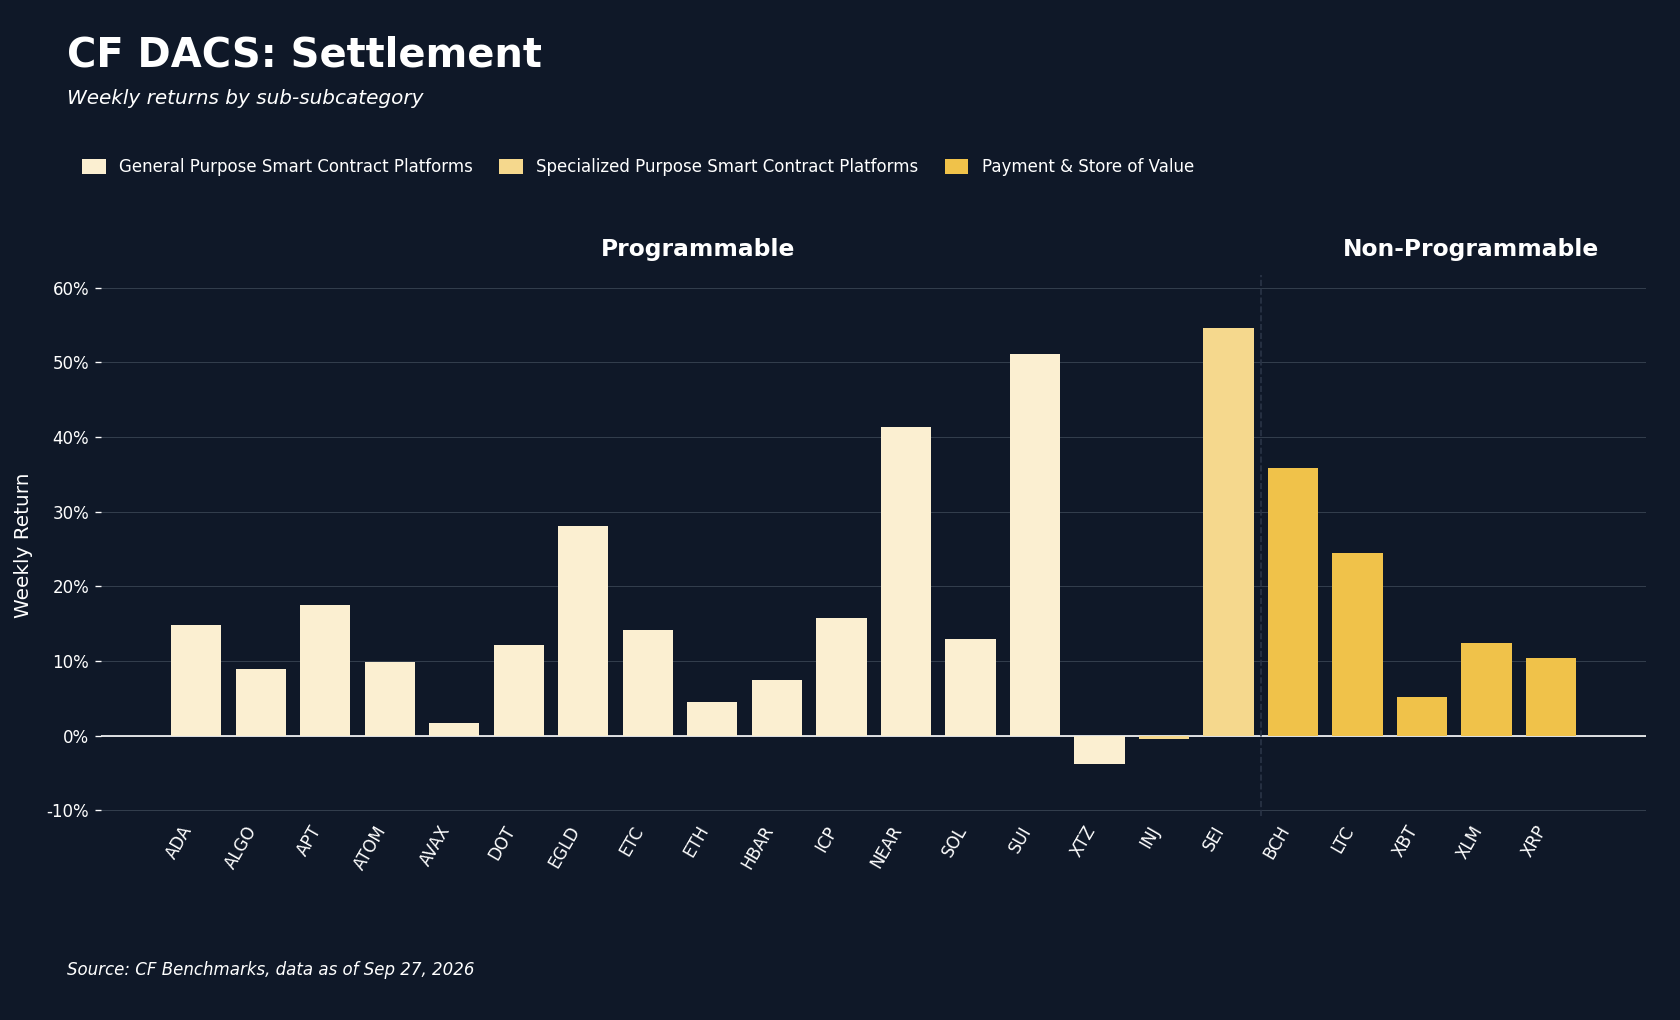
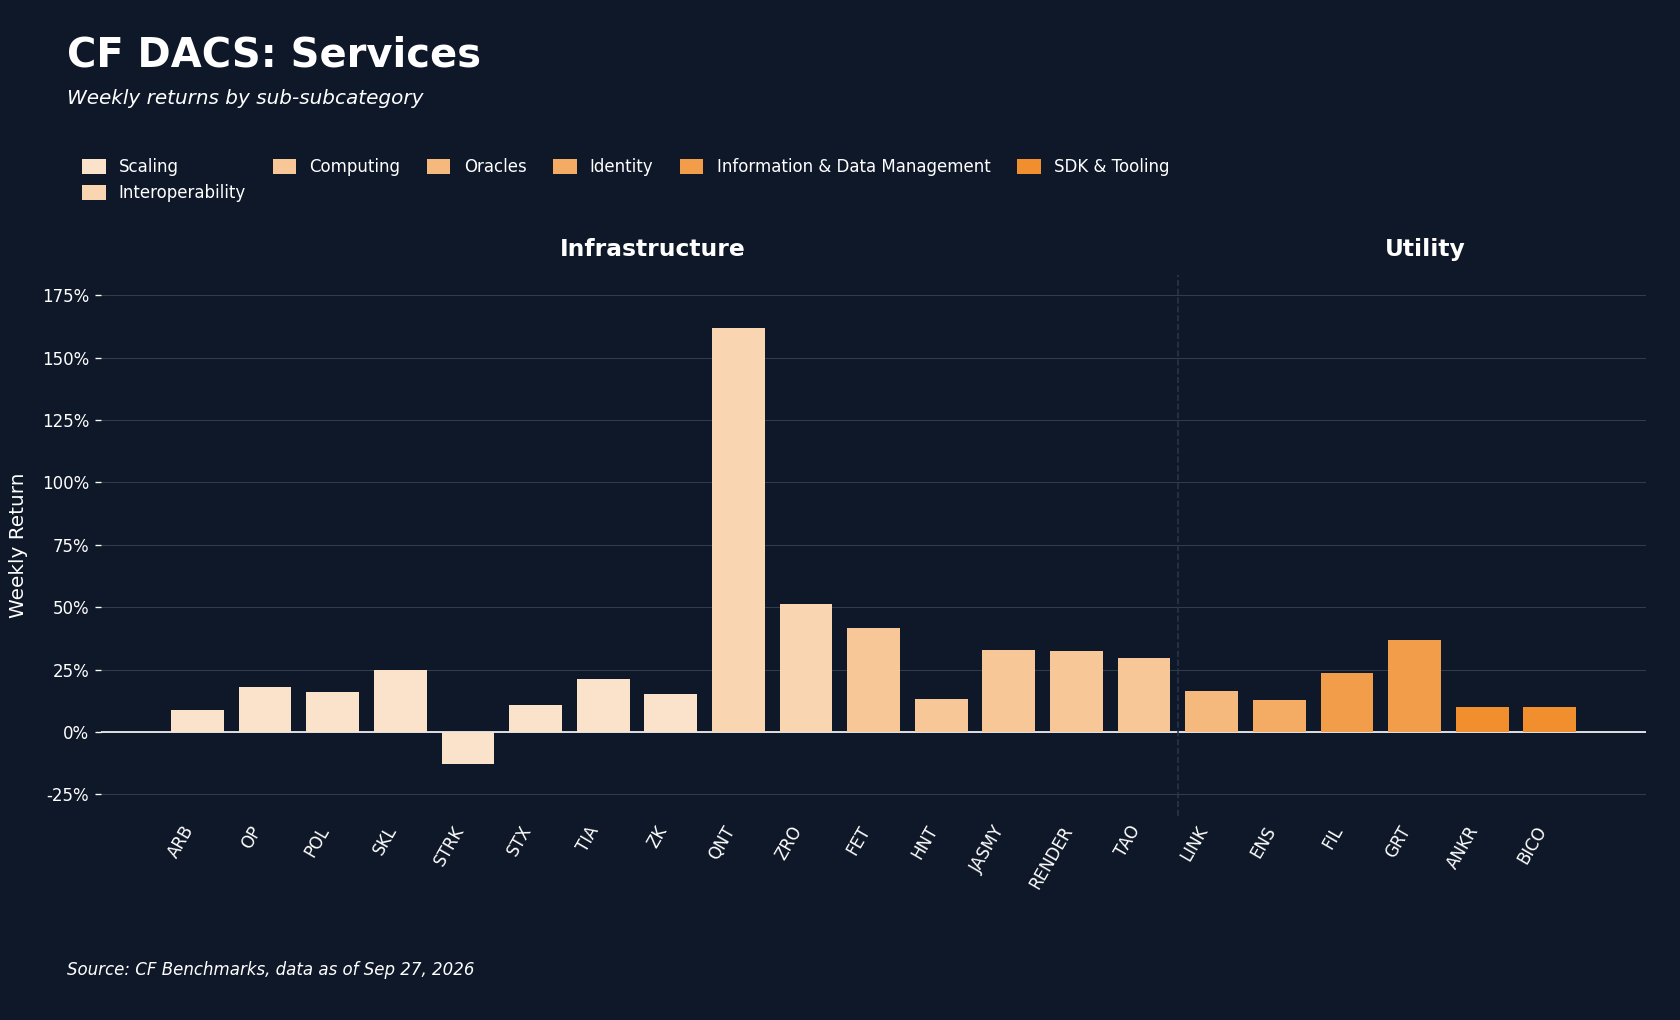
Every populated CF DACS sub-category recorded a double-digit average gain. Infrastructure led at 31.00%, followed by Culture at 19.31%, Utility at 18.32%, Finance at 18.01%, Non-Programmable at 17.68% and Programmable at 17.10%, leaving a 13.90 pp gap between first and last. Quant (QNT) accounted for much of Infrastructure's lead, gaining 161.95% after The Clearing House selected Quant on September 24th to provide the interoperability, orchestration and transaction-management layer for its On-Chain Money Initiative, the same day UK banks completed live tokenized-deposit transactions reported to run on Quant-built infrastructure. QNT's weekend extension, including a 54.7% gain between the Saturday and Sunday fixes, came with no new announcement found and coincided with heavy short liquidations and record open interest. Excluding QNT lowers the Infrastructure average to 21.64%, a 9.35 pp difference that still leaves it first. LayerZero (ZRO) added 51.28% and Fetch.ai (FET) 41.82% within the same sub-category. Programmable fell from first to last, although Sei (SEI) gained 54.64%, Sui (SUI) 51.09% and Near Protocol (NEAR) 41.35%, the latter after NYSE Arca approved the Bitwise NEAR ETF for listing on September 24th; excluding NEAR lowers the Programmable average to 15.58%. SuperVerse (SUPER) led Culture at 56.84%, Amp (AMP) led Finance at 42.22%, and Bitcoin Cash (BCH) rose 35.87% against BTC's 5.22%. Only three of 75 constituents with valid weekly returns declined: Starknet (STRK) at -12.69%, Tezos (XTZ) at -3.75% and Injective (INJ) at -0.50%. QNT and STRK defined a 174.64 pp spread.
CF Staking Series
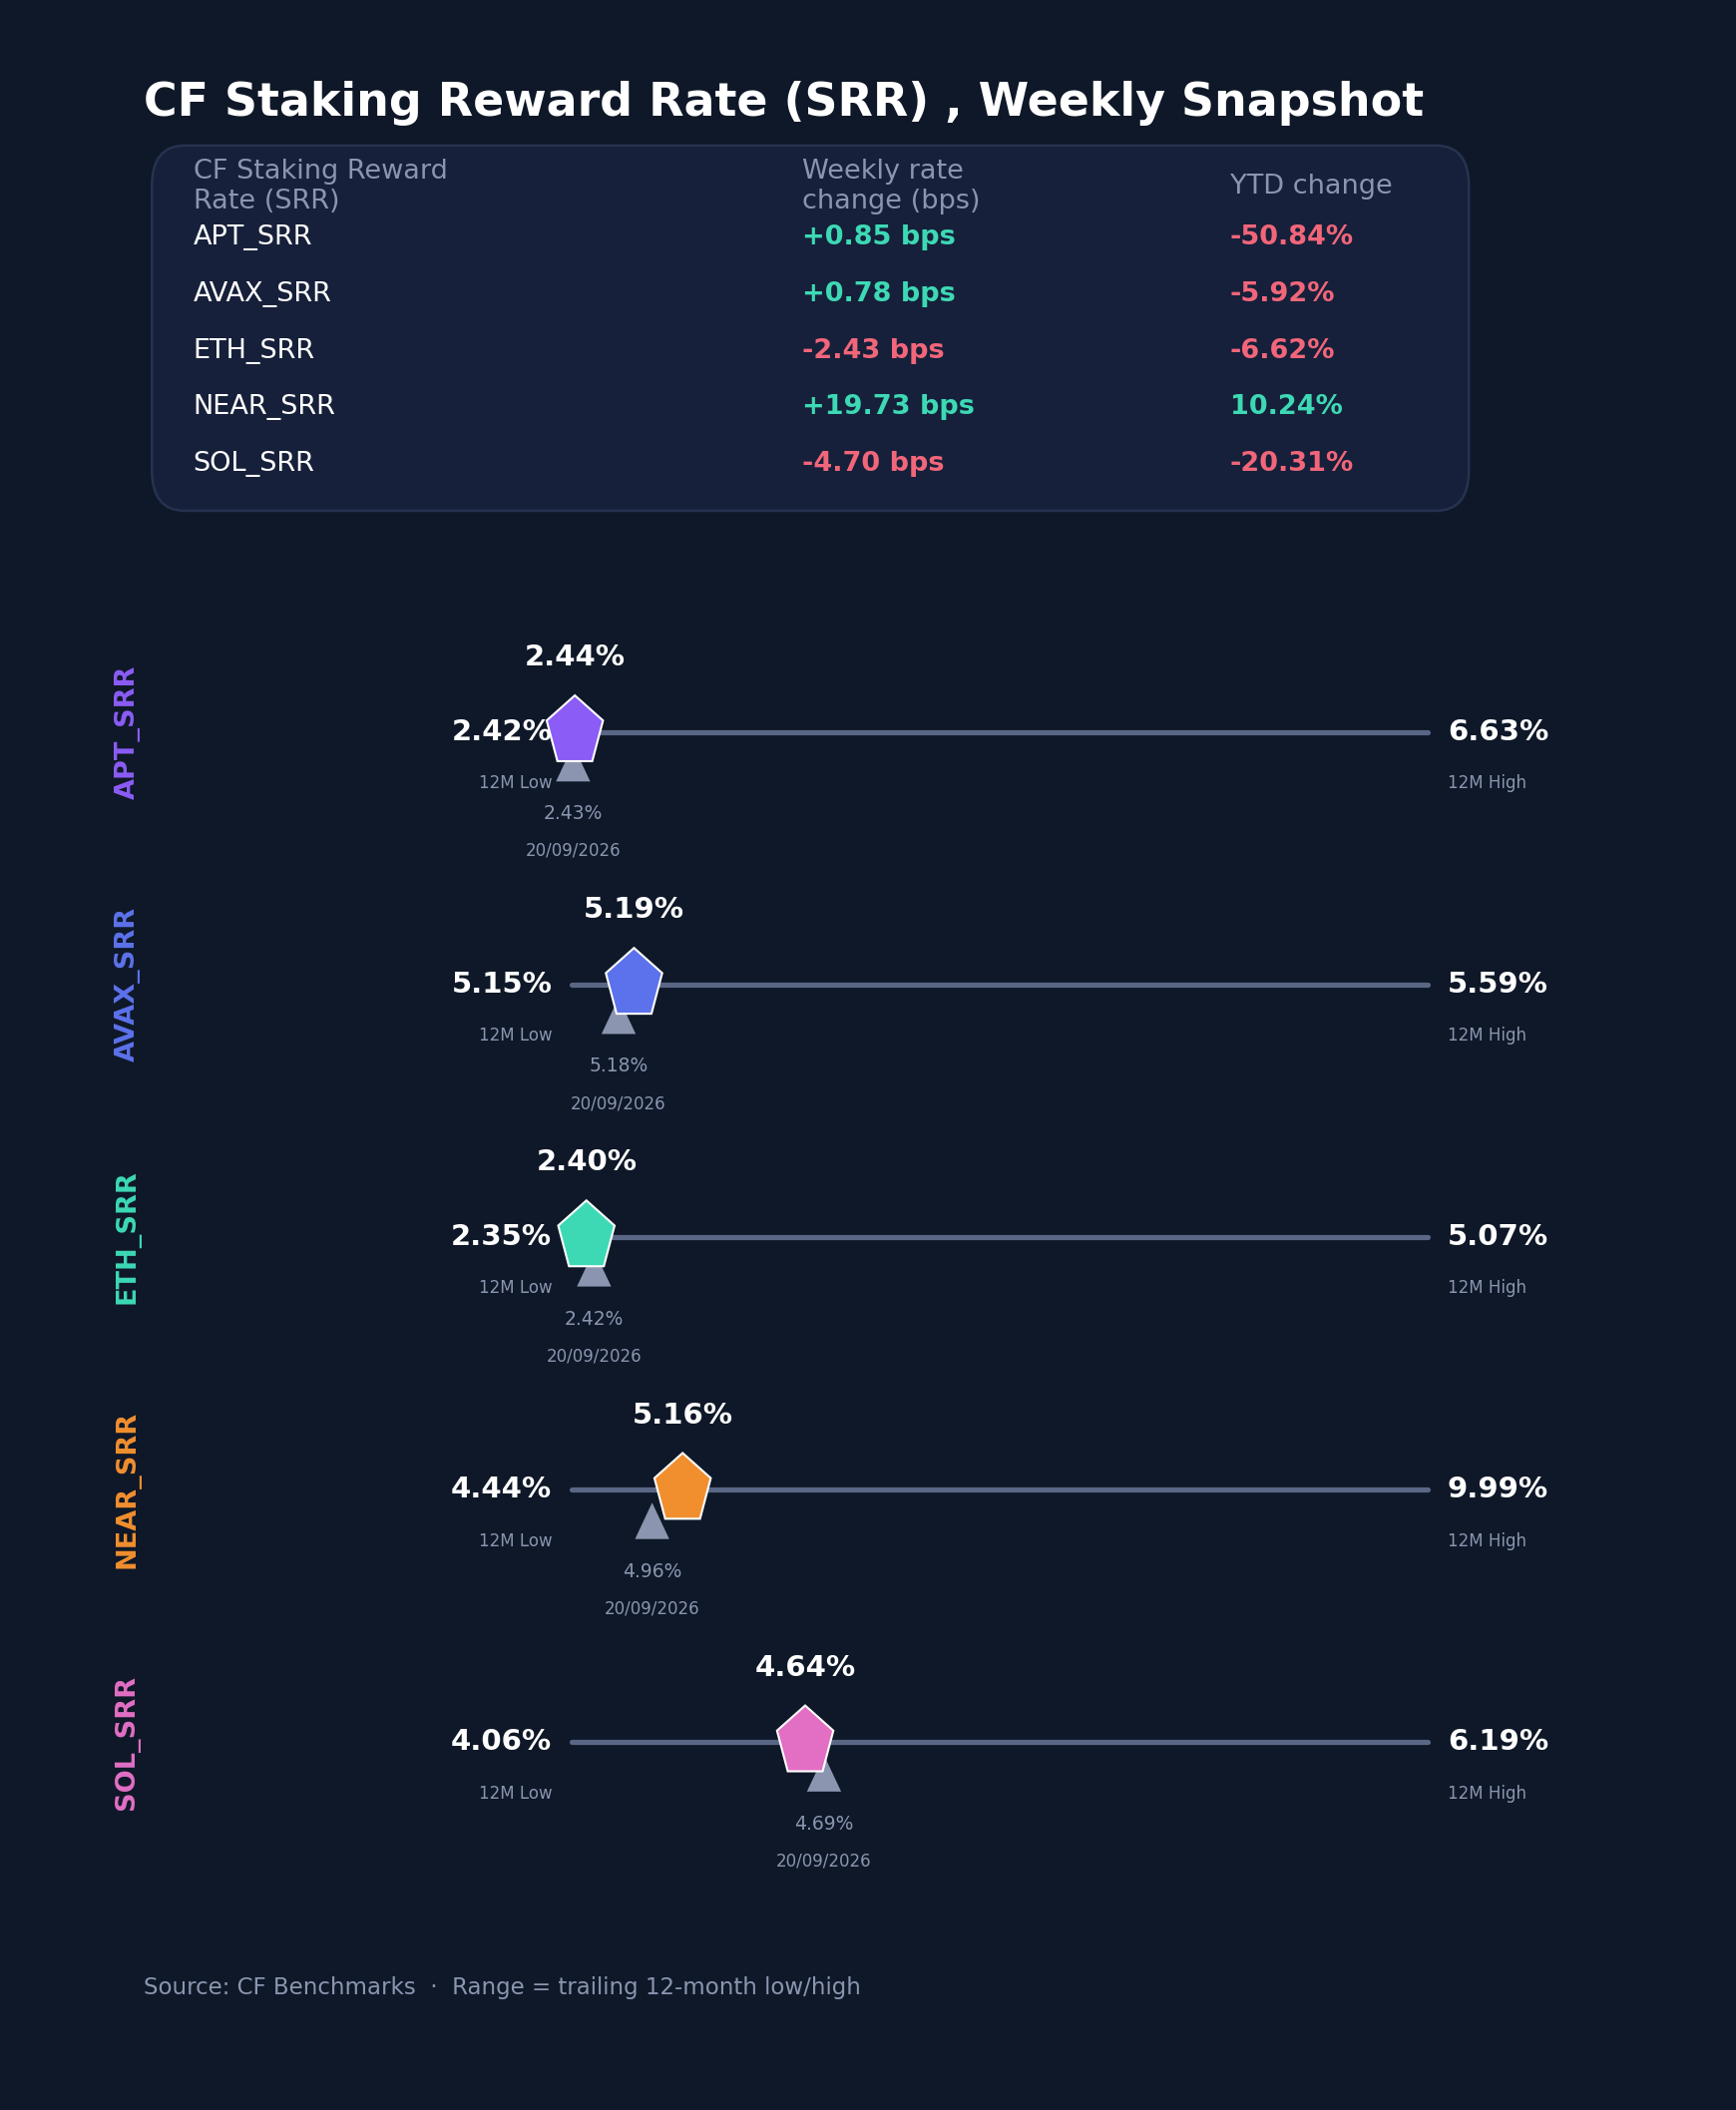
The CF Staking Series was quiet outside Near Protocol (NEAR). NEAR led the relative rate-index returns at +3.97% w/w, followed by Aptos (APT) at +0.35% and Avalanche (AVAX) at +0.15%, while Ether (ETH) and Solana (SOL) each declined 1.00%. These are relative changes in the series, not staking income earned during the week. NEAR's reward rate rose 19.7 basis points (bps) to 5.1611% from 4.9638%, following a 17.45 bps increase a week earlier, and now sits 2.5 bps below AVAX at 5.1861%, which added 0.8 bps. APT rose 0.85 bps to 2.4398%, 1.6 bps above its trailing 12-month low. SOL fell 4.7 bps to 4.6414% and ETH 2.4 bps to 2.3985%, both smaller declines than the prior week's 8.54 bps and 4.25 bps. Reward-rate changes spanned -4.7 bps to +19.7 bps, and current reward rates spanned 2.79 pp, with AVAX the highest and ETH the lowest. NEAR's sustained increase has nearly closed its gap with AVAX at the top of the set, while the rest of the series was little changed.
Interest Rate Analysis
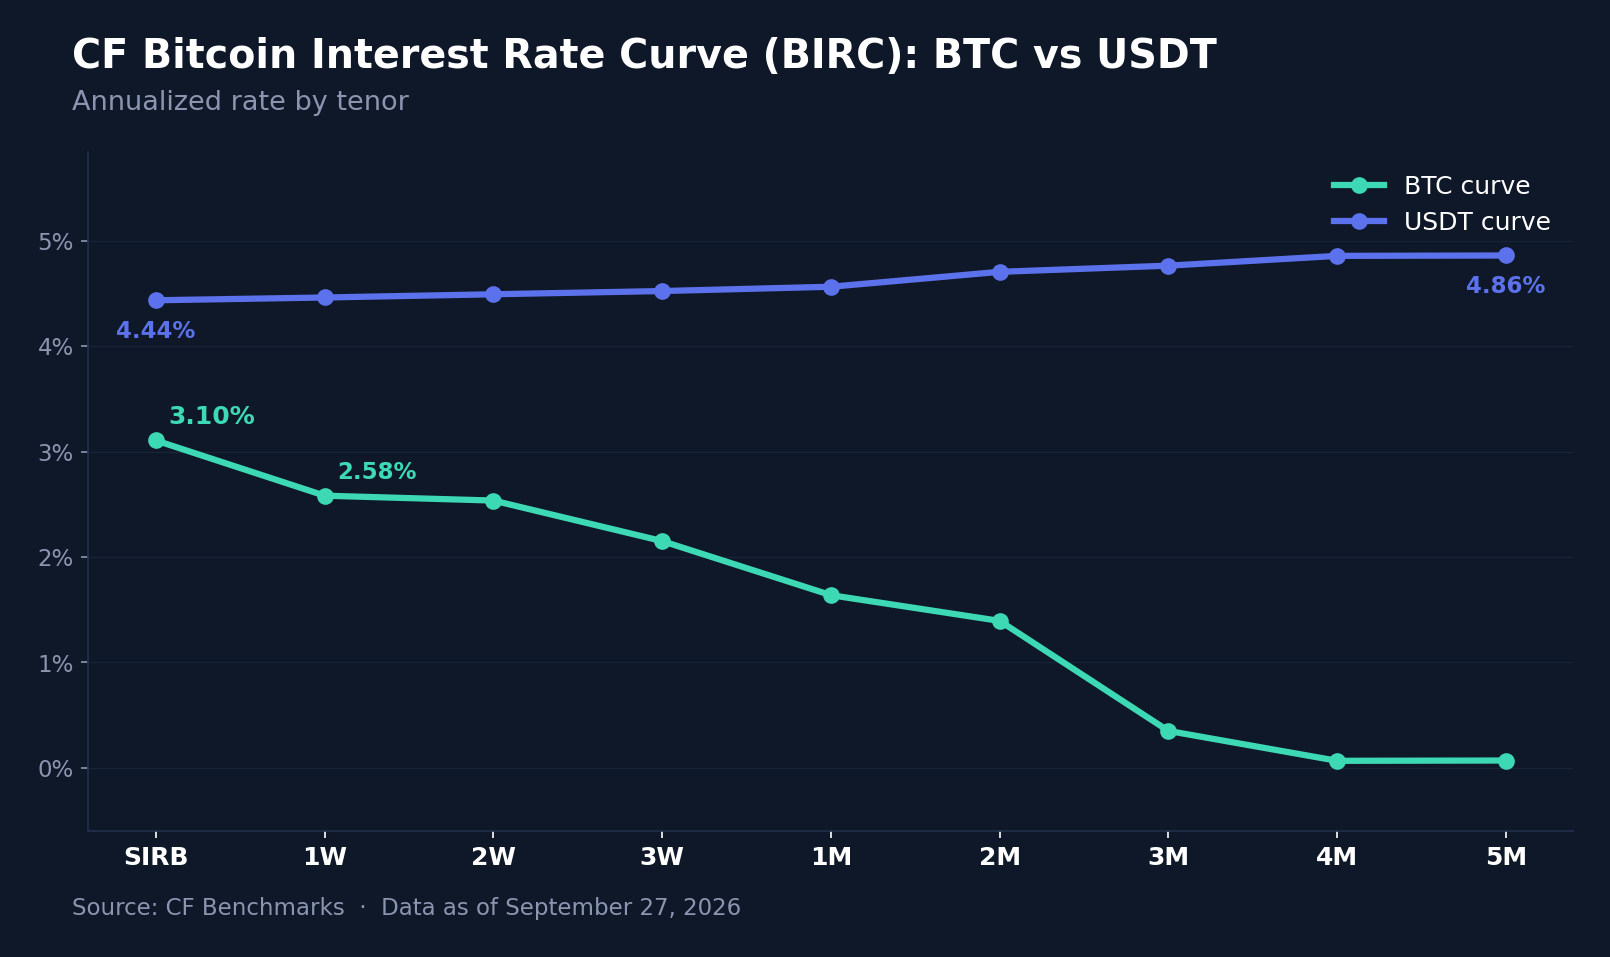
The CF Bitcoin Interest Rate Curve (BIRC) rose at the front on both the BTC and Tether (USDT) curves, but only the USDT curve shifted in parallel. On the weekly-average basis, BTC's Short-term Interest Rate Benchmark (SIRB) increased 130.1 bps to 3.1046% from 1.8037%, and the 1-week (1W) rate rose 94.2 bps to 2.5808%. The increase faded along the curve: 2-week (2W) rose 34.6 bps to 2.5345% and 3-week (3W) 6.7 bps to 2.1496%, while 1-month (1M) fell 30.5 bps to 1.6365%, 2-month (2M) 3.2 bps to 1.3922% and 3-month (3M) 52.3 bps to 0.3478%. BTC 4-month (4M) and 5-month (5M) rates published a single non-zero print, on September 25th, for weekly means of 0.0642% and 0.0671%. That left the BTC curve steeply inverted, with SIRB 275.7 bps above 3M. USDT rates rose between 59.2 and 69.4 bps at every tenor, with SIRB at 4.4355%, 1M at 4.5640% and 5M at 4.8605%, keeping a steady upward slope. USDT's premium over BTC at SIRB narrowed to 133.1 bps from 193.7 bps. Across both curves, tenor changes ranged from -52.3 bps to +130.1 bps. The pattern points to a broad increase in dollar stablecoin funding costs alongside a front-end BTC rate increase that did not extend to longer tenors.
Closing Synthesis
A weekend short squeeze and lower oil prices opened a broad rally that held through a hawkish repricing, as flash PMIs beat, Governor Barr pointed to further rate increases and Treasury yields rose. Every single asset, capitalization index and classification composite advanced, and 72 of 75 DACS constituents with valid returns gained. BTC and ETH trailed LINK, ADA, SOL and XRP despite $3.08 billion of combined US spot ETF inflows. Diversified indices beat their free-float counterparts, classification composites outpaced every capitalization index, and Infrastructure led the DACS averages, with Quant's tokenized-deposit mandate concentrating that lead and NEAR's ETF listing approval standing out in Programmable. Size led and Momentum reversed as smaller constituents took the late-week lead. Implied volatility was flat while realized volatility rose, NEAR's reward rate moved closer to AVAX's, and funding costs rose across the USDT curve and at the BTC front end. The result was a broad, high-beta advance against a tighter rates backdrop.
The information contained within is for educational and informational purposes ONLY. It is not intended nor should it be considered an invitation or inducement to buy or sell any of the underlying instruments cited including but not limited to cryptoassets, financial instruments or any instruments that reference any index provided by CF Benchmarks Ltd. This communication is not intended to persuade or incite you to buy or sell security or securities noted within. Any commentary provided is the opinion of the author and should not be considered a personalised recommendation. Please contact your financial adviser or professional before making an investment decision.
Note: Some of the underlying instruments cited within this material may be restricted to certain customer categories in certain jurisdictions.
Addition of Lighter Settlement Price and Spot Rate to the CF Digital Asset Index Family
The Administrator announces the addition of the CF Lighter-Dollar Settlement Price and CF Lighter-Dollar Spot Rate to the CF Digital Asset Index Family - Single Asset Series.
CF Benchmarks
Bitcoin ETFs See Inflows as Yields Climb
High-beta digital assets rallied broadly over the week, with breadth reaching well beyond the largest assets as rates repriced higher. Smaller names and Infrastructure led on a tokenized-deposit mandate, Momentum reversed, implied volatility held flat and funding costs rose.
Mark Pilipczuk
Factor Friday - September 25, 2026
The Market rose 11.70% to lead CF Benchmarks' factor table, ending Value's three-week run at the top. Liquidity finished last and Downside Beta fell for a third week, so the rally favored heavily traded, drawdown-sensitive tokens, while Size showed the bid still reached smaller caps.
Mark Pilipczuk
By clicking Accept, you consent to CF Benchmarks's use of cookies.
Visit Cookie Settings to learn how CF Benchmarks uses cookies and to adjust your preferences.