
Nov 13, 2026
Factor Friday - November 13, 2026
Size leads as the Market keeps falling
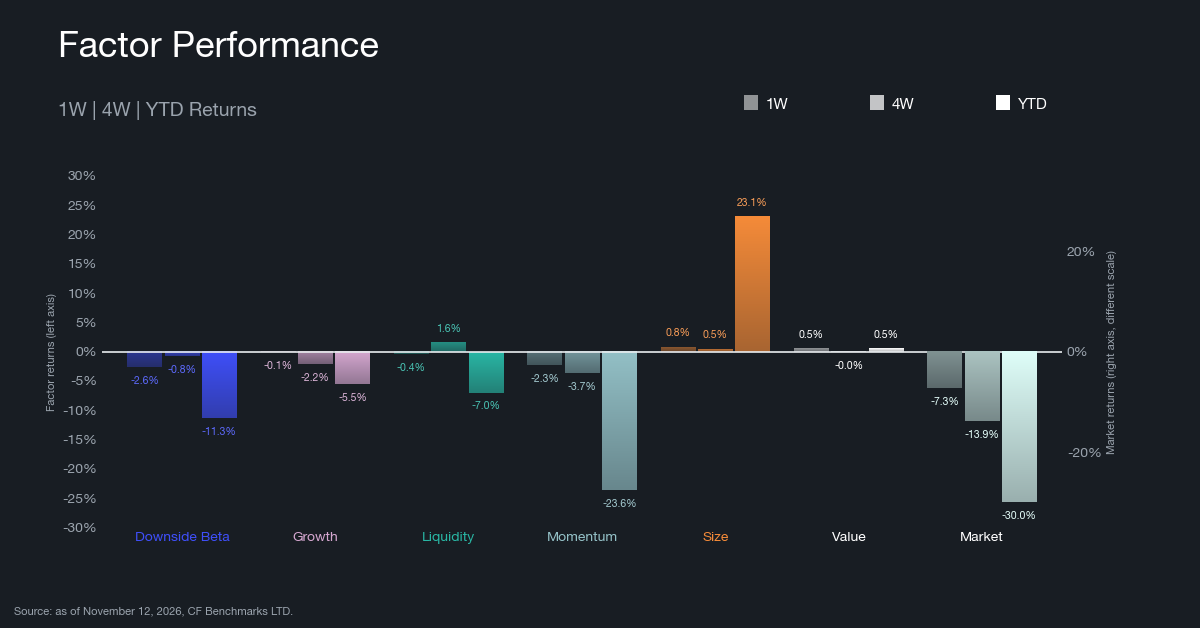
Size led the factor table at 0.78% in a week the Market fell 7.25%, its largest weekly loss since the week to June 11. Value (0.51%) also gained, while Growth (-0.09%), Liquidity (-0.42%), Momentum (-2.34%) and Downside Beta (-2.60%) declined, so the six style factors finished within 3.4 percentage points (pp) of each other, against 2.2 pp a week earlier. Over four weeks Liquidity leads at 1.57%, ahead of Size (0.45%), Value (-0.02%), Downside Beta (-0.79%), Growth (-2.15%) and Momentum (-3.68%), with the Market (-13.87%) last. Year to date Size leads at 23.09%, up from 22.14% a week earlier, followed by Value (0.54%), Growth (-5.47%), Liquidity (-6.99%), Downside Beta (-11.29%) and Momentum (-23.64%), with the Market (-29.95%) at the bottom. Breadth stayed narrow, with 2 of 35 CF Broad Cap constituents closing higher against 1 a week ago, and the median constituent lost 7.30% after losing 7.43%. Bitcoin (BTC) fell 6.01%, 1.3 pp ahead of the median. The Market is down 9.42% month to date, only 0.3 pp short of the 9.72% loss for all of October. Size's lead on the week is the less certain read. The ten highest size-beta tokens beat the ten lowest by only 1.0 pp, and the gap reverses when the one riser in the highest ten is removed. Liquidity's small loss is the opposite case, with the ten highest liquidity-beta tokens trailing the ten lowest by 5.5 pp. A third week of Market losses would test both reads.
Rolling Factor Rankings and Rotation
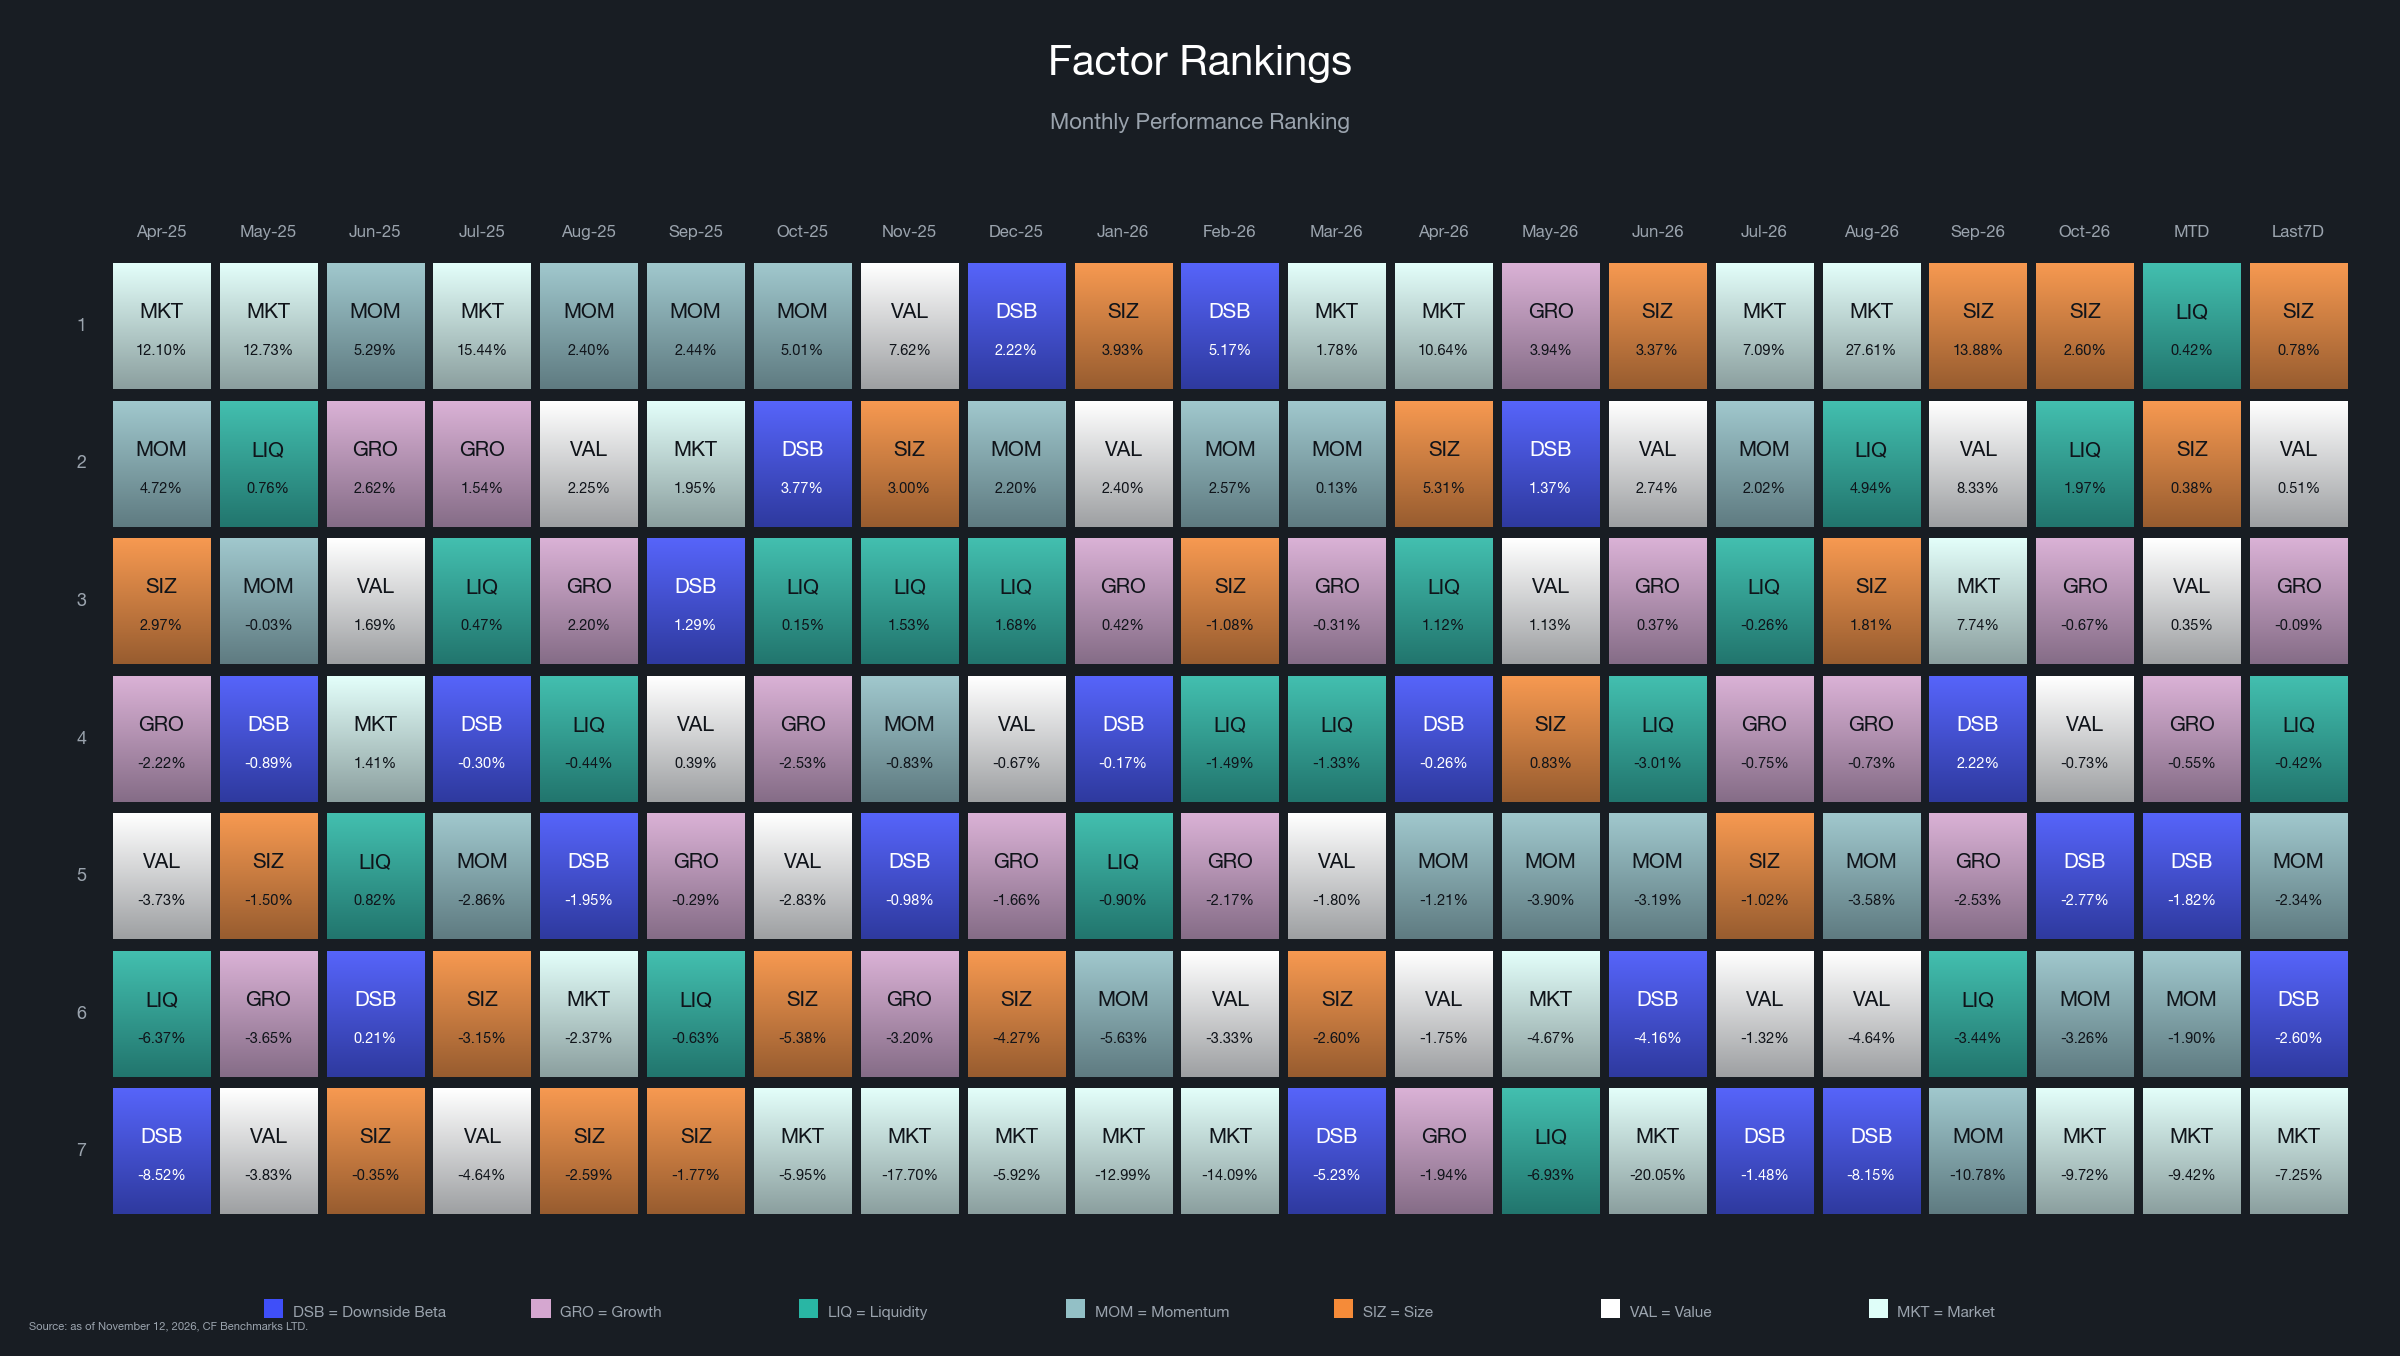
Leadership moved from Downside Beta to Size on the weekly table. Size rose from sixth to first at 0.78%, Value rose from fourth to second at 0.51%, Growth stayed third at -0.09%, Liquidity slipped from second to fourth at -0.42%, Momentum stayed fifth at -2.34%, and Downside Beta fell from first to sixth at -2.60%, a 4.3 pp swing from last week's 1.66%. The Market stayed last at -7.25%, after -6.17% a week earlier. Liquidity's two weekly gains, at 1.54% and 1.51%, ended, but it still leads the four-week table at 1.57%, down from 4.46%. Only Liquidity and Size are positive over four weeks. Size moved from fifth to second on that table, with its four-week return rising to 0.45% from -2.28%, a 2.7 pp improvement against a 0.78% gain on the week, and the rest is the window as the days from October 13 to October 19 left it. Its last five weekly prints have run 0.59%, 0.75%, -0.79%, -0.50% and 0.78%. Size also moved from fifth to second month to date at 0.38%, behind Liquidity (0.42%, down from 0.84%) and ahead of Value (0.35%), Growth (-0.55%), Downside Beta (-1.82%), Momentum (-1.90%) and the Market (-9.42%). Downside Beta and Momentum, second and third month to date a week ago at 0.80% and 0.45%, have fallen to fifth and sixth. Size still leads year to date at 23.09%, well ahead of Value (0.54%). The Market's four-week return fell to -13.87% from -9.03%, and its year-to-date loss widened to -29.95% from -24.47%. Whether Size's lead holds if the decline extends is the test, since its cohort gap holds only under certain cuts.
Market and Key Factor Betas
Market Beta
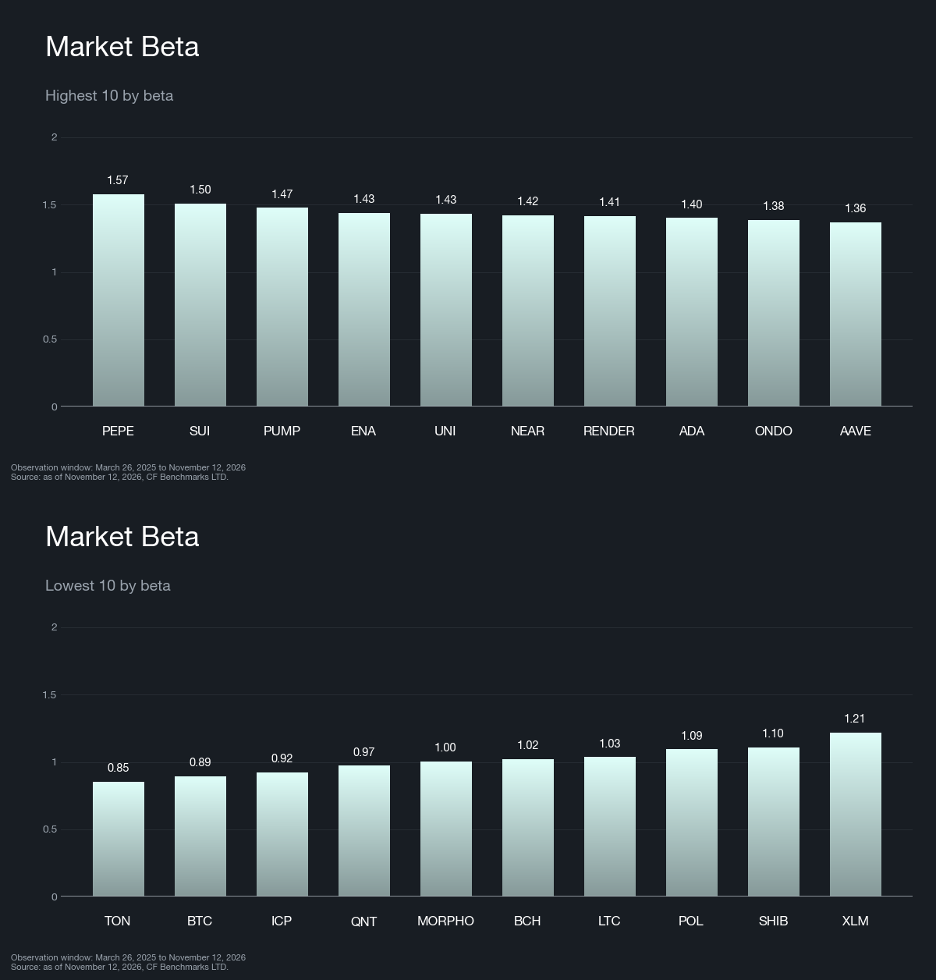
Broad exposure took the loss again. The Market fell 7.25%, and only 2 of 35 CF Broad Cap constituents finished higher, Internet Computer (ICP) at +3.18% and Toncoin (TON) at +1.02%, against 1 a week ago. The median constituent, NEAR Protocol (NEAR), lost 7.30% after 7.43% last week. BTC, at a market beta of 0.89, fell 6.01%, 1.2 pp ahead of the Market. The high market-beta roster changed by one name, with Aave (AAVE) entering at 1.36 as Chainlink (LINK) left. It remains a mix of meme coins and a meme launchpad, three layer-1 platforms, DeFi protocols spanning exchange, lending and synthetic-dollar tokens, an AI compute network and a real-world-asset token. The low-beta ten also changed by one name, with Stellar (XLM) entering at 1.21 as Venice (VVV) left. It holds Bitcoin and two of its forks, two layer-1 and computing platforms, an interoperability token, a lending protocol, a scaling network, a meme coin and a payments token. The ten highest market-beta names returned an average -8.90% against -6.12% for the ten lowest, a 2.8 pp shortfall that runs with the print, down from 4.6 pp last week, and the medians (-7.05% and -5.13%) are 1.9 pp apart in the same direction. Returns inside the high-beta cohort ranged 13.3 pp, from Render (RENDER, -1.51%) to Ethena (ENA, -14.80%). The lowest ten holds two risers, ICP and TON, and excluding them the cohort averages -8.2%, so the shortfall narrows to 0.7 pp. Excluding Bitcoin Cash (BCH, -18.49%) and Quant (QNT, -14.93%), the two worst names in the lowest ten, the lowest ten average -3.5% and the shortfall widens to 5.4 pp. The cohorts run with the print under each cut, but the size of the gap depends on two small risers. Beta ordered returns again, so the highest-beta roster carries the most exposure if the decline extends.
Size
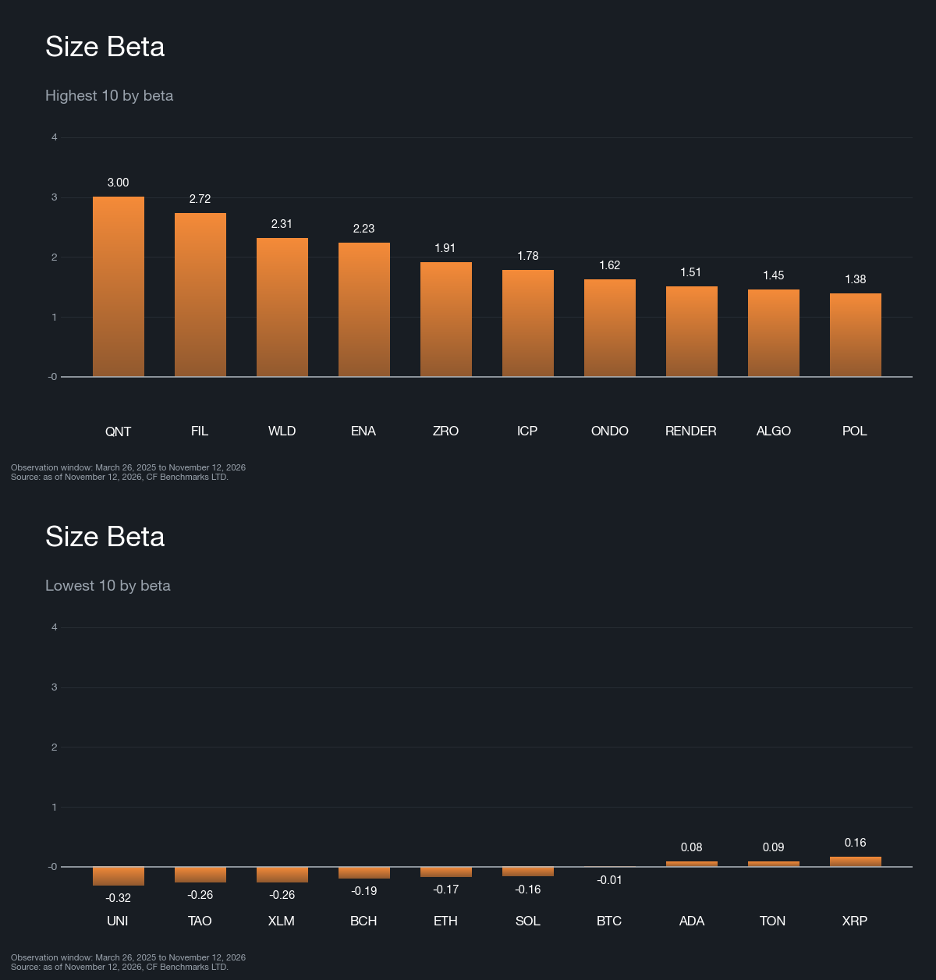
Size gained 0.78% to rank first, up from sixth last week, after two weekly losses of -0.79% and -0.50%. Its four-week return improved to 0.45% from -2.28%, moving it from fifth to second, it is second month to date at 0.38%, and it leads year to date at 23.09%, up from 22.14%. The factor is sign-inverted, so a positive print means smaller tokens outperformed larger ones, here by falling less as the Market lost 7.25%. The beta cohorts give only thin confirmation. The ten highest size-beta names returned an average -7.73% against -8.75% for the ten lowest, a 1.0 pp gap in the factor's direction, and the medians (-7.70% and -8.09%) are 0.4 pp apart in the same direction. Last week the cohorts ran level, at -7.40% against -7.26%, a 0.1 pp gap the wrong way. The result rests on one token at each end. ICP is the only riser in the highest ten, and excluding it the highest ten average -8.94% and trail the lowest ten by 0.2 pp, against the print. Excluding BCH, which fell 18.49% in the lowest ten, the highest ten also trail, by 0.1 pp. The gap runs with the print again only when both risers are removed, ICP from the highest ten and TON from the lowest, which leaves the highest ten ahead by 0.9 pp. The highest ten is unchanged from last week and is led by QNT at 3.00, clear of Filecoin (FIL) at 2.72 and the rest. The group otherwise holds an identity token, a synthetic-dollar token, an interoperability token, a computing platform, a real-world-asset token, an AI compute network, a layer-1 platform and a scaling network, with LayerZero (ZRO) easing to 1.91 from 2.01. The lowest ten holds Bitcoin and Bitcoin Cash, established layer-1 platforms, payments tokens, a DEX token and an AI token, with XRP entering at 0.16 as Morpho (MORPHO) left. Score moves were negligible. The largest was 0.03 and no name changed sides. Size's year-to-date lead is intact, but this week's gain came with a cohort gap that holds only when both risers are set aside.
Liquidity
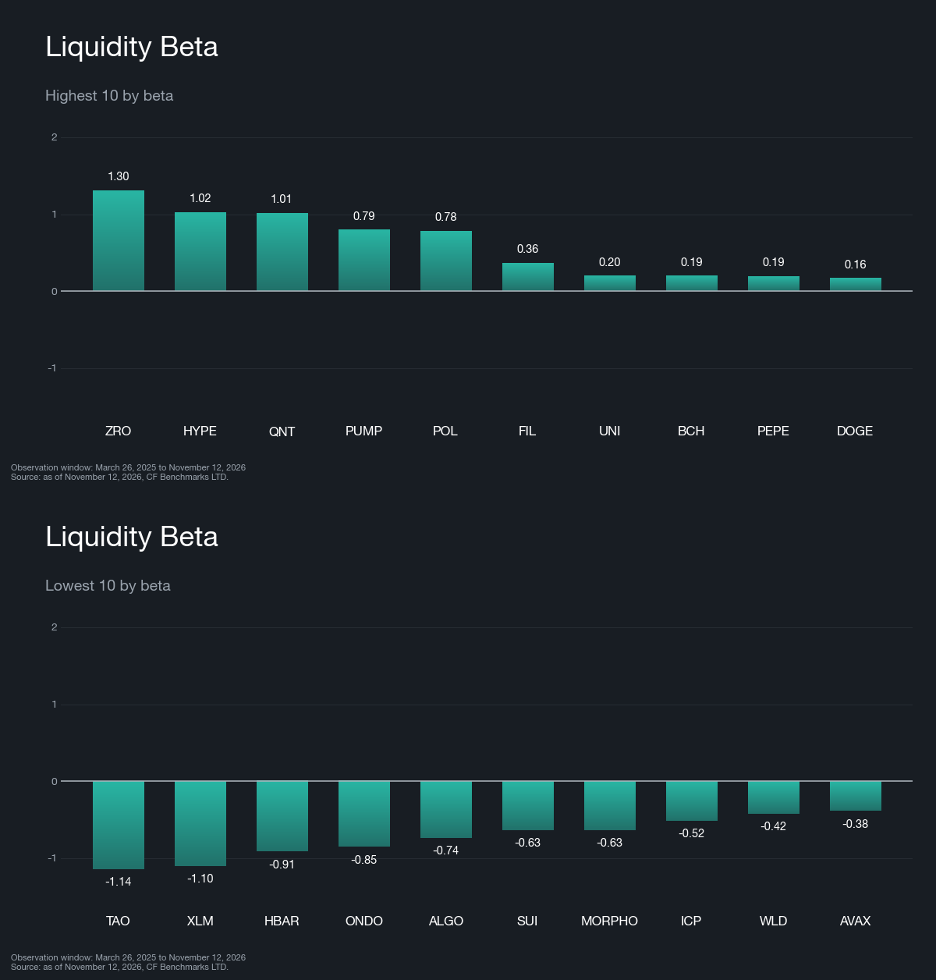
Liquidity lost 0.42% to rank fourth, down from second last week, ending two weekly gains at 1.54% and 1.51%. It still leads the four-week table at 1.57%, down from 4.46%, and month to date at 0.42%, down from 0.84%. The factor is sign-inverted, so a negative print means more liquid assets outperformed less liquid ones. The beta cohorts give a much clearer answer than last week. The ten highest liquidity-beta names returned an average -10.63% against -5.17% for the ten lowest, so the less liquid cohort trailed by 5.5 pp, in the direction of the print, and the medians (-8.76% and -5.10%) are 3.7 pp apart in the same direction. Last week the gap was 1.1 pp in the factor's direction on a positive print. The gap holds under cuts at either end. Excluding BCH, which entered the highest ten and fell 18.49%, the highest ten average -9.76% and trail by 4.6 pp, and with QNT (-14.93%) also removed the gap is 3.9 pp. Excluding ICP, the only riser in the lowest ten, the gap is 4.5 pp. The cohort gap is much wider than the factor's 0.42% loss, so the week reads as a sell-off in which thinner high-beta tokens fell furthest, not as a broad rotation toward liquid assets. The highest ten mixes interoperability, perpetuals-exchange, meme-launchpad, scaling, storage, DEX, Bitcoin-fork and meme tokens, with BCH entering at 0.19 as VVV left. ZRO's beta rose to 1.30 from 1.19, extending its lead, and Hyperliquid (HYPE, 1.02) moved ahead of QNT (1.01). The lowest ten holds AI, payments, enterprise, real-world-asset, layer-1, lending, computing and identity tokens, with Avalanche (AVAX) entering at -0.38 as RENDER left. AVAX's score fell by 1.66 to -1.80, NEAR's rose by 1.31 to -1.61, and QNT's rose by 1.26 to 0.13, a second straight move toward the less liquid side that left it on the short side. Four names changed sides, Solana (SOL) and Litecoin (LTC) to the long side and XLM and Ether (ETH) to the short, and SOL, LTC and ETH reversed last week's moves.
What Factors are Driving Markets
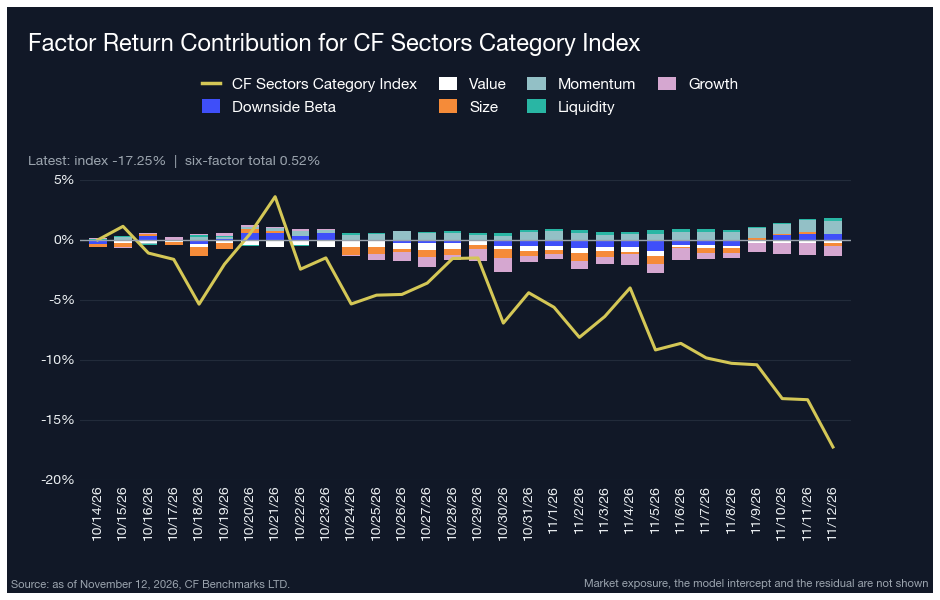
Across the CF DACS Sectors universe, factor contributions total 0.52% over the trailing 30 days against an index return of -17.25%, so the factors sit 17.8 pp above the index, compared with 15.8 pp above it last week as published. That is 2.0 pp wider, but two larger moves offset each other. The window roll narrowed the gap to 7.2 pp, as the sessions from October 7 to October 13 left the window and took 7.0 pp of loss off the index and 1.5 pp of gain off the six-factor total. This week widened it by 10.6 pp, with the index down 8.1 pp and the six factors up 2.5 pp. Momentum (1.09%) is the largest contributor for a second week, up from 0.58%, followed by Downside Beta (0.47%) and Liquidity (0.25%), with Size (-0.25%) and Value (-0.27%) small drags and Growth (-0.78%) the largest drag for a third week running, after -1.03% and -1.22%. The index fell 9.30% on the week, and one token accounts for nearly half of it. Dogecoin (DOGE), at 44.41% of the weight at the start of the week, fell 9.14% for about 4.1 pp of the decline, and Uniswap (UNI), at 14.01%, fell 12.06% for about 1.7 pp. ENA (-14.80%) and Pump.fun (PUMP, -14.64%) trailed the index by 5.5 pp and 5.3 pp, while MORPHO (-4.10%) and Shiba Inu (SHIB, -5.47%) finished 5.2 pp and 3.8 pp ahead. The six factors shown leave out Market exposure, which the model also includes along with an intercept and a token-specific residual. The Sectors model carries a Market beta of 1.34 with an R2 of 0.81. On a 30-day log basis that also counts the October 14 session, the index's -23.77% splits into about -23.23% from Market exposure, -3.32% from the intercept, 2.26% from the residual and 0.52% from the six factors. Sectors lost with the Market, and the six style factors neither cushioned the loss nor added to it in any meaningful way. Growth is the contribution to track.
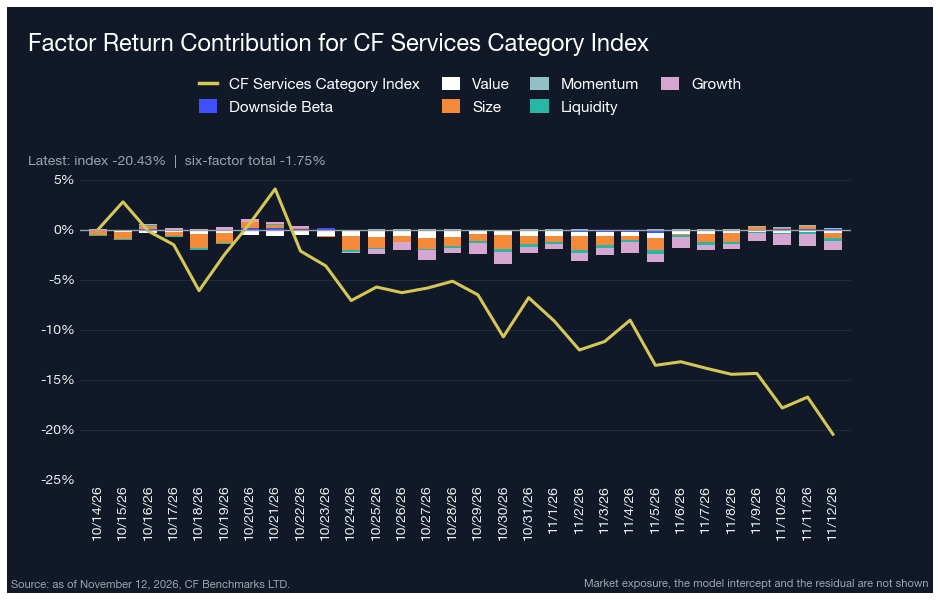
In the CF DACS Services universe, factor contributions total -1.75% against an index return of -20.43%, so the factors sit 18.7 pp above the index, compared with 18.4 pp above it last week as published. The roll narrowed the gap to 10.4 pp, taking 6.9 pp of loss off the index and 1.1 pp of gain off the six-factor total, and this week widened it by 8.3 pp, with the index down 6.9 pp and the six factors up 1.4 pp. No factor is a meaningful contributor. Downside Beta (0.14%) and Momentum (0.11%) are marginally positive, Size (-0.47%), Liquidity (-0.32%) and Value (-0.32%) are small drags, and Growth (-0.87%) is the largest drag for a third week running, after -1.12% and -1.30%. Size, the largest contributor two weeks ago at 2.04%, is now a drag. The index lost 8.40% on the week, and two tokens account for more than half of it. LINK, at 42.98% of the weight at the start of the week, fell 7.10% for about 3.1 pp, and QNT, at 13.56%, fell 14.93% for about 2.0 pp. QNT trailed the index by 6.5 pp and Worldcoin (WLD, -12.34%) by 3.9 pp, while RENDER (-1.51%) and Bittensor (TAO, -4.65%) finished 6.9 pp and 3.8 pp ahead. The Services model carries a Market beta of 1.33 with an R2 of 0.81. Of the index's -28.57% log return over the window, Market exposure accounts for about -23.08%, the intercept -2.17%, the residual -1.58% and the six factors -1.75%. The residual is down from -5.5% last week, so Market exposure now accounts for about four fifths of the loss. With LINK near 43% of the index, one token's move still drove Services more than any factor did.
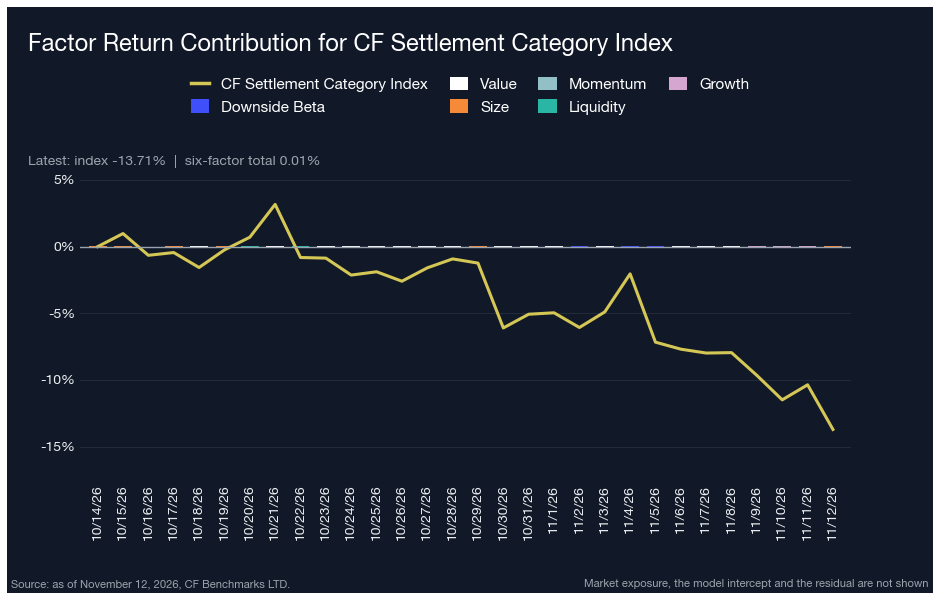
The Settlement universe, dominated by Bitcoin at about 75% of the index, again shows the weakest link to the style factors, which is expected because Market exposure sits outside the set. Factor contributions total 0.01% against an index return of -13.71%, so the factors sit 13.7 pp above the index, compared with 10.2 pp above it last week as published, and no single factor contributes more than 0.03% in either direction. The roll narrowed the gap to 7.2 pp, as 3.0 pp of loss left the index, and this week's move widened it by 6.5 pp, with the index down 6.6 pp and the six factors down 0.1 pp. The model's Market beta for Settlement is 0.99 with an R2 of 1.00, and Market exposure accounts for about -17.21% of the index's -17.17% log return, so the index tracked the Market essentially one for one. The index lost 7.21% on the week. BTC fell 6.01% for about 4.5 pp of the decline and ETH fell 10.26% for about 1.2 pp, and 15 of 17 constituents fell. XRP (-16.56%) and BCH (-18.49%) trailed the index by 9.4 pp and 11.3 pp, at roughly 4% and 0.2% of the weight, while ICP (+3.18%) and TON (+1.02%) were the only risers, 10.4 pp and 8.2 pp ahead on weights of 0.2% or less. Style contributions in Settlement read near zero while BTC holds three quarters of the weight.
Appendix: CF Factor Methodology
Market Factor
The market factor captures the broad, systematic risk that permeates the digital asset ecosystem. It reflects aggregate influences such as macroeconomic conditions, investor sentiment, and overall market volatility. As such, this factor is defined by the daily returns of the CF Broad Cap (Free Float Market Cap Weight) Index, offering a comprehensive and capitalization-weighted representation of the asset class.
Size Factor
The size factor captures the return differential associated with asset scale, reflecting the hypothesis that smaller-cap digital assets tend to outperform their larger-cap counterparts. This effect is understood to compensate for elevated operational and financial risks while exploiting potential market inefficiencies. In this framework, the size factor is defined by each asset’s fully diluted market capitalization. The value is sign-inverted so that higher z-scores are assigned to smaller assets and vice-versa.
Value Factor
The value factor reflects a protocol’s ability to generate economic output relative to its capital base and market valuation, combining measures of both efficiency and user engagement. It is constructed as the average z-score of two key ratios: transaction fees relative to total value locked (Fees/TVL) and daily active users relative to market capitalization (DAU/MCap). This composite metric captures how productively a protocol utilizes its resources while also serving as a proxy for user-driven demand. A higher combined score indicates efficient resource utilization and strong user engagement.
Momentum Factor
The momentum factor captures short-term price persistence by identifying assets that have recently exhibited strong performance. It is computed as the average z-score of two metrics: the 2 weeks cumulative performance and the 2 weeks risk-adjusted cumulative performance. This approach aligns with established findings in traditional financial literature and demonstrates empirical relevance in digital assets, where price trends tend to exhibit momentum over short horizons.
Growth Factor
The growth factor captures the expansion of a protocol’s network activity and user adoption. In the context of digital assets, it reflects metrics such as fee generation and user engagement, which serve as indicators of increased platform utilization and operational scale. The factor is defined as the average z-score of 30-day fee growth and 30-day weekly active user growth, thereby identifying assets exhibiting consistent and measurable increases in underlying network usage.
Downside Beta
The downside beta factor captures an asset’s sensitivity to adverse market conditions by isolating its behavior during periods of negative market returns. Empirical evidence shows that assets with lower downside beta tend to outperform their higher-beta counterparts over the long-term, due to their reduced participation in market drawdowns and more stable return profiles during periods of elevated volatility. As such, it is estimated through a regression of the asset’s daily returns over the most recent four-week period against market returns observed exclusively during negative sessions. The resulting value is sign-inverted to ensure that assets with lower downside exposure are assigned higher z-scores.
Liquidity Factor
The liquidity factor captures the ease with which a digital asset can be traded without significantly impacting its price. Empirical evidence shows that illiquid assets tend to command a higher risk premium than their more liquid counterparts, serving as compensation for trading friction and price volatility. To quantify this, the factor is measured using token turnover, defined as trading volume as a percentage of circulating supply. The value is sign-inverted such that higher z-scores are assigned to less liquid assets.
For further detail, view the CF Factors Methodology Document, the CF Factor Data Suite, and Our paper “A Factor Model for Digital Assets” in Springer Nature’s Mathematical Research for Blockchain Economy.
The information contained within is for educational and informational purposes ONLY. It is not intended nor should it be considered an invitation or inducement to buy or sell any of the underlying instruments cited including but not limited to cryptoassets, financial instruments or any instruments that reference any index provided by CF Benchmarks Ltd. This communication is not intended to persuade or incite you to buy or sell security or securities noted within. Any commentary provided is the opinion of the author and should not be considered a personalised recommendation. Please contact your financial adviser or professional before making an investment decision.
Note: Some of the underlying instruments cited within this material may be restricted to certain customer categories in certain jurisdictions.
Factor Friday - November 13, 2026
Size led CF Benchmarks' factor table at 0.78% as the Market fell 7.25%, its largest weekly loss since June. Liquidity still leads over four weeks at 1.57%, while Downside Beta, last week's leader, fell 2.60%. Only 2 of 35 Broad Cap tokens finished higher.
Mark Pilipczuk
Suspension of MEXC as a Contributed Exchange from Token Market Price Benchmarks Series
The Administrator announces the suspension of MEXC as a Contributed Exchange for all Token Market Price Benchmarks Series products
CF Benchmarks
Changes to the Token Market Price Benchmarks Series - Market Prices – 10 November 2026
The Administrator has confirmed changes to the Token Market Price Family for the period 03 November 2026 to 10 November 2026
CF Benchmarks
By clicking Accept, you consent to CF Benchmarks's use of cookies.
Visit Cookie Settings to learn how CF Benchmarks uses cookies and to adjust your preferences.